 Indietro
Financial Accounting Key Concepts and Practices ch1 2 3 9/29
 02:35

Termini in questo insieme (20)
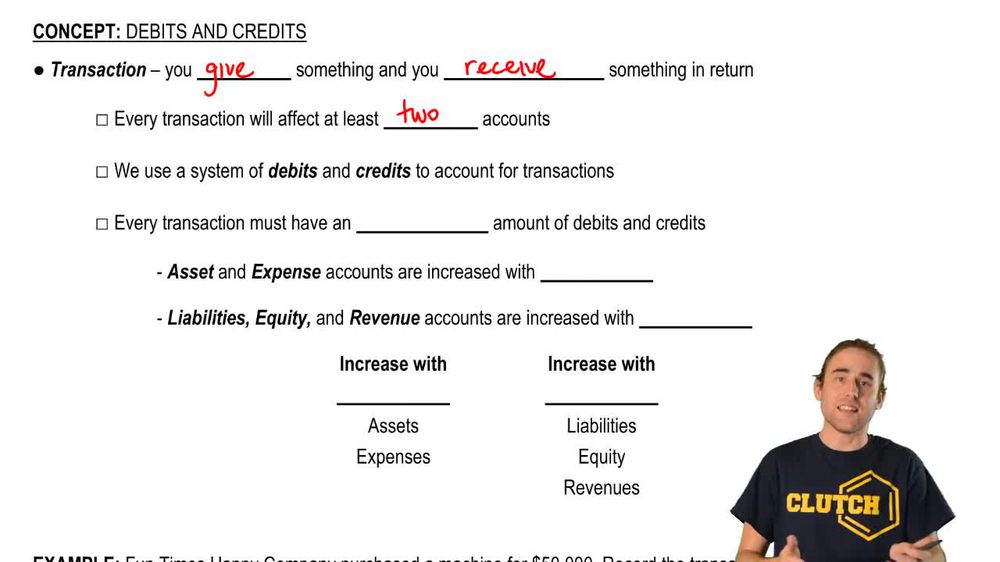
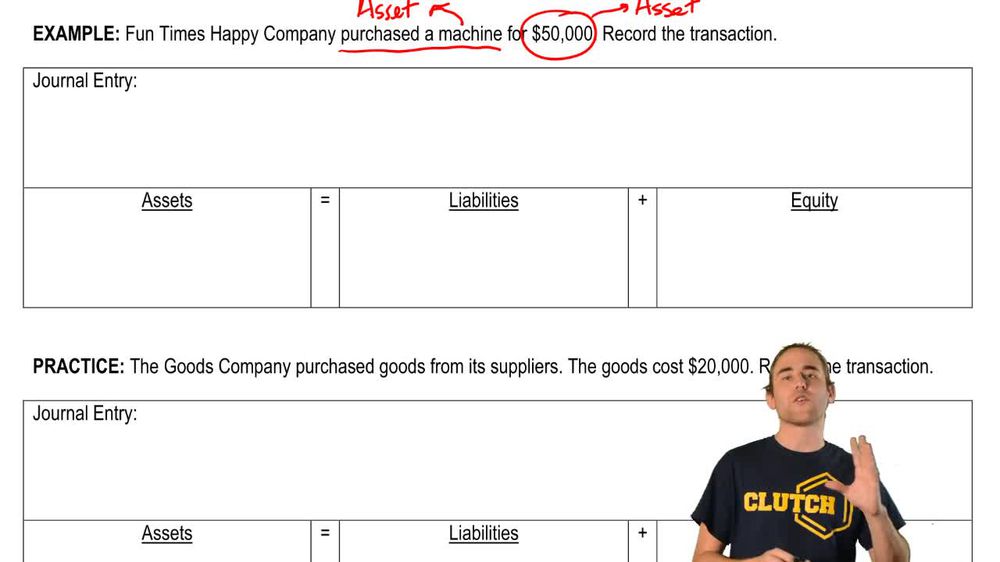
The system records each transaction in at least two accounts, ensuring debits equal credits. It overcomes the template approach's limitations by providing detailed, balanced financial data.
Each account has a normal balance (debit or credit) used to increase it. To decrease, the opposite entry is made, ensuring the accounting equation stays balanced.
1) Opening balances, 2) Transaction analysis, 3) Journal recording, 4) Posting to ledger, 5) Trial balance, 6) Adjustments, 7) Adjusted trial balance, 8) Financial statements, 9) Closing entries.
Chart of accounts must reflect needed info for management, external users, and compliance. Changes mid-year can disrupt reporting; deactivation at year-end preserves data consistency.
Permanent accounts (assets, liabilities, retained earnings) carry balances year to year. Temporary accounts (revenues, expenses, dividends) reset to zero each period.
Transactions are recorded chronologically with debited accounts listed first and credited accounts indented below, showing date, account names, and amounts debited/credited.
The ledger contains all accounts and their transactions, updated frequently to provide current balances for each account.
Adjusting entries recognize revenues and expenses in the correct period, following revenue recognition and matching principles, without involving cash.
Accruals: recognize revenue/expense before cash changes hands. Deferrals: recognize revenue/expense after cash is received or paid.
An account with a balance opposite to its normal balance, e.g., a contra asset has a credit balance instead of a debit.
Closing entries reset temporary accounts to zero and transfer their balances to retained earnings to prepare for the next accounting period.
1) Close revenues to Income Summary, 2) Close expenses to Income Summary, 3) Close Income Summary to Retained Earnings, 4) Close Dividends to Retained Earnings.
Closing entries are made at the end of each accounting year to reset temporary accounts and update retained earnings.
They transfer balances to retained earnings and reset temporary accounts to zero for the new period.
Every transaction affects at least two accounts so that total debits equal total credits, keeping the equation balanced.
Evaluating source documents to determine which accounts to debit and credit for each transaction.
To verify that total debits equal total credits before preparing financial statements.
Prepared after adjustments to confirm accounts remain balanced before financial statements are made.
Includes Income Statement, Statement of Financial Position (Balance Sheet), and others summarizing financial performance and position.
Can cause gaps and inconsistencies in reporting, making year-to-year comparisons difficult.