Skip to main content
Financial Accounting
Il mio corso
Impara
Preparazione agli esami
AI Tutor
Guide di studio
Flashcard
Esplora
Prova l'app
Il mio corso
Impara
Preparazione agli esami
AI Tutor
Guide di studio
Flashcard
Esplora
Prova l'app
Indietro
GAAP vs. IFRS: Classified Balance Sheet definitions
Puoi toccare per girare la carta.
GAAP
Puoi toccare per girare la carta.
👆
GAAP
U.S. accounting standards set by FASB, emphasizing historical cost and a specific balance sheet format.
Avanzamenti del tracciato
I pulsanti di controllo sono stati cambiati in modalità "navigazione".
1/15
Flashcard correlate
Pratica correlata
Video consigliati
GAAP vs. IFRS: Classified Balance Sheet quiz #1
GAAP vs. IFRS: Classified Balance Sheet
10 Termini
GAAP vs. IFRS: Classified Balance Sheet
15. GAAP vs IFRS
10 Problemi
Argomento
GAAP vs. IFRS: Recording Differences
15. GAAP vs IFRS
10 Problemi
Argomento
15. GAAP vs IFRS
13 Argomenti
13 Problemi
Capitolo
VideoThumbView.guidedCourse
06:27
GAAP vs. IFRS: Classified Balance Sheet
526
views
14
rank
Termini in questo insieme (15)
Nascondere definizioni
GAAP
U.S. accounting standards set by FASB, emphasizing historical cost and a specific balance sheet format.
IFRS
International accounting standards set by IASB, allowing asset revaluation and using different balance sheet terminology.
FASB
U.S. organization responsible for establishing and updating generally accepted accounting principles.
IASB
International body that develops and issues global accounting standards for financial reporting.
Classified Balance Sheet
Financial statement dividing assets and liabilities into current and long-term categories using a one-year threshold.
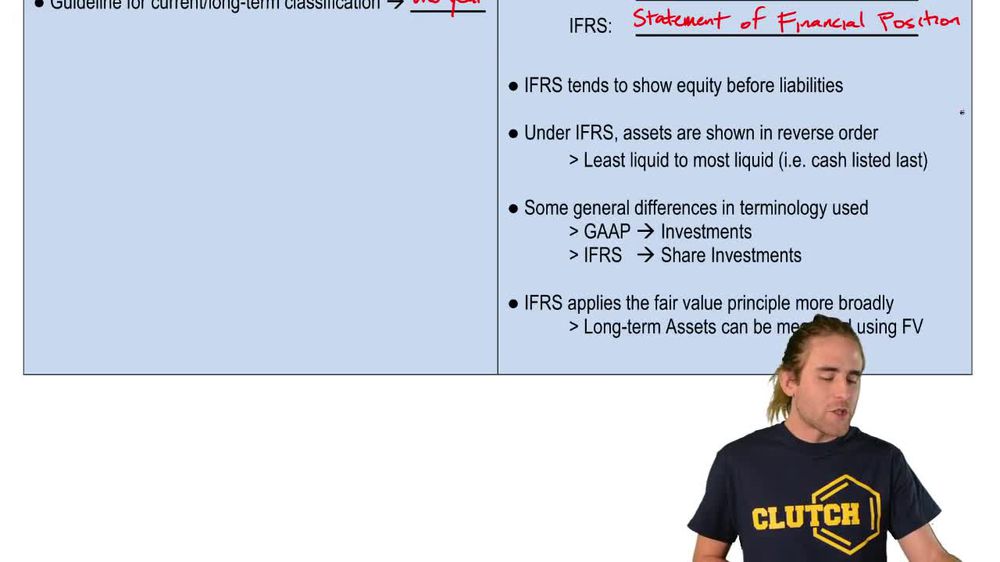
Statement of Financial Position
IFRS term for the balance sheet, typically listing equity before liabilities and assets in reverse liquidity order.
Historical Cost Principle
Accounting guideline requiring assets to be recorded at their original purchase price, ensuring consistency over time.
Fair Value Principle
IFRS guideline allowing assets to be updated to reflect current market values, resulting in more frequent valuation changes.
Current Assets
Resources expected to be converted to cash or used up within one year, such as cash and receivables.
Long-term Assets
Resources expected to provide economic benefit beyond one year, including equipment and long-term investments.
Current Liabilities
Obligations due within one year, such as accounts payable and short-term loans.
Long-term Liabilities
Obligations not due within the next year, including bonds payable and long-term loans.
Equity
Residual interest in assets after deducting liabilities, often presented before liabilities under IFRS.
Liquidity
Measure of how quickly assets can be converted to cash, with IFRS listing assets in reverse order of this characteristic.
Share Investments
IFRS term for investments in other companies' shares, equivalent to 'investments' under GAAP.
 IndietroIndietro
 06:27
