Skip to main content
Financial Accounting
Il mio corso
Impara
Preparazione agli esami
AI Tutor
Guide di studio
Flashcard
Esplora
Prova l'app
Il mio corso
Impara
Preparazione agli esami
AI Tutor
Guide di studio
Flashcard
Esplora
Prova l'app
Indietro
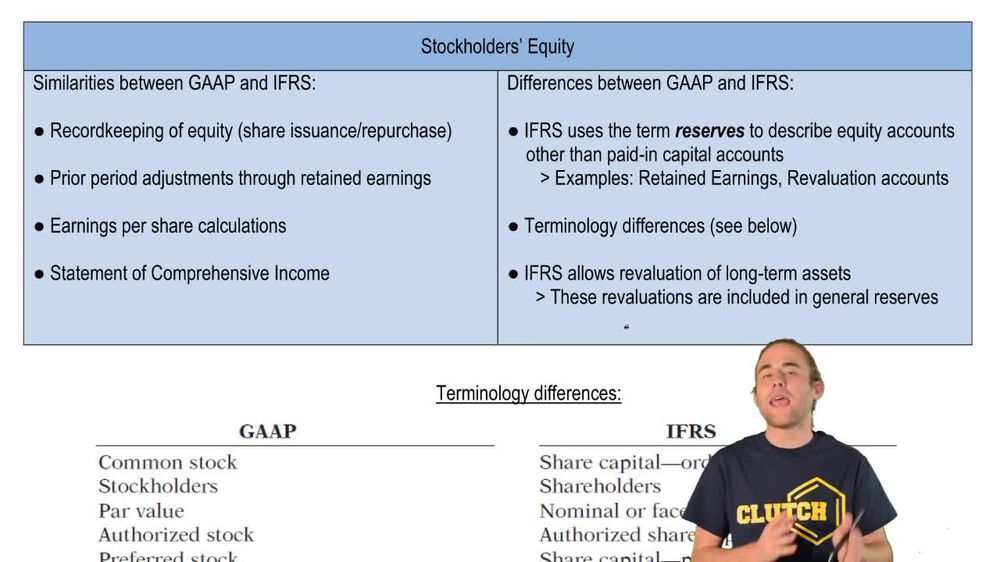
GAAP vs. IFRS: Stockholders' Equity definitions
Puoi toccare per girare la carta.
GAAP
Puoi toccare per girare la carta.
👆
GAAP
A set of accounting rules established by FASB, primarily used in the United States for financial reporting.
Avanzamenti del tracciato
I pulsanti di controllo sono stati cambiati in modalità "navigazione".
1/15
Flashcard correlate
Pratica correlata
Video consigliati
GAAP vs. IFRS: Stockholders' Equity quiz
GAAP vs. IFRS: Stockholders' Equity
15 Termini
GAAP vs. IFRS: Stockholders' Equity
15. GAAP vs IFRS
10 Problemi
Argomento
GAAP vs. IFRS: Statement of Cash Flows
15. GAAP vs IFRS
10 Problemi
Argomento
15. GAAP vs IFRS
13 Argomenti
13 Problemi
Capitolo
VideoThumbView.guidedCourse
03:39
GAAP vs. IFRS: Stockholders' Equity
654
views
5
rank
Termini in questo insieme (15)
Nascondere definizioni
GAAP
A set of accounting rules established by FASB, primarily used in the United States for financial reporting.
IFRS
International accounting standards developed by the IASB, used globally for financial statement preparation.
FASB
The U.S. organization responsible for creating and updating generally accepted accounting principles.
IASB
The international body that develops and issues International Financial Reporting Standards.
Stockholders' Equity
The residual interest in a company's assets after deducting liabilities, including paid-in capital and retained earnings.
Paid-in Capital
Funds contributed by shareholders through the purchase of stock, including common and preferred shares.
Treasury Stock
Shares that were issued and later reacquired by the company, reducing total stockholders' equity.
Retained Earnings
Accumulated net income not distributed as dividends, often included in reserves under IFRS.
Reserves
Under IFRS, items in equity not classified as paid-in capital, such as retained earnings and revaluation accounts.
Revaluation Accounts
Equity accounts under IFRS reflecting adjustments from revaluing long-term assets.
Comprehensive Income
Total change in equity from net income and other complex items not included in net income.
Net Income
The profit remaining after all expenses, taxes, and costs are subtracted from total revenue.
Earnings Per Share
A financial metric showing the portion of a company's profit allocated to each outstanding share.
Prior Period Adjustments
Corrections to previously issued financial statements, typically affecting retained earnings.
Change in Accounting Principle
A switch in accounting methods, such as from weighted average to FIFO, requiring retroactive adjustments.
 IndietroIndietro
 03:39
