 Back
Chapter 1 Definitions
 01:42

Terms in this set (22)
Scarcity
Our inability to satisfy our wants. We want more than we can get and our inability to get everything that we want is called scarcity. LIMITED resources
Incentive
A reward that encourages an action or a penalty that discourages one
Economics ( 2 types)
The social science that studies the choices that individuals, businesses, governments and entire societies make as they cope with scarcity and the incentives that influence and reconcile those choices
Microeconomics
The study of the choices that individuals and businesses make, the way these choices interact in markets and the influence of governments
Macroeconomics
The study of the performance of the national economy and the global economy
Factors of Production
The resources used to produce goods and services:
Land
Labour
Capital
Entrepreneurship
Self interest
The choices that you think are the best ones available to you are choices made in your self-interest
Social interest
Choices that are the best ones for society as a whole
Efficient
Not possible to make someone better off without making someone else worse off
Human Capital
The knowledge and skill that people obtain from education, on the job training and work experience
The Gender Pay Gap
The gap between the average hourly earnings of women and men
Market Capitalism
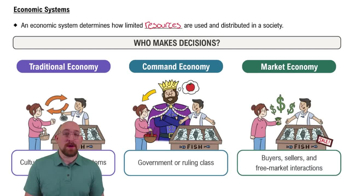
An economic system in which individuals own land and capital and are free to buy and sell land, capital, and goods and services in markets
Centrally Planned Socialism
An economic system in which the government owns all the land and capital, directs workers to jobs and decides what, how, and for whom to produce
Tradeoff
An exchange; giving up one thing to get something else
Rational Choice
Is one that compares costs and benefits and achieves the greatest benefit over cost for the person making the choice
The Opportunity Cost
The highest-valued alternative that must be given up to get something
Marginal benefit
The benefit you receive when you increase an activity
Marginal Cost
The opportunity cost you incur when you increase an activity
Economic Model
a description of some aspect of the economic world that includes only those features that are needed for the purpose at hand
Positive statements
a statement about what is. It says what is currently believed about the way the world operates
May be right or wrong but can be checked by testing against the facts
Normative statements
a statement about what should be. It depends on values and cannot be tested.
Goods and Services
The objects that people value and produce to satisfy wants
Goods are physical objects such as smartphones and automobiles
Services are tasks performed for people such as smartphone service and auto-repair service