 Back
Completing the Accounting Cycle: Financial Statements, Closing Entries, and Business Performance
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Completing the Accounting Cycle
Overview
This chapter covers the final steps in the accounting cycle, focusing on the preparation of financial statements, closing entries, post-closing trial balance, and evaluating business performance using the current ratio. It is essential for students to understand these processes to ensure accurate financial reporting and analysis.
Preparation of Financial Statements
Types of Financial Statements
Financial statements are prepared from the adjusted trial balance and provide a comprehensive overview of a company's financial position and performance.
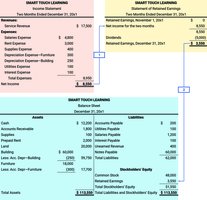
Income Statement: Reports revenues and expenses, calculating net income or net loss for the period.
Statement of Retained Earnings: Shows changes in retained earnings due to net income (or net loss) and dividends.
Balance Sheet: Reports assets, liabilities, and stockholders’ equity as of the last day of the period.
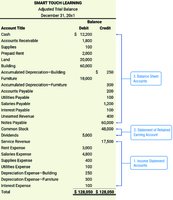
Relationships Among Financial Statements
Net income or net loss from the income statement flows to the statement of retained earnings.
Ending retained earnings from the statement of retained earnings flows to the balance sheet.
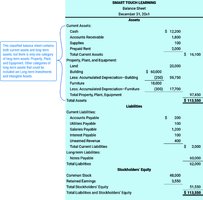
Classified Balance Sheet
A classified balance sheet organizes assets and liabilities into specific categories, enhancing clarity and usefulness for decision-making.
Assets: Listed in order of liquidity.
Current Assets: Will be converted to cash, sold, or used up within 12 months or the operating cycle.
Long-term Assets: Not converted to cash or used up within one year or the operating cycle. Includes long-term investments, property, plant, and equipment, and intangible assets.
Liabilities:
Current Liabilities: Must be paid within one year or the operating cycle.
Long-term Liabilities: Due after one year or the operating cycle.
Stockholders’ Equity: Represents owners’ claims to assets after liabilities are paid.
Closing Entries and the Closing Process
Purpose and Process
The closing process ensures that temporary accounts are reset for the next accounting period, allowing accurate measurement of net income for each period.
Temporary Accounts: Revenues, expenses, Income Summary, and Dividends. Closed at period end.
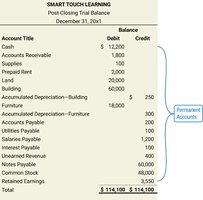
Permanent Accounts: Asset, liability, Common Stock, and Retained Earnings. Not closed at period end.
Steps in Closing Temporary Accounts
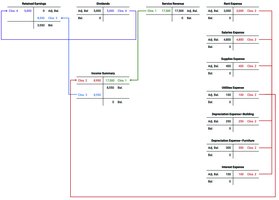
Close Revenue Accounts: Transfer balances to Income Summary.
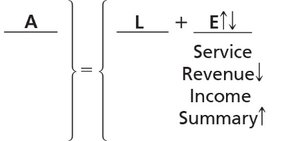
Close Expense Accounts: Transfer balances to Income Summary.
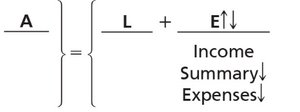
Close Income Summary: Transfer net income or net loss to Retained Earnings.
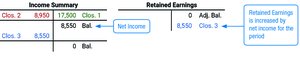
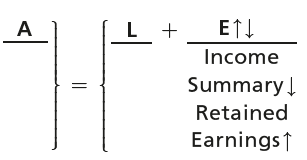
Close Dividends: Transfer balance to Retained Earnings.
Closing Entries for Net Loss
If a business has a net loss, the closing entry to close the Income Summary account decreases Retained Earnings.
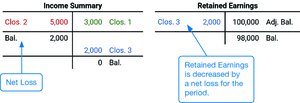
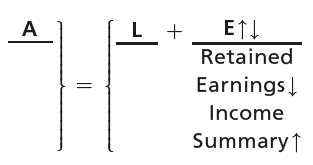
Summary of Closing Entries
Journalizing and posting closing entries ensures all temporary accounts are zeroed out and permanent accounts are carried forward.
Post-Closing Trial Balance
Purpose and Preparation
The post-closing trial balance lists only permanent accounts and their balances after closing entries are posted, marking the end of the accounting cycle.
The Accounting Cycle
Definition and Steps
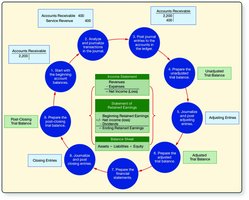
The accounting cycle is the sequence of steps followed to produce financial statements for a specific period, starting with beginning balances and ending with the post-closing trial balance.
Begins with asset, liability, and equity balances from the previous period.
Includes journalizing, posting, adjusting entries, preparing financial statements, and closing entries.
Evaluating Business Performance: The Current Ratio
Definition and Calculation
The current ratio measures a company’s ability to pay its current liabilities with its current assets. A higher ratio indicates better liquidity and financial health.
Formula:
Increases in the current ratio signal improvement in the ability to pay debts.
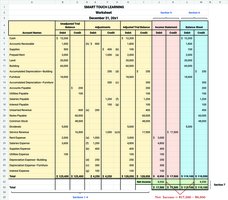
Using the Worksheet to Prepare Financial Statements
Worksheet Sections
A worksheet helps organize account balances and adjustments, facilitating the preparation of financial statements.
Section 5—Income Statement: Includes only revenue and expense accounts.
Section 6—Balance Sheet: Includes asset, liability, and equity accounts except revenues and expenses.
Section 7—Net Income or Net Loss: The balancing amount for the income statement and balance sheet sections.
Summary Table: Types of Accounts and Their Treatment
Account Type | Temporary/Permanent | Closed at Period End? |
|---|---|---|
Revenue | Temporary | Yes |
Expense | Temporary | Yes |
Income Summary | Temporary | Yes |
Dividends | Temporary | Yes |
Asset | Permanent | No |
Liability | Permanent | No |
Common Stock | Permanent | No |
Retained Earnings | Permanent | No |
Key Terms
Adjusted Trial Balance: A list of accounts and their balances after adjustments.
Classified Balance Sheet: A balance sheet that categorizes assets and liabilities.
Closing Entries: Journal entries made to close temporary accounts.
Post-Closing Trial Balance: A list of permanent accounts and their balances after closing entries.
Current Ratio: A liquidity measure calculated as current assets divided by current liabilities.
Accounting Cycle: The process of recording and processing all financial transactions of a company.
Example: Closing Process Steps
Close Service Revenue to Income Summary.
Close all expense accounts to Income Summary.
Close Income Summary to Retained Earnings.
Close Dividends to Retained Earnings.
Additional info: The chapter provides a comprehensive overview of the completion of the accounting cycle, including practical examples and diagrams to reinforce understanding.
