 Back
Inventory and Cost of Goods Sold: Financial Accounting Study Notes (Ch. 6)
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Inventory and Cost of Goods Sold
Introduction
This chapter explores the accounting for inventory, the methods used to value inventory and cost of goods sold (COGS), and the impact of these methods on financial statements and management decisions. Inventory is a critical asset for merchandising companies, and its proper accounting is essential for accurate financial reporting and analysis.
Accounting for Inventory
Definition and Classification
Inventory refers to goods purchased for resale, distinct from supplies or equipment used internally.
Inventory is classified as an asset on the balance sheet because it provides future economic benefit through eventual sale for cash.
Service vs. Merchandising Companies
Service companies do not hold inventory for resale, while merchandising companies do.
Merchandisers have two unique accounts: Inventory (balance sheet) and Cost of Goods Sold (income statement).
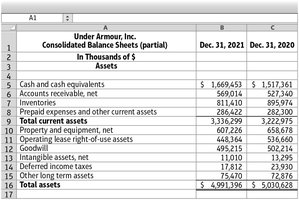
Inventory Flow and Financial Statement Impact
Inventory purchased is initially recorded as an asset. When sold, its cost is transferred to COGS, an expense on the income statement.
The basic inventory equation is:
Sales Price vs. Cost of Inventory
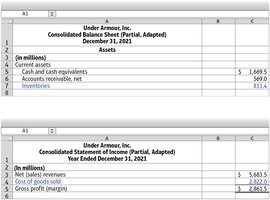
Sales revenue is based on the sale price of inventory sold.
COGS is based on the cost of inventory sold.
Gross profit (or gross margin) is the excess of sales revenue over COGS.
Determining Inventory Quantities
Physical counts at year-end verify inventory quantities.
Consigned goods: Inventory on consignment is included in the seller's records, not the retailer's.
Goods in transit: Ownership depends on shipping terms (FOB Shipping Point vs. FOB Destination).
Cost per Unit and Inventory Systems
Inventory costs may vary throughout the year, requiring methods to assign costs to COGS and ending inventory.
Perpetual system: Maintains real-time inventory records; requires POS systems.
Periodic system: Updates inventory balances at period end based on physical counts.
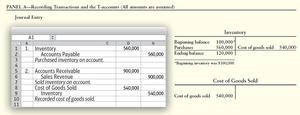
Recording Inventory Transactions (Perpetual System)
Purchases: Debit Inventory; Credit Cash/Accounts Payable.
Sales: Debit Cash/Accounts Receivable and Credit Sales Revenue; Debit COGS and Credit Inventory.
Other considerations: Freight-in (added to inventory), purchase returns/allowances (reduce inventory), purchase discounts (reduce inventory cost).
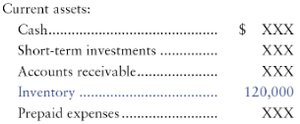
Inventory Costing Methods
Overview
The choice of inventory costing method affects reported profits, taxes, and key ratios. The main methods are:
Specific Identification: Assigns actual cost to each unique item (used for high-value, unique goods).
Average-Cost (Weighted-Average): Uses the average cost of all units available for sale during the period.
FIFO (First-In, First-Out): Assigns the cost of earliest purchases to COGS; ending inventory reflects recent costs.
LIFO (Last-In, First-Out): Assigns the cost of latest purchases to COGS; ending inventory reflects older costs.
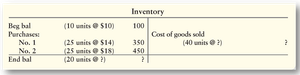
Average-Cost Method Example
Units available: 10 + 25 + 25 = 60 units; Total cost: $100 + $350 + $450 = $900.
Average cost per unit: $900 / 60 = $15.
If 40 units sold: COGS = 40 × $15 = $600; Ending inventory = 20 × $15 = $300.
FIFO and LIFO Effects
When prices rise, FIFO results in lower COGS and higher net income; LIFO results in higher COGS and lower net income (tax advantage).
When prices fall, the effects reverse.
LIFO is not permitted under IFRS.
U.S. GAAP for Inventory
Key Principles
Disclosure: Sufficient information for decision-making.
Representational Faithfulness: Accurate reporting of inventory methods and transactions.
Consistency: Use comparable methods across periods.
Lower-of-Cost-or-Market (LCM) Rule
Inventory is reported at the lower of historical cost or market value (net realizable value).
If market value drops below cost, inventory is written down to market value.
Under U.S. GAAP, write-downs cannot be reversed; under IFRS, some reversals are allowed.
ESG and Inventory Valuation
Environmental, social, and governance (ESG) factors can affect inventory value (e.g., declining demand for unsustainable products).
Companies may need to write down inventory if ESG factors reduce market value.
Inventory Analysis and Ratios
Gross Profit Percentage
Measures profitability of inventory sales.
Formula:
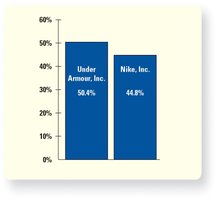
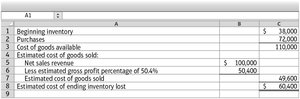
Example: Under Armour's gross profit percentage is 50.4% (each $1 of sales generates $0.504 gross profit).
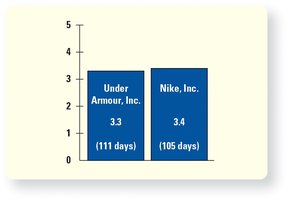
Inventory Turnover and Days Inventory Outstanding (DIO)
Inventory Turnover:
Indicates how quickly inventory is sold; higher is generally better.
DIO:
Shows average days inventory is held before sale.
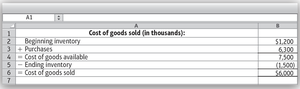
Cost-of-Goods-Sold (COGS) Model and Management Decisions
COGS Model Formula
Used to determine COGS and ending inventory, especially in periodic systems.
Formula:
Budgeting and Estimating Inventory
Managers can rearrange the COGS model to estimate required purchases:
Formula:
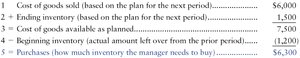
Gross Profit Method (Estimation)
Estimates ending inventory using gross profit percentage when physical count is not possible (e.g., after a fire).
Not covered in detail in this course, but the method is widely used in practice.
Excel Tools for Inventory Analysis
Using XLOOKUP for Inventory Records
Inventory items are tracked using identifiers such as SKU, UPC, or serial numbers.
The XLOOKUP function in Excel helps managers retrieve inventory details from reference files for analysis.
Useful for merging transaction data with descriptive inventory information.
Summary Table: Key Inventory Equations
Equation | Description |
|---|---|
Calculates cost of goods sold | |
Calculates gross profit | |
Measures profitability | |
Measures inventory efficiency | |
Average days inventory is held |
Additional info: Some advanced topics (e.g., LIFO liquidation, gross profit method, and inventory errors) are referenced but not covered in detail in this course. Students should focus on understanding the main inventory accounting methods, their impact on financial statements, and the use of key ratios for analysis.
