 Back
Merchandising Operations and Inventory Systems: Financial Accounting Study Notes
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Merchandising Operations
Overview of Merchandising Operations
Merchandising operations involve businesses that purchase goods for resale to customers. These businesses are classified as either wholesalers or retailers, and their main asset is merchandise inventory. - Wholesaler: Buys goods from manufacturers and sells them to retailers. - Retailer: Buys goods from wholesalers or manufacturers and sells them to consumers. - Merchandise Inventory: Goods held for resale by a merchandiser.
The Operating Cycle of a Merchandising Business
The operating cycle describes the flow of transactions in a merchandising business, from purchasing inventory to collecting cash from customers. - Step 1: Purchase inventory from a vendor. - Step 2: Sell inventory to customers. - Step 3: Collect cash from customers. 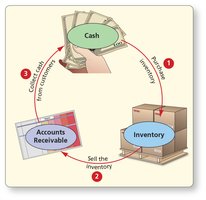
Financial Statements of Merchandisers
Merchandisers report Sales Revenue instead of Service Revenue, and include Cost of Goods Sold (COGS) and Gross Profit on their income statements. - Gross Profit: Net Sales Revenue minus Cost of Goods Sold. - Operating Expenses: Expenses other than COGS. 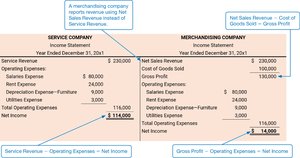
Balance Sheet Differences
The balance sheet of a merchandising company includes merchandise inventory as a current asset, unlike a service company. 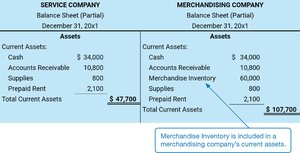
Merchandise Inventory Systems
Perpetual vs. Periodic Inventory Systems
Businesses use inventory systems to track the value of merchandise inventory. - Perpetual Inventory System: Maintains a continuous, computerized record of inventory. - Periodic Inventory System: Requires a physical count at period end to determine inventory on hand.
Purchasing Merchandise Inventory (Perpetual System)
Recording Purchases
Purchases are recorded when inventory is received, either for cash or on account. - Invoice: Seller's request for payment; also called a bill. 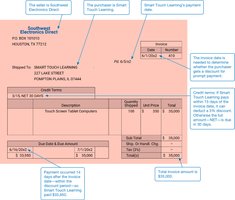
Purchase Returns and Allowances
- Purchase Return: Returning defective or unsuitable merchandise. - Purchase Allowance: Reduction in price for keeping unsatisfactory goods.
Purchase Discounts
Purchase discounts incentivize early payment. - Credit Terms: Expressed as, e.g., "3/15, n/30" (3% discount if paid within 15 days, net due in 30 days). - Example: $28,000 owed, 3% discount = $840 discount if paid within period.
Transportation Costs
Shipping terms determine ownership and responsibility for freight costs. - FOB Shipping Point: Buyer owns goods after they leave seller; buyer pays freight. - FOB Destination: Buyer owns goods at delivery; seller pays freight. 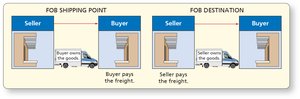 - Freight In: Cost to bring goods into purchaser's warehouse. - Freight Out: Cost to deliver goods to customer.
Net Cost of Inventory Purchased
The net cost formula is:
Selling Merchandise Inventory (Perpetual System)
Recording Sales
Sales transactions require two entries: one for sales revenue and one for the cost of goods sold. 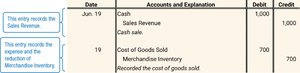
Sales on Account
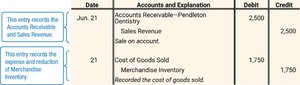
Sales may be made on account, with or without discounts. 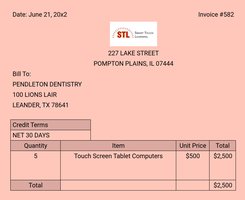
Sales Discounts
- Sales Discount: Reduction in revenue for early payment. - Example: $7,500 sale, 2% discount = $150 discount if paid within period. 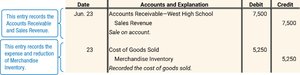
Sales Returns and Allowances
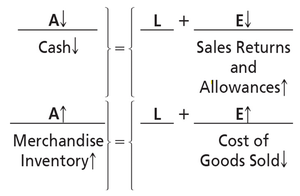
- Sales Return: Customer returns goods. - Sales Allowance: Reduction in amount owed without return of goods. 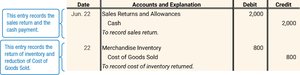
Transportation Costs—Freight Out
- Freight Out: Delivery expense to seller for shipping goods to customers.
Adjusting and Closing Accounts (Perpetual System)
Inventory Shrinkage
Inventory shrinkage is the loss of inventory due to theft, damage, or errors. Adjusting entry: 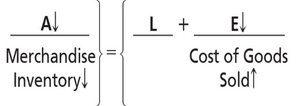
Closing Entries
Merchandisers close temporary accounts to Income Summary and then to Retained Earnings. 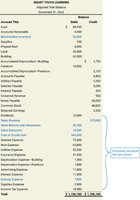
Financial Statements (Perpetual System)
Single-Step vs. Multi-Step Income Statement
- Single-Step: Groups all revenues and expenses together. 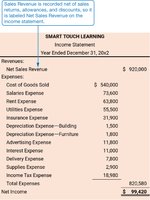 - Multi-Step: Reports subtotals for gross profit, operating income, and net income.
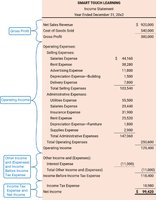
Gross Profit Percentage
Evaluating Business Performance
The gross profit percentage measures profitability above the cost of goods sold. - Formula:
Periodic Inventory System
Recording Purchases
Purchases are recorded in a Purchases account, and inventory is updated at period end. 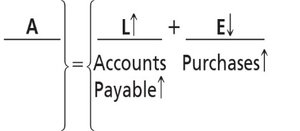
Freight In
Freight in is debited to a separate account under the periodic system. 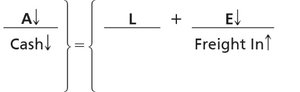
Net Cost of Inventory Purchased
Net cost is calculated at period end, combining purchases, returns, discounts, and freight in.
Sales Transactions
No running record of inventory; sales discounts and returns are handled similarly to the perpetual system. 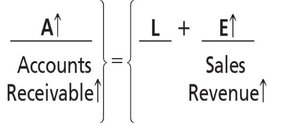
Adjusting and Closing Accounts (Periodic System)
Adjusting Entries
Ending inventory is determined by physical count; no adjustment for shrinkage. 
Closing Entries
Temporary accounts are closed via Income Summary; ending inventory and estimated returns are recorded as debits.
Financial Statements (Periodic System)
Cost of Goods Sold Calculation
At period end, cost of goods sold is calculated by combining relevant accounts.
Net Method for Sales Discounts
Recording Sales at Net Amount
Under new standards, sales are recorded at the net amount, less any sales discounts. 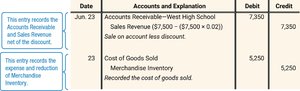 Additional info: These notes cover the full scope of merchandising operations, inventory systems, and related financial statement preparation, suitable for Financial Accounting college students.
