 Back
Plant Assets, Natural Resources, and Intangibles: Financial Accounting Study Guide
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Plant Assets, Natural Resources, and Intangibles
Introduction
This chapter covers the accounting treatment for long-term assets used in business operations, including property, plant, and equipment (PP&E), natural resources, and intangible assets. These assets are essential for generating future revenues and require specialized accounting methods to reflect their consumption, impairment, and disposal.
Accounting for the Cost of Plant Assets
Definition and Classification
Plant assets are tangible, long-lived assets used in operations, such as land, buildings, machinery, and equipment. The cost of a plant asset includes all expenditures necessary to acquire the asset and prepare it for its intended use.
Land: Includes purchase price, commissions, survey and legal fees, back property taxes, grading, clearing, and removal of unwanted buildings. Excludes land improvements (e.g., fencing, paving).
Buildings: Construction costs include architectural fees, permits, contractor charges, materials, labor, overhead, and interest during construction. Purchase costs include price, commissions, taxes, and renovation expenses.
Equipment: Includes purchase price (net of discounts), transportation, insurance in transit, taxes, commissions, installation, testing, and special platforms.
Land Improvements: Includes driveways, signs, fences, sprinkler systems, and similar items. These are depreciated over their useful lives.
Leasehold Improvements: Improvements made to leased property, depreciated or amortized over the lease term.
Lump-Sum (Basket) Purchases
When multiple assets are purchased together for a single price, the cost is allocated based on their relative market values using the relative-sales-value method.
Formula:
Capital Expenditures vs. Immediate Expenses
Definitions
Capital Expenditures: Costs that increase the asset’s capacity or extend its useful life. These are added to the asset account and depreciated over time.
Immediate Expenses: Costs that maintain the asset at its intended use (e.g., repairs and maintenance). These are expensed as incurred.
Small, immaterial costs are typically expensed immediately. Errors may occur if costs are incorrectly capitalized or expensed.
Leased Assets
Leasing allows businesses to use assets without large upfront payments. Most leases result in both an asset and a liability being recorded on the balance sheet.
Depreciation of Plant Assets
Concept and Purpose
Depreciation allocates the cost of a plant asset to expense over its useful life, reflecting wear, obsolescence, and loss of value. Land is not depreciated.
Book Value: Asset cost minus accumulated depreciation.
Depreciable Cost:
Depreciation Methods
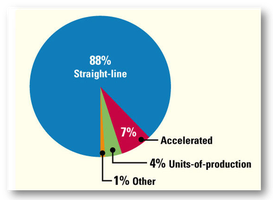
Straight-Line Method: Equal depreciation each period.
Units-of-Production Method: Depreciation based on usage.
Double-Declining-Balance Method: Accelerated depreciation, higher in early years.
Depreciation Schedules and Patterns
Depreciation schedules show yearly expense, accumulated depreciation, and book value for each method.
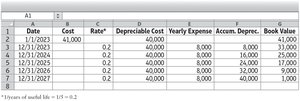
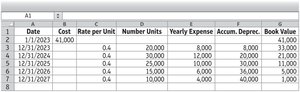
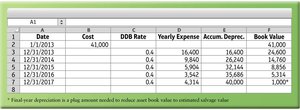
Depreciation patterns differ by method:
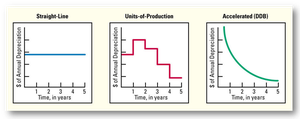
Most companies use straight-line depreciation for financial reporting:
Other Issues in Accounting for Plant Assets
Tax Depreciation
Companies often use accelerated depreciation for tax purposes to maximize deductions and conserve cash. Modified Accelerated Cost Recovery System (MACRS) is used for tax reporting but is not covered in detail here.
Depreciation for Partial Years
When assets are purchased or disposed of partway through the year, depreciation is prorated based on the period of use.
Changes in Useful Life
Managers may revise an asset’s useful life based on new information. Changes are accounted for prospectively as a change in accounting estimate.
Fully Depreciated Assets
Assets that have reached the end of their useful life may still be used, but no further depreciation is recorded. Upon disposal, both the asset and accumulated depreciation are removed from the books.
Disposal of Plant Assets
Accounting for Disposal
Depreciation must be brought up to date before disposal. The asset’s final book value is measured, and any gain or loss is recognized based on the difference between book value and proceeds received.
Gain: Sale price > book value
Loss: Sale price < book value
Natural Resources and Intangible Assets
Natural Resources
Natural resources (e.g., oil, timber) are depleted over time. Depletion is calculated similarly to units-of-production depreciation.
Formula:
Intangible Assets
Intangible assets lack physical form but carry special rights (e.g., patents, copyrights, trademarks, franchises, goodwill).
Finite Lives: Amortized over useful life.
Indefinite Lives: Not amortized; tested annually for impairment.
Asset Impairment
Impairment Testing
Assets are tested annually for impairment. If expected future cash flows are less than the asset’s net book value, the asset is impaired and its carrying value is reduced to fair value.
Rate of Return on Assets (ROA)
Definition and Calculation
ROA measures how efficiently a company uses its assets to generate net income.
Formula:
ESG Factors and Asset Accounting
Impact of ESG
Environmental, Social, and Governance (ESG) factors can affect the useful life and value of plant assets, natural resources, and intangibles. Regulatory changes, societal values, and environmental risks may lead to asset impairment or reduced useful lives.
Cash Flow Impact of Long-Lived Asset Transactions
Statement of Cash Flows
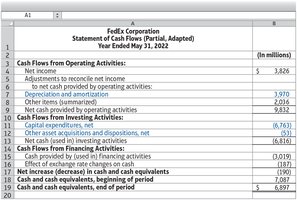
Long-lived asset transactions affect the statement of cash flows in three main ways:
Acquisitions: Investing activities (cash outflow)
Sales: Investing activities (cash inflow)
Depreciation/Amortization: Operating activities (added back to net income)
Calculating Depreciation Using Excel Functions
Excel Functions
SLN: Calculates straight-line depreciation.
DDB: Calculates double-declining-balance depreciation.
These functions simplify depreciation calculations for assets with known cost, residual value, and useful life.
Summary Table: Depreciation Methods Comparison
Method | Best For | Depreciation Pattern |
|---|---|---|
Straight-Line | Assets generating revenue evenly | Equal expense each period |
Units-of-Production | Assets worn out by use | Expense varies with usage |
Double-Declining-Balance | Assets generating more revenue early | Higher expense in early years |
