 Indietro
Chapter 3: The Adjusting Process – Financial Accounting Study Notes
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Accrual Accounting Concepts
Cash Basis vs. Accrual Basis Accounting
Understanding the difference between cash basis and accrual basis accounting is fundamental for accurate financial reporting. These methods determine when revenues and expenses are recognized in the accounting records.
Cash Basis Accounting: Revenues are recorded when cash is received, and expenses are recorded when cash is paid. This method is not permitted under GAAP and is generally used by small businesses due to its simplicity.
Accrual Basis Accounting: Revenues are recorded when earned, and expenses are recorded when incurred, regardless of when cash is exchanged. This method is required by GAAP and provides a more accurate picture of a business’s financial performance.
Example: If a company pays $1,200 for six months of insurance on May 1, under cash basis, the entire amount is expensed in May. Under accrual basis, $200 is expensed each month as the insurance is used.
The Time Period Concept, Revenue Recognition, and Matching Principles
These principles ensure that financial statements reflect the correct revenues and expenses for a specific period.
Time Period Concept: Business activities are divided into specific periods (month, quarter, year) for reporting purposes. A fiscal year is any 12 consecutive months.
Revenue Recognition Principle: Revenue is recognized when earned, not necessarily when cash is received. The five-step process includes:
Identify the contract with the customer.
Identify the performance obligations.
Determine the transaction price.
Allocate the transaction price to performance obligations.
Recognize revenue when (or as) each obligation is satisfied.
Matching Principle: Expenses are recorded in the same period as the revenues they help generate, ensuring accurate net income or loss calculation.
The Adjusting Process
Purpose and Types of Adjusting Entries
Adjusting entries are made at the end of the accounting period to ensure that revenues and expenses are recognized in the correct period. They also update asset and liability accounts to reflect their true balances.
Deferrals: Recognition of revenue or expense is deferred to a future date after cash is received or paid.
Deferred Expenses (Prepaid Expenses): Advance payments for future expenses, treated as assets until used (e.g., prepaid rent, supplies, depreciation).
Deferred Revenues (Unearned Revenues): Cash received before services are performed or goods delivered, recorded as liabilities until earned.
Accruals: Recognition of revenue or expense occurs before cash is received or paid.
Accrued Expenses: Expenses incurred but not yet paid (e.g., salaries, interest).
Accrued Revenues: Revenues earned but not yet received in cash.
Journalizing and Posting Adjusting Entries for Deferrals
Deferrals require adjusting entries to transfer amounts from asset or liability accounts to expense or revenue accounts as they are used or earned.
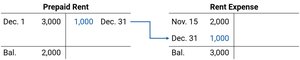
Prepaid Rent Example: If $3,000 is paid for three months’ rent, $1,000 is expensed each month as used.
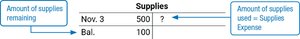
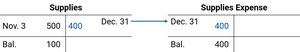
Supplies Example: If $500 of supplies are purchased and $100 remain at period end, $400 is expensed.
Depreciation: The allocation of a plant asset’s cost over its useful life. The straight-line method is commonly used:
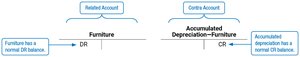
Contra Account: Accumulated Depreciation is a contra asset account, paired with the related asset account and has a normal credit balance.
Journalizing and Posting Adjusting Entries for Deferred Revenues
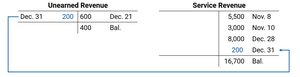
Deferred revenues are recognized as liabilities until the service is performed or the product is delivered, at which point they are transferred to revenue.
Example: $600 received in advance for services; $200 earned by period end.
Journalizing and Posting Adjusting Entries for Accruals
Accruals recognize expenses and revenues before cash is exchanged.
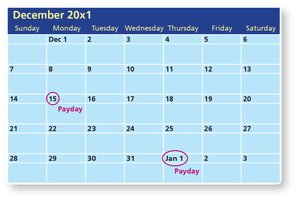
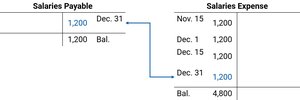
Accrued Salaries: Salaries earned by employees but not yet paid are recorded as a liability (Salaries Payable).
Accrued Interest: Interest incurred but not yet paid is recorded as Interest Expense and Interest Payable.
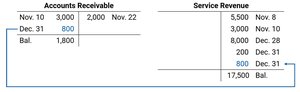
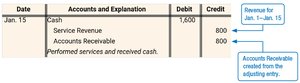
Accrued Revenues: Services performed but not yet billed are recorded as Accounts Receivable and Service Revenue.
Adjusted Trial Balance
Purpose and Preparation
An adjusted trial balance lists all accounts with their adjusted balances after posting adjusting entries. It ensures total debits equal total credits and is used to prepare financial statements.
Steps:
Journalize adjusting entries
Post adjusting entries
Prepare adjusted trial balance
Impact of Adjusting Entries on Financial Statements
Consequences of Omitting Adjusting Entries
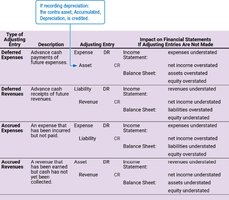
Failing to record adjusting entries results in misstated financial statements. For example, assets, liabilities, revenues, or expenses may be over- or understated, leading to incorrect net income and equity.
The Accounting Cycle
Steps in the Accounting Cycle
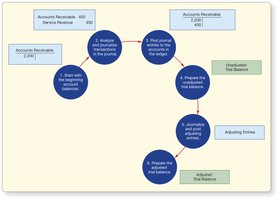
The accounting cycle is the process by which companies record transactions and prepare financial statements. Adjusting entries are a critical step in this cycle.
Typical steps include:
Analyze transactions
Journalize transactions
Post to ledger accounts
Prepare unadjusted trial balance
Journalize and post adjusting entries
Prepare adjusted trial balance
Prepare financial statements
Journalize and post closing entries
Prepare post-closing trial balance
Worksheets in the Adjusting Process
Purpose and Structure of a Worksheet
A worksheet is an internal tool used to organize and summarize data for preparing adjusting entries and the adjusted trial balance. It typically includes columns for account names, unadjusted trial balance, adjustments, and adjusted trial balance.
Summary Table: Deferral and Accrual Adjustments
Type of Adjusting Entry | Description | Adjusting Entry | Impact on Financial Statements If Not Made |
|---|---|---|---|
Deferred Expenses | Advance cash payments of future expenses | Expense DR / Asset CR | Expenses understated, net income overstated, assets overstated, equity overstated |
Deferred Revenues | Advance cash receipts of future revenues | Liability DR / Revenue CR | Revenues understated, net income understated, liabilities overstated, equity understated |
Accrued Expenses | Expenses incurred but not yet paid | Expense DR / Liability CR | Expenses understated, net income overstated, liabilities understated, equity overstated |
Accrued Revenues | Revenues earned but not yet received | Asset DR / Revenue CR | Revenues understated, net income understated, assets understated, equity understated |
