 Indietro
Chapter 5: Receivables and Revenue – Financial Accounting Study Notes
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Receivables and Revenue
Introduction
This chapter explores the accounting principles and practices related to receivables and revenue recognition. It covers the application of GAAP for revenue recognition, accounting for sales returns, allowances, and discounts, managing accounts receivable, evaluating collectability, and analyzing liquidity and receivables collectibility using financial ratios and schedules.
GAAP for Proper Revenue Recognition
Revenue Recognition Principles
Revenue is recognized when earned – typically when goods are delivered or services are performed.
Recorded at the amount of cash received or the fair market value of assets received in exchange.
Revenue recognition requires an enforceable contract (written or oral) and follows a five-step process:
Identify the contract(s) with a customer.
Identify the performance obligations.
Determine the transaction price.
Allocate the transaction price to the performance obligations.
Recognize revenue when the entity satisfies a performance obligation.
For multiple performance obligations, revenue is allocated based on relative stand-alone selling prices (SSPs).
Revenue for delivered goods is recognized when control transfers to the customer (e.g., shipment for products, over time for services).
Example: Apple Inc. recognizes revenue for hardware when shipped (FOB shipping point) and for services as delivered over time.
Shipping Terms
FOB Shipping Point: Ownership and revenue recognition occur when goods leave the seller's dock.
FOB Destination: Ownership and revenue recognition occur when goods reach the customer.
Sales Returns and Allowances
Accounting for Returns and Allowances
Customers may return unsatisfactory or damaged goods, resulting in a credit memo to their account.
Companies with significant return experience estimate returns and record them in a Sales Returns & Allowances contra-revenue account.
Sales Revenue on the income statement is reported net of returns and allowances:
Sales – Sales Returns & Allowances
Estimated returns are recorded in the same period as the related sales to comply with the matching principle.
Example: If Apple expects 1% of $200 million sales to be returned, it records $2 million in estimated returns in the same period as the sale.
Sales Discounts
Accounting for Sales Discounts
Sales discounts are incentives for early payment (e.g., 2/10, n/30 means 2% discount if paid within 10 days, net due in 30 days).
Discounts are recorded in a Sales Discounts contra-revenue account.
Net revenue is calculated as:
Sales – Sales Returns & Allowances – Sales Discounts
Example: A $2,000 sale with $800 returned and a 2% discount on the remaining $1,200 results in net revenue of $1,176.
Accounts Receivable
Types and Management of Receivables
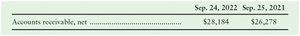
Receivables are monetary claims against others, classified as current assets.
Types include accounts receivable (from sales) and notes receivable (from lending).
Subsidiary ledgers track individual customer balances.
Effective management includes credit checks, monitoring payment habits, and separating cash handling from record-keeping.
Allowance for Uncollectible Accounts
Evaluating Collectability
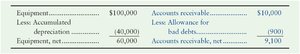
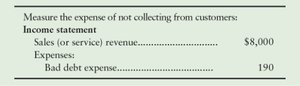
Not all receivables are collected; the allowance method estimates uncollectible accounts as an expense.
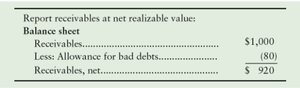
The Allowance for Uncollectible Accounts is a contra-asset account reducing accounts receivable to net realizable value (NRV):
Methods for Estimating Uncollectibles
Percent-of-Sales Method: Estimates uncollectible expense as a percentage of sales (income statement approach).
Aging-of-Receivables Method: Estimates allowance based on the age of receivables (balance sheet approach).
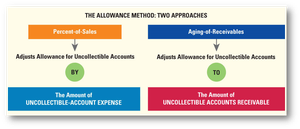
Percent-of-Sales Method Example
If total revenues are $394,328 million and the estimated uncollectible rate is 0.0002, the expense is $79 million.
The allowance balance is updated by adding the expense to the beginning balance.
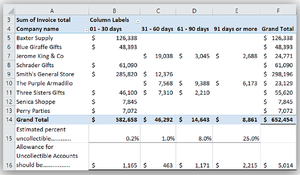
Aging-of-Receivables Method Example
Receivables are grouped by age, and different percentages are applied to each group to estimate uncollectibles.
The sum of these estimates gives the required allowance balance.
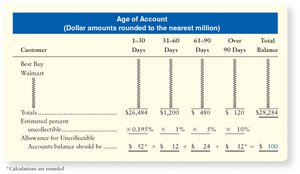
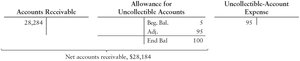
Writing Off Uncollectible Accounts
Write-Offs
When a specific account is deemed uncollectible, it is written off against the allowance account.
This does not affect the net realizable value of accounts receivable.
Direct Write-Off Method
Records expense only when a specific account is uncollectible.
Not GAAP-compliant except for immaterial amounts, as it may overstate assets and mismatches expenses and revenues.
Notes Receivable and Interest Revenue
Key Terms
Creditor: The lender or party to whom money is owed.
Debtor: The borrower or party who owes money.
Interest: The cost of borrowing, stated as an annual percentage rate.
Maturity date: When the note must be repaid.
Maturity value: Principal plus interest due at maturity.
Interest Calculation Formula:
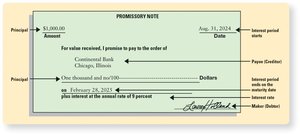
Liquidity and Receivables Ratios
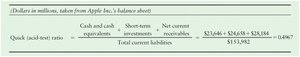
Quick (Acid-Test) Ratio
Measures a company's ability to pay current liabilities with quick assets (cash, short-term investments, receivables).
Formula:
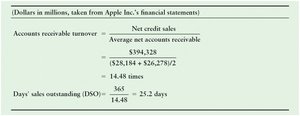
Accounts Receivable Turnover
Indicates how many times per year a company collects its average accounts receivable.
Formula:
Days' Sales Outstanding (DSO)
Shows the average number of days it takes to collect receivables.
Formula:
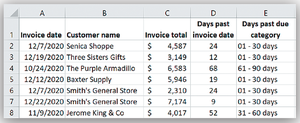
Analyzing Receivables Collectibility with Aging Schedules
Using Pivot Tables
Aging schedules summarize receivables by age category to estimate collectibility.
Pivot tables in Excel can efficiently summarize large sets of receivable data for analysis.
Summary Table: Key Methods for Estimating Uncollectible Accounts
Method | Basis | Primary Use | Key Feature |
|---|---|---|---|
Percent-of-Sales | Credit Sales | Income Statement | Estimates expense as % of sales |
Aging-of-Receivables | Receivable Age | Balance Sheet | Estimates allowance based on age |
Additional info: This chapter provides a comprehensive overview of the accounting for receivables and revenue, including practical examples, journal entries, and real-world applications using Apple Inc.'s financial statements.
