 Indietro
The Interaction of Demand and Supply: Foundations of Market Prices
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Where Prices Come From: The Interaction of Demand and Supply
The Model of a Perfectly Competitive Market
A perfectly competitive market is characterized by many buyers and sellers, identical products, and no barriers to entry for new firms. This model forms the foundation for understanding how prices are determined in markets.
Many buyers and sellers: No single participant can influence the market price.
Identical products: Goods offered by different sellers are perfect substitutes.
No barriers to entry: New firms can freely enter or exit the market.
The Demand Side of the Market
Market Demand and the Law of Demand
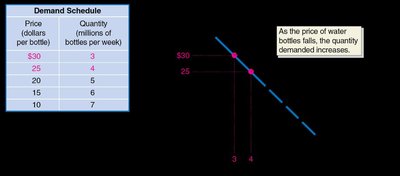
Market demand refers to the total demand by all consumers for a given good or service. The law of demand states that, holding all else constant, as the price of a product falls, the quantity demanded increases, and as the price rises, the quantity demanded decreases.
Demand schedule: A table showing the relationship between price and quantity demanded.
Demand curve: A graphical representation of the demand schedule, typically downward sloping.
Quantity demanded: The amount consumers are willing and able to purchase at a specific price.
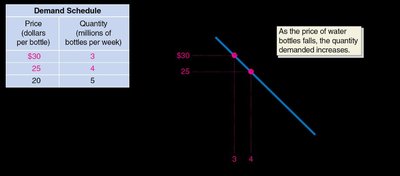
Explaining the Law of Demand
Substitution effect: When the price of a good falls, it becomes cheaper relative to other goods, leading consumers to substitute toward it.
Income effect: A lower price increases consumers' purchasing power, allowing them to buy more.
Ceteris paribus: The assumption that all other variables are held constant when analyzing the relationship between price and quantity demanded.
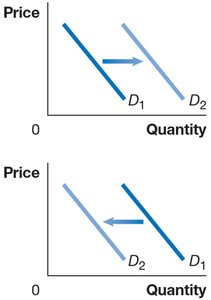
Shifts in the Demand Curve
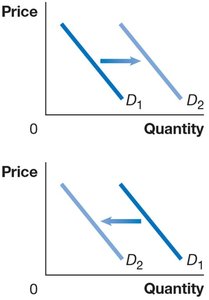
A change in a non-price determinant of demand causes the entire demand curve to shift. A shift to the right indicates an increase in demand, while a shift to the left indicates a decrease.
Increase in demand: Demand curve shifts right (D1 to D2).
Decrease in demand: Demand curve shifts left (D2 to D1).
Variables That Shift Market Demand
Income: Demand for normal goods increases with income; demand for inferior goods decreases with income.
Prices of related goods: Substitutes and complements affect demand differently.
Tastes: Changes in consumer preferences can increase or decrease demand.
Population and demographics: More buyers increase demand.
Expected future prices: Anticipation of higher future prices increases current demand.
Natural disasters and pandemics: Can temporarily alter demand for certain goods.
Normal and Inferior Goods
Normal good: Demand increases as income rises (e.g., new clothes).
Inferior good: Demand increases as income falls (e.g., second-hand clothes).
Substitutes and Complements
Substitutes: Goods used in place of each other (e.g., Big Mac and Whopper).
Complements: Goods used together (e.g., Big Mac and McDonald's fries).
Other Demand Shifters
Tastes: Changes in preferences can shift demand.
Population/Demographics: Larger or changing populations affect demand.
Expectations: Anticipated future prices influence current demand.
Natural disasters/pandemics: Can increase or decrease demand for specific goods.
Change in Demand vs. Change in Quantity Demanded
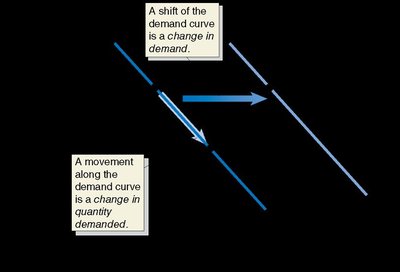
A change in the price of the product causes a movement along the demand curve (change in quantity demanded). Any other change affecting demand causes the entire demand curve to shift (change in demand).
The Supply Side of the Market
Market Supply and the Law of Supply
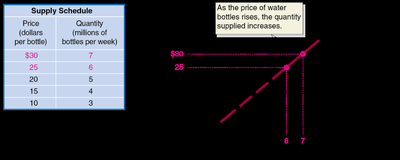
Market supply is the total quantity of a good or service that firms are willing and able to sell at various prices. The law of supply states that, holding all else constant, increases in price cause increases in quantity supplied, and decreases in price cause decreases in quantity supplied.
Supply schedule: Table showing the relationship between price and quantity supplied.
Supply curve: Graphical representation of the supply schedule, typically upward sloping.
Quantity supplied: The amount a firm is willing and able to supply at a given price.
Shifts in the Supply Curve
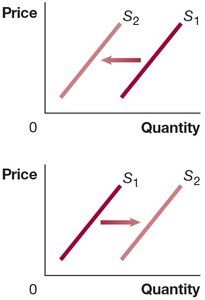
A change in a non-price determinant of supply causes the entire supply curve to shift. A shift to the right indicates an increase in supply, while a shift to the left indicates a decrease.
Increase in supply: Supply curve shifts right (S1 to S2).
Decrease in supply: Supply curve shifts left (S2 to S1).
Variables That Shift Market Supply
Prices of inputs: Higher input prices decrease supply; lower input prices increase supply.
Technological change: Improvements increase supply; setbacks decrease supply.
Prices of related goods in production: Substitutes and complements in production affect supply decisions.
Number of firms: More firms increase supply; fewer firms decrease supply.
Expected future prices: Anticipation of higher future prices may decrease current supply.
Natural disasters and pandemics: Can disrupt production and decrease supply.
Change in Supply vs. Change in Quantity Supplied
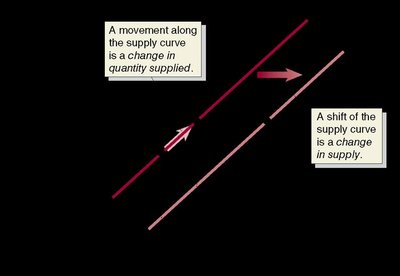
A change in the price of the product causes a movement along the supply curve (change in quantity supplied). Any other change affecting supply causes the entire supply curve to shift (change in supply).
Market Equilibrium: Putting Demand and Supply Together
Market Equilibrium
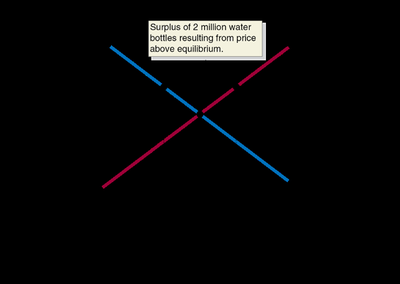
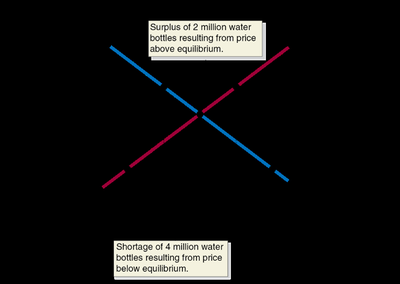
Market equilibrium occurs where the quantity demanded equals the quantity supplied. The corresponding price is the equilibrium price, and the quantity is the equilibrium quantity. In a perfectly competitive market, this is called a competitive market equilibrium.
Equilibrium price: The price at which quantity demanded equals quantity supplied.
Equilibrium quantity: The quantity bought and sold at the equilibrium price.
Surpluses and Shortages
Surplus: Occurs when the price is above equilibrium, leading to excess supply.
Shortage: Occurs when the price is below equilibrium, leading to excess demand.
The Effect of Demand and Supply Shifts on Equilibrium
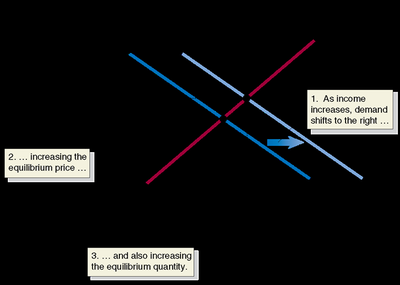
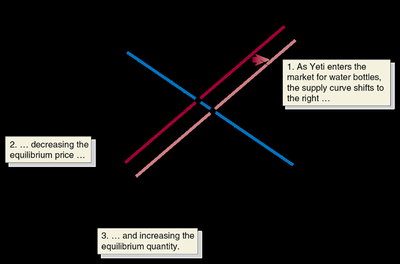
Shifts in demand or supply curves change the equilibrium price and quantity. The demand and supply model predicts the direction of these changes.
Increase in demand: Raises both equilibrium price and quantity.
Increase in supply: Lowers equilibrium price but raises equilibrium quantity.
Summary Table: Effects of Shifts in Demand and Supply
The following table summarizes how shifts in demand and supply affect equilibrium price and quantity:
Supply Curve Unchanged | Supply Curve Shifts to the Right | Supply Curve Shifts to the Left | |
|---|---|---|---|
Demand Curve Unchanged | Q unchanged P unchanged | Q increases P decreases | Q decreases P increases |
Demand Curve Shifts to the Right | Q increases P increases | Additional info: Both Q and P increase, but the magnitude depends on the size of the shifts. | Additional info: Q may increase or decrease, P increases. |
Demand Curve Shifts to the Left | Q decreases P decreases | Additional info: Q may increase or decrease, P decreases. | Additional info: Both Q and P decrease, but the magnitude depends on the size of the shifts. |
Shifts of a Curve vs. Movements Along a Curve
A shift in supply or demand changes the equilibrium, but the resulting price change causes a movement along the other curve, not a shift. For example, an increase in supply lowers price, causing a movement along the demand curve (higher quantity demanded), not a shift in demand.
Government Intervention: Price Floors and Price Ceilings
Price Floors
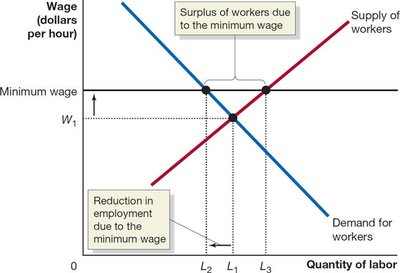
A price floor is a legally determined minimum price that sellers may receive. The minimum wage is a common example, intended to raise incomes for low-skilled workers but potentially reducing employment.
Price Ceilings
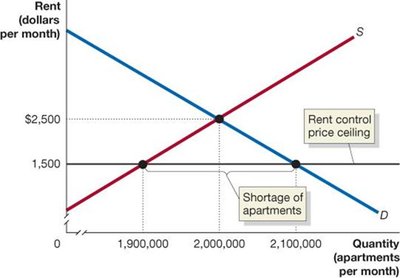
A price ceiling is a legally determined maximum price that sellers may charge. Rent control is a typical example, aiming to keep housing affordable but often resulting in shortages.
Consequences of Price Controls
Winners: Some consumers (renters) or workers (minimum wage earners) benefit from price controls.
Losers: Some suppliers (landlords, employers) and those unable to find goods or jobs at the controlled price lose out.
Illegal markets may arise when shortages occur due to price controls.
Positive vs. Normative Analysis
Economic analysis can show that price controls decrease efficiency, but whether they are 'good' or 'bad' is a normative question, depending on societal values and priorities.
