 Indietro
Trade-offs, Comparative Advantage, and the Market System: Core Concepts in Macroeconomics
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Trade-offs, Comparative Advantage, and the Market System
Scarcity and Trade-offs
Scarcity is a fundamental concept in economics, referring to the situation where unlimited wants exceed the limited resources available to fulfill those wants. Because resources are scarce, individuals, firms, and governments must make choices, leading to trade-offs. Economics provides tools to analyze and make optimal decisions regarding these trade-offs.
Scarcity: The condition that arises because resources are limited while wants are unlimited.
Trade-off: The idea that producing more of one good or service means producing less of another due to limited resources.
Example: If Ford allocates more resources to producing electric vehicles, it must reduce resources for gasoline-powered vehicles.
Production Possibilities Frontier (PPF) and Opportunity Costs
The Production Possibilities Frontier (PPF) is a curve that shows the maximum attainable combinations of two goods that can be produced with available resources and current technology. The PPF is a positive economic tool, illustrating what is possible, not what should be.
Points on the PPF: Efficient and attainable combinations of goods.
Points inside the PPF: Inefficient use of resources.
Points outside the PPF: Unattainable with current resources and technology.
Opportunity Cost: The highest-valued alternative that must be given up to engage in an activity.
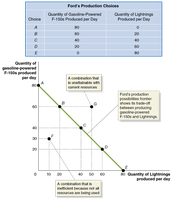
Example: Moving from producing more gasoline-powered F-150s to more electric F-150 Lightnings means giving up some gasoline-powered vehicles—the opportunity cost of producing more electric vehicles.
Increasing Marginal Opportunity Costs
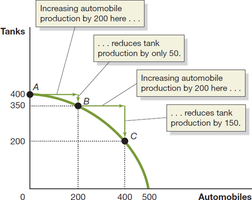
Opportunity costs are often increasing because resources are not equally suited to all tasks. As more resources are devoted to one activity, the opportunity cost of producing additional units increases.
Law of Increasing Opportunity Cost: As production of a good increases, the opportunity cost of producing an additional unit rises.
Economic Growth and Shifts in the PPF
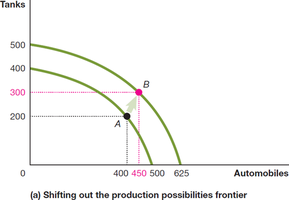
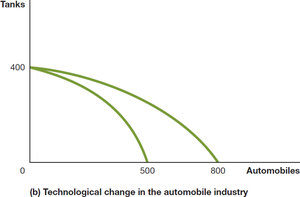
Economic growth occurs when an economy's capacity to produce goods and services increases, shifting the PPF outward. This can result from more resources or technological improvements.
Economic Growth: The ability of the economy to increase the production of goods and services.
Technological Change: Improvements in technology can shift the PPF outward for specific goods.
Application: PPF for Exam Grades
When allocating limited study time between two exams, the PPF illustrates the trade-off between grades. The curve is typically bowed outward, reflecting increasing opportunity costs—the first hours of study are more productive than the last.
Comparative Advantage and Trade
Production Possibilities Without Trade
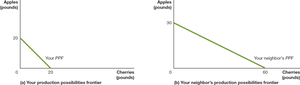
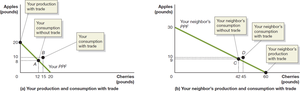
Individuals or countries face limits on what they can produce based on their resources and technology. The PPF for each shows the maximum possible output of two goods.
Specialization and Gains from Trade
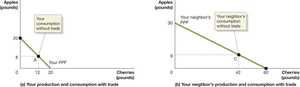
Trade allows individuals or countries to specialize in the production of goods for which they have a comparative advantage, leading to greater overall consumption and efficiency.
Specialization: Focusing resources on the production of one or a few goods.
Trade: The act of buying and selling goods and services.
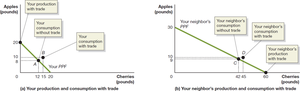
Gains from Trade: Both parties can consume more than they could without trade by specializing and exchanging goods.
Absolute and Comparative Advantage
Absolute Advantage: The ability to produce more of a good or service than competitors using the same amount of resources.
Comparative Advantage: The ability to produce a good or service at a lower opportunity cost than competitors.
Basis for Trade: Comparative advantage, not absolute advantage, determines the potential for mutually beneficial trade.
Example: Even if your neighbor is better at picking both apples and cherries, you can both benefit from trade if you specialize according to comparative advantage.
The Market System
How Markets Work
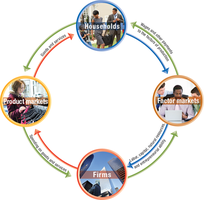
A market is a group of buyers and sellers of a good or service and the institution or arrangement by which they come together to trade. The market system coordinates the allocation of resources through the interaction of households and firms.
Households: Provide factors of production (labor, capital, natural resources, entrepreneurial ability).
Firms: Purchase factors of production and use them to produce goods and services.
The Four Factors of Production
Labor: All types of work.
Capital: Physical capital such as machinery, buildings, and tools.
Natural Resources: Raw materials like land, water, and minerals.
Entrepreneurial Ability: The skill to bring together the other factors to produce goods and services.
Factor and Product Markets
Factor Market: Where resources (labor, capital, etc.) are bought and sold.
Product Market: Where finished goods and services are bought and sold.
The Circular-Flow Diagram
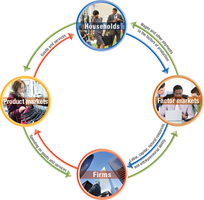
The circular-flow diagram illustrates the flow of resources, goods and services, and money in an economy. Households provide factors of production to firms, and firms provide goods and services to households. Money flows in the opposite direction of goods and services.
The Gains from Free Markets
Free markets, with minimal government intervention, have historically led to higher living standards compared to centrally planned economies. Adam Smith's concept of the "invisible hand" describes how individuals pursuing their own self-interest can lead to outcomes that benefit society as a whole.
The Market Mechanism and Price Signals
Markets use flexible prices to signal the relative value of goods and services. When consumer preferences change, prices adjust, guiding firms to allocate resources efficiently without central direction.
Invisible Hand: The self-regulating nature of the marketplace.
Flexible Prices: Essential for transmitting information and coordinating economic activity.
Knowledge and the Market System
Markets efficiently process and mobilize both general and local knowledge, allowing rapid adaptation to changing conditions. Individuals use their unique information for personal gain, but this also benefits the broader economy through improved price signals and resource allocation.
The Role of the Entrepreneur
Entrepreneurs organize the factors of production to create goods and services, often introducing innovations that drive economic growth. Their willingness to take risks is vital for the development of new products and industries.
The Legal Basis of a Successful Market System
While free markets minimize government intervention, a sound legal environment is essential. This includes protection of private property, enforcement of contracts, and an independent court system to ensure fair transactions and encourage investment.
Property Rights: The rights to use, buy, or sell property.
Enforcement of Contracts: Ensures that agreements are honored, facilitating long-term transactions.
Comparing Economic Systems: Socialism and Capitalism
Economic systems differ in the role of government and the market. Socialism, as envisioned by Karl Marx, involves government control of production, but most modern economies are mixed, with varying degrees of government involvement. Social democratic systems advocate for significant government roles in sectors like health care and education, but not full government ownership of all industries.
*Additional info: The notes above expand on the textbook outline by providing definitions, examples, and context for each concept, ensuring a self-contained and comprehensive study guide for macroeconomics students.*
