 Indietro
Understanding Individual Markets: Demand and Supply
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Understanding Individual Markets: Demand and Supply
What Is a Market?
A market is a group of buyers and sellers of a particular good or service. The interaction between buyers and sellers determines the price and quantity of goods exchanged. The concepts of supply and demand describe the behavior of people as they interact in markets.
Classification of Goods and Services
Free goods: Goods with no production costs, typically gifts of nature (e.g., sunlight, river water, air).
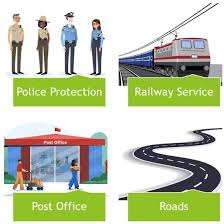
Public goods: Goods commonly used and beneficial to everyone (e.g., police protection, railway service, post office, roads).
Economic goods and services: Goods that involve production costs. Economic goods are tangible, while economic services are intangible (e.g., groceries, manufactured products).
Demand
Definition of Demand
Demand is the ability and willingness to buy specific quantities of goods in a given period at a particular price. It is determined by both the willingness and the ability to buy.
Law of Demand
As the price of a product increases, the quantity demanded decreases.
As the price of a product decreases, the quantity demanded increases.
Related Goods
Substitute goods: Goods that can replace each other (e.g., tea vs. coffee, bus ride vs. LRT ride).
Complementary goods: Goods used together (e.g., pen and ink, bread and butter).
Demand Schedule
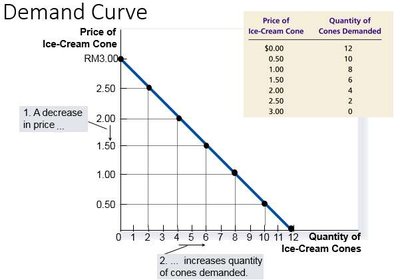
A demand schedule is a table showing the relationship between the price of a good and the quantity demanded.
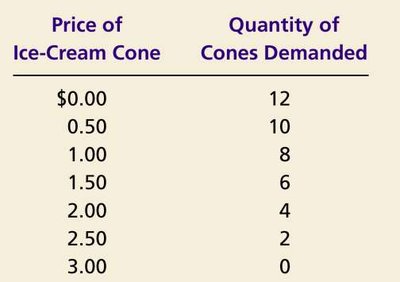
Demand Curve
The demand curve is a graphical representation of the relationship between the price of a good and the quantity demanded. It typically slopes downward, reflecting the law of demand.
Market Demand versus Individual Demand
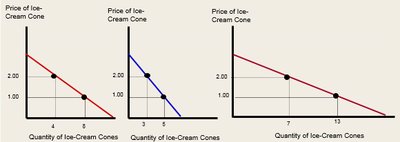
Market demand is the sum of all individual demands for a good or service. Individual demand curves are summed horizontally to obtain the market demand curve.
Determinants of Demand
Internal factor: Price of the product itself (movement along the demand curve).
External factors:
Price of related goods (substitutes and complements)
Consumers’ income (normal and inferior goods)
Consumers’ tastes and preferences
Population or number of buyers
Expectations about future prices
Festive seasons and climate
Shifts in the Demand Curve
Change in quantity demanded: Movement along the demand curve due to a change in the product's price.
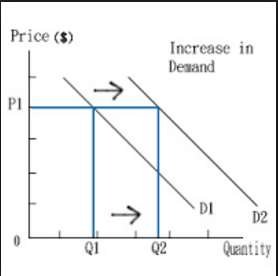
Change in demand: Shift of the demand curve due to changes in external factors (price remains constant). An increase in demand shifts the curve right; a decrease shifts it left.
Supply
Definition of Supply
Supply is the ability and willingness to sell specific quantities of goods in a given period at a particular price. It depends on both the willingness and ability to sell.
Law of Supply
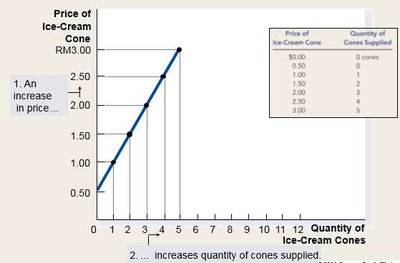
As the price of a product increases, the quantity supplied increases.
As the price of a product decreases, the quantity supplied decreases.
Supply Schedule
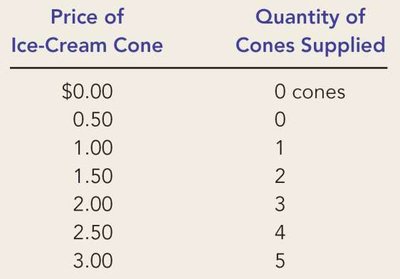
A supply schedule is a table showing the relationship between the price of a good and the quantity supplied.
Supply Curve
The supply curve is a graphical representation of the relationship between the price of a good and the quantity supplied. It typically slopes upward, reflecting the law of supply.
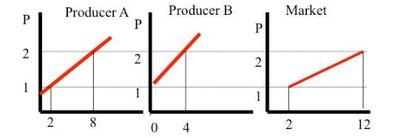
Market Supply versus Individual Supply
Market supply is the sum of all individual supplies for a good or service. Individual supply curves are summed horizontally to obtain the market supply curve.
Determinants of Supply
Price of related goods (substitutes and complements in production)
Cost of production
Technological advancement
Number of sellers
Shifts in the Supply Curve
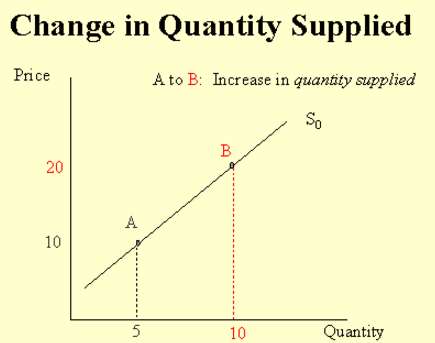
Change in quantity supplied: Movement along the supply curve due to a change in the product's price.
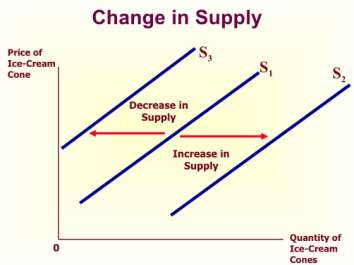
Change in supply: Shift of the supply curve due to changes in other factors (price remains constant). An increase in supply shifts the curve right; a decrease shifts it left.
Supply and Demand Together
Equilibrium
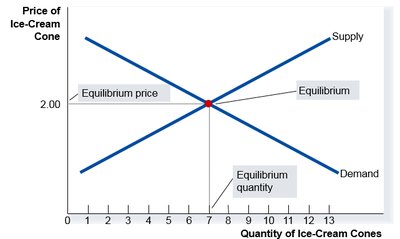
Equilibrium occurs when the price has reached a level where quantity supplied equals quantity demanded. The equilibrium price is where the supply and demand curves intersect, and the equilibrium quantity is the quantity at this price.
Surplus and Shortage
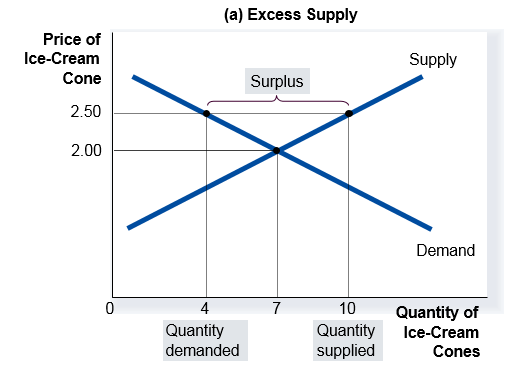
Surplus: When price is above equilibrium, quantity supplied exceeds quantity demanded, resulting in excess supply. Suppliers lower prices to restore equilibrium.
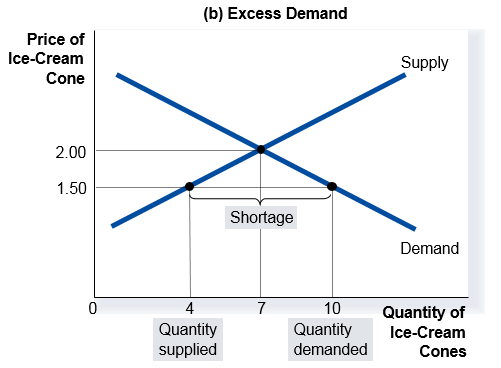
Shortage: When price is below equilibrium, quantity demanded exceeds quantity supplied, resulting in excess demand. Suppliers raise prices to restore equilibrium.
Three Steps for Analyzing Changes in Equilibrium
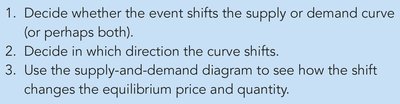
Decide whether the event shifts the supply or demand curve (or both).
Decide in which direction the curve shifts.
Use the supply-and-demand diagram to see how the shift changes the equilibrium price and quantity.
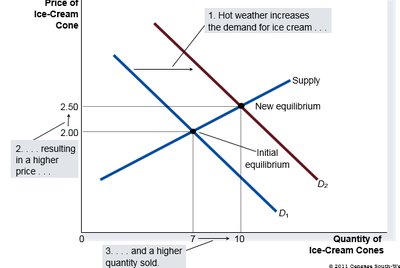
How an Increase in Demand Affects Equilibrium
An increase in demand shifts the demand curve to the right, resulting in a higher equilibrium price and quantity.
Shifts in Curves versus Movements along Curves
A shift in the supply curve is a change in supply.
A movement along a fixed supply curve is a change in quantity supplied.
A shift in the demand curve is a change in demand.
A movement along a fixed demand curve is a change in quantity demanded.
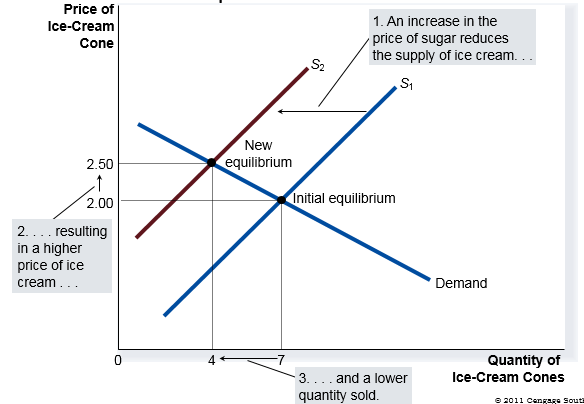
How a Decrease in Supply Affects Equilibrium
A decrease in supply shifts the supply curve to the left, resulting in a higher equilibrium price and a lower equilibrium quantity.
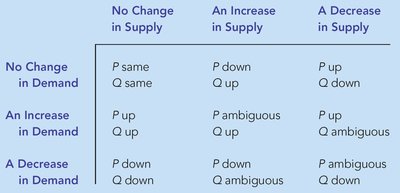
What Happens to Price and Quantity When Supply or Demand Shifts?
The following table summarizes the effects of changes in supply and demand on equilibrium price (P) and quantity (Q):
No Change in Supply | An Increase in Supply | A Decrease in Supply | |
|---|---|---|---|
No Change in Demand | P same Q same | P down Q up | P up Q down |
An Increase in Demand | P up Q up | P ambiguous Q up | P up Q ambiguous |
A Decrease in Demand | P down Q down | P down Q ambiguous | P ambiguous Q down |
Key Equations
Demand function: Where = quantity demanded, = price of the good, = price of related goods, = income, = tastes, = number of buyers, = expectations, = festive/climate factors.
Supply function: Where = quantity supplied, = price of the good, = price of related goods, = cost of production, = technology, = number of sellers.
Additional info: The above equations summarize the main determinants of demand and supply, which are essential for understanding market equilibrium and the effects of shifts in market conditions.
