 Indietro
Introduction to Microeconomics: Key Concepts and Graphical Analysis
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
What is Economics?
Definition of Economics
Economics is the study of how individuals and societies allocate scarce resources to satisfy unlimited wants. Because resources are limited, all economic questions arise from the problem of scarcity, which forces people to make choices.
Scarcity: The fundamental economic problem of having seemingly unlimited human wants in a world of limited resources.
Choices: Decisions made to allocate resources efficiently due to scarcity.
Example: Scarcity applies to all countries, regardless of their level of development.
Microeconomics vs. Macroeconomics
Economics is divided into two main branches:
Microeconomics: The study of choices made by individuals and businesses, and how these choices interact in markets.
Macroeconomics: The study of the economy as a whole, including issues like inflation, unemployment, and economic growth.
Examples of Microeconomic Topics:
Why a consumer buys less honey (microeconomic)
When the price of gas increases, consumers use less gas (microeconomic)
Two Big Economic Questions
What, How, and For Whom?
Economics seeks to answer two fundamental questions:
How do choices determine what, how, and for whom goods and services are produced?
When do choices made in self-interest also promote the social interest?
Factors of Production: Land, labor, capital, and entrepreneurship are the resources used to produce goods and services.
Land earns rent
Labor earns wages
Capital earns interest
Entrepreneurship earns profit
The Economic Way of Thinking
Opportunity Cost
The opportunity cost of an action is the highest-valued alternative that must be given up to take that action.
Example: The opportunity cost of attending university includes forgone income and other expenses.
Example: Choosing to go to the movies instead of studying results in a lower test score; the opportunity cost is the points forgone.
Marginal Analysis
Decisions are often made at the margin, weighing the additional (marginal) benefit against the additional (marginal) cost.
Marginal Benefit: The benefit from an incremental increase in an activity.
Marginal Cost: The opportunity cost of an incremental increase in an activity.
If marginal benefit exceeds marginal cost, it is rational to do more of the activity.
Positive vs. Normative Statements
Positive Statements: Statements that can be tested and validated; they describe "what is." Example: If the price of gasoline rises, people will drive less.
Normative Statements: Statements that express value judgments; they describe "what ought to be." Example: Greece is the best place to vacation.
Self-Interest and Social Interest
Economic decisions are often motivated by self-interest, but they can also promote the social interest.
Example: Starbucks expanding in China is in its self-interest, but it may also affect social interest by changing consumption patterns.
Example: Requiring nutrition labels is a decision made in the social interest.
Graphing in Economics
Economic Variables and Relationships
Economic models use variables such as price (P), quantity (Q), cost (C), labor (L), capital (K), and profit to describe relationships. These relationships can be expressed in words, symbols, equations, or graphs.
Types of Graphical Relationships
Variables move in the same direction (positive relationship)
Variables move in opposite directions (negative relationship)
Variables have a maximum or minimum
Variables are unrelated
The Slope of a Relationship
The slope measures the rate at which one variable changes with respect to another. For a straight line, the slope is constant and calculated as "rise over run." For a curve, the slope at a point is the slope of the tangent at that point.
Formula for Slope:
Example: If the slope is -2 at point A and -0.25 at point B, the relationship is changing along the curve.
Graphing Relationships Among More Than Two Variables
Economists often use graphs to represent relationships among multiple variables, helping to visualize and analyze economic models.
Mathematical Note: Linear Equations in Economics
Many economic relationships can be described by linear equations, such as:
Example: describes a straight-line relationship between variables x and y.
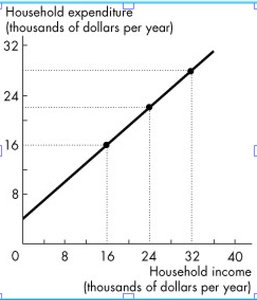
Example: Household Expenditure and Income
The following graph shows the relationship between household income and household expenditure. The slope of the line can be calculated as follows:
Formula:
Variable | Economic Meaning |
|---|---|
Land | Earns rent |
Labor | Earns wages |
Capital | Earns interest |
Entrepreneurship | Earns profit |
Additional info: Understanding the basics of graphing and interpreting economic data is essential for analyzing more advanced topics in microeconomics, such as supply and demand, elasticity, and market structures.
