 Indietro
Principles and Practice of Economics: Microeconomics Chapter 1 Study Guide
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Principles and Practice of Economics
Learning Objectives
Understand the scope of economics and its relevance to everyday choices.
Identify and explain the three fundamental principles of economics: optimization, equilibrium, and empiricism.
Apply economic reasoning to real-world scenarios and evaluate the costs and benefits of economic decisions.
The Scope of Economics
Definition and Focus
Economics is the study of how people make choices under conditions of scarcity and how those choices affect society. The central feature of economics is choice, not money, as individuals, firms, and governments must decide how to allocate limited resources to satisfy unlimited wants.
Scarcity: The situation where the quantity of resources available is insufficient to satisfy all wants.
Economic Agent: Any individual or group that makes choices, such as consumers, firms, parents, politicians, etc.
Microeconomics studies the behavior of individuals, firms, and governments in making choices, while macroeconomics examines the economy as a whole.
Key Ideas in Economics
Three Principles of Economics
Optimization: People try to choose the best available option given the information they have.
Equilibrium: Economic systems tend to reach a state where no individual can benefit by changing their own behavior.
Empiricism: Economists use data to test theories and understand real-world phenomena.
The First Principle: Optimization
Trade-offs and Budget Constraints
Optimization involves making the best possible choice, considering the trade-offs and constraints faced. Trade-offs occur when some benefits must be sacrificed to gain others. A budget constraint represents the set of options available without exceeding one's budget.
Opportunity Cost: The value of the next best alternative forgone when making a choice.
Economists often assign monetary values to opportunity costs to facilitate comparison.
Example: If you want to buy a $20 book but can get it for $10 by driving 3 miles, the opportunity cost of not driving is $10. Similarly, for a $1,000 computer available for $990 after driving, the opportunity cost is $10.
Opportunity cost formula:
Movie example: If you earn $10/hour and spend 2 hours watching a movie, the opportunity cost is $20.
The Second Principle: Equilibrium
Definition and Implications
Equilibrium is a situation where no individual can improve their outcome by changing their behavior. It is a central concept in economics, ensuring that resources are allocated efficiently.
Equilibrium occurs when everyone is optimizing.
Markets tend to move toward equilibrium, but not all situations are in equilibrium.
The Free Rider Problem arises when individuals benefit from resources or services without paying for them, leading to inefficiency and potential market failure.
To address free riders, groups must decide what is fair and apply pressure to conform.
Markets lack mechanisms for determining fairness.
The Third Principle: Empiricism
Evidence-Based Analysis
Empiricism involves using data to test economic theories and validate models. Economists rely on evidence to determine whether theoretical predictions match actual behavior.
Empirical analysis helps identify causality and evaluate the effectiveness of policies.
Example: Estimating the opportunity cost of time spent on social media platforms.
Calculation example: If U.S. adults spend 1 hour per day on social media and the opportunity cost of time is $13/hour, the annual cost is:
Positive vs. Normative Economics
Descriptive vs. Prescriptive Analysis
Positive Economics: Describes what people actually do (e.g., some people took more than one candy, not everyone got a piece).
Normative Economics: Recommends what people or society ought to do (e.g., each student should take one candy so everyone gets a piece).
Normative analysis is used to generate advice for public policy.
Is Economics Good for You?
Costs and Benefits of Studying Economics
Studying economics involves weighing the costs (tuition, other courses, sleep, stress) against the benefits (graduation, knowledge, higher earnings potential, learning to think like an economist).
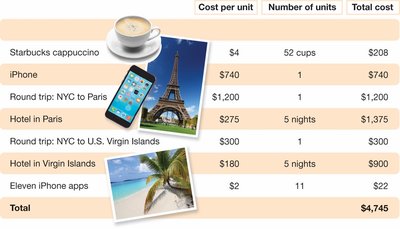
Summary Table: Opportunity Cost Example
This table illustrates what could be purchased with the opportunity cost of time spent on social media ($4,745/year).
Item | Cost per unit | Number of units | Total cost |
|---|---|---|---|
Starbucks cappuccino | $4 | 52 cups | $208 |
iPhone | $740 | 1 | $740 |
Round trip: NYC to Paris | $1,200 | 1 | $1,200 |
Hotel in Paris | $275 | 5 nights | $1,375 |
Round trip: NYC to U.S. Virgin Islands | $300 | 1 | $300 |
Hotel in Virgin Islands | $180 | 5 nights | $900 |
Eleven iPhone apps | $2 | 11 | $22 |
Total | $4,745 |
Conclusion
Economics provides a framework for understanding how individuals and societies make choices under scarcity. The principles of optimization, equilibrium, and empiricism are foundational to economic analysis and are essential for evaluating real-world decisions and policies.
