Indietro
The Ten Principles of Economics: Foundations of Microeconomics
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Introduction to Microeconomics
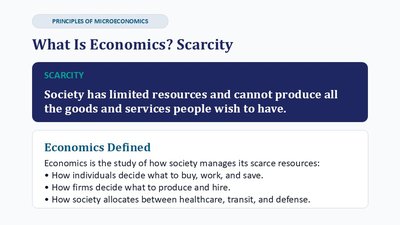
What Is Economics? Scarcity
Economics is the study of how society manages its scarce resources. Scarcity means that society has limited resources and cannot produce all the goods and services people wish to have. This fundamental problem leads to the need for choices and trade-offs.
Key Focus: How individuals decide what to buy, work, and save; how firms decide what to produce and hire; how society allocates resources among competing uses.
Introductory Economic Models
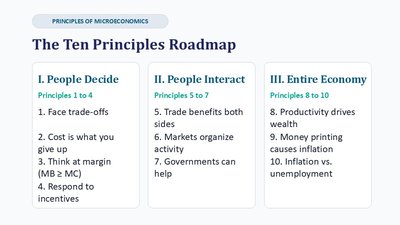
The Ten Principles Roadmap
The ten principles of economics provide a framework for understanding how people make decisions, how people interact, and how the economy as a whole works.
People Decide: Principles 1-4 (trade-offs, opportunity cost, marginal thinking, incentives)
People Interact: Principles 5-7 (trade, markets, government)
Entire Economy: Principles 8-10 (productivity, inflation, unemployment)
Principles of Microeconomics
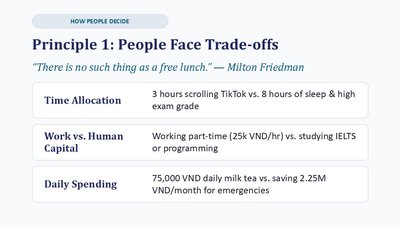
Principle 1: People Face Trade-offs
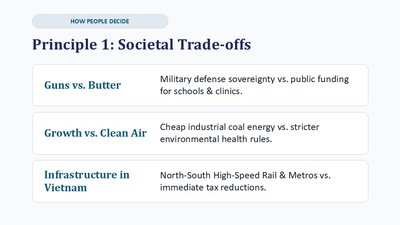
Every choice involves trade-offs because resources are limited. Choosing one thing means giving up something else. This applies to individuals (time, money) and societies (e.g., guns vs. butter).
Example: Choosing between extra sleep and breakfast, or between working part-time and studying.
Societal Trade-offs: Military vs. education funding, economic growth vs. environmental protection.
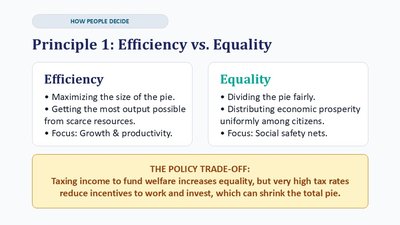
Principle 1: Efficiency vs. Equality
Efficiency means maximizing output from scarce resources, while equality means distributing economic prosperity fairly. Policies often involve a trade-off between these goals.
Efficiency: Focus on growth and productivity.
Equality: Focus on social safety nets and redistribution.
Policy Trade-off: High taxes may increase equality but reduce incentives for productivity.
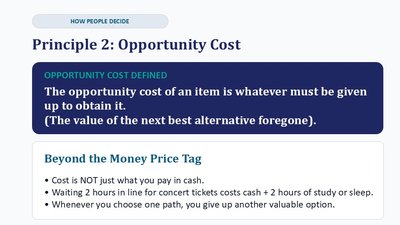
Principle 2: Opportunity Cost
The opportunity cost of an item is what you give up to get it—the value of the next best alternative foregone. This concept goes beyond just monetary cost and includes time, effort, and other resources.
Example: Waiting in line for tickets costs both money and time that could be spent elsewhere.
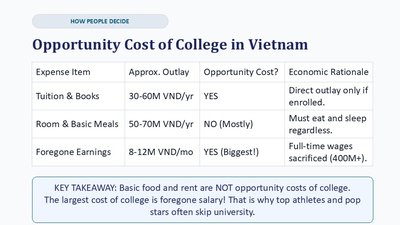
Opportunity Cost of College in Vietnam
Expense Item | Approx. Outlay | Opportunity Cost? | Economic Rationale |
|---|---|---|---|
Tuition & Books | 30-60M VND/yr | YES | Direct outlay only if enrolled |
Room & Basic Meals | 50-70M VND/yr | NO (Mostly) | Must eat and sleep regardless |
Foregone Earnings | 8-12M VND/mo | YES (Biggest!) | Full-time wages sacrificed |
Principle 3: Thinking at the Margin
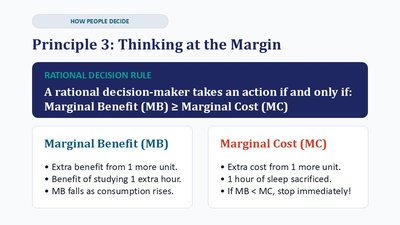
Rational decision-makers compare the additional (marginal) benefit to the additional (marginal) cost. An action is taken if and only if the marginal benefit is at least as great as the marginal cost.
Marginal Benefit (MB): Extra benefit from one more unit.
Marginal Cost (MC): Extra cost from one more unit.
Decision Rule:
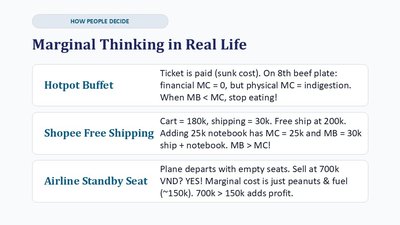
Marginal Thinking in Real Life
Hotpot Buffet: Stop eating when marginal benefit of more food is less than marginal cost (e.g., discomfort).
Shopee Free Shipping: Add items to reach free shipping if marginal benefit exceeds marginal cost.
Airline Standby Seat: Sell empty seats if marginal revenue exceeds marginal cost of fuel and peanuts.
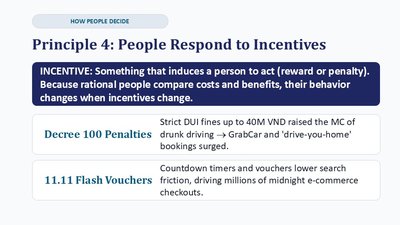
Principle 4: People Respond to Incentives
Incentives are rewards or penalties that motivate people to act. Rational people change their behavior when costs or benefits change.
Example: Higher fines for drunk driving reduce offenses; e-commerce vouchers increase purchases.
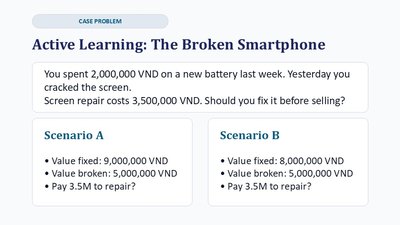
Case Study: Sunk Cost Fallacy
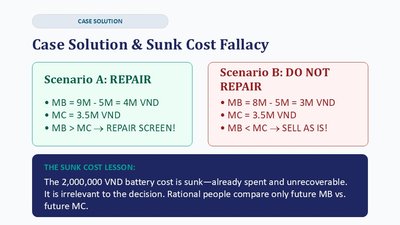
Rational decisions should ignore sunk costs—costs that have already been incurred and cannot be recovered. Only future costs and benefits should influence decisions.
Example: Deciding whether to repair a broken smartphone should depend on the marginal benefit and cost, not on past expenses.
How People Interact
Principle 5: Trade Benefits Both Sides
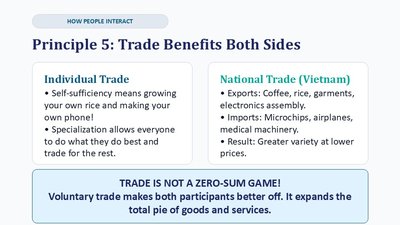
Trade allows individuals and nations to specialize in what they do best and to enjoy a greater variety of goods and services at lower cost. Voluntary trade makes all participants better off.
Individual Trade: Specialization and exchange increase efficiency.
National Trade: Exports and imports expand choices and lower prices.
Principle 6: Market Organization
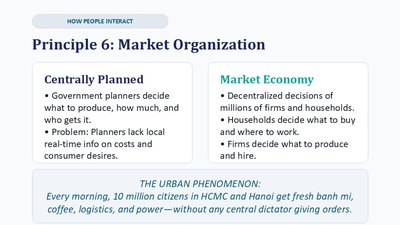
Markets are usually the best way to organize economic activity. In a market economy, decisions are decentralized and guided by prices, whereas in a centrally planned economy, government planners make decisions.
Market Economy: Millions of firms and households interact freely.
Centrally Planned: Planners often lack real-time information.
The "Invisible Hand" (Adam Smith, 1776)
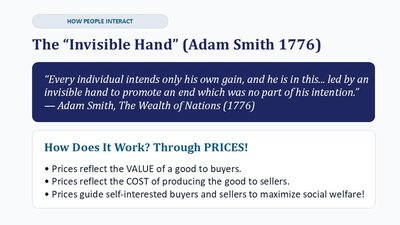
Adam Smith described how individuals pursuing their own self-interest unintentionally promote the overall good of society, as if guided by an "invisible hand." Prices play a central role in this process.
Prices reflect both the value to buyers and the cost to sellers.
Prices guide self-interested buyers and sellers to maximize social welfare.
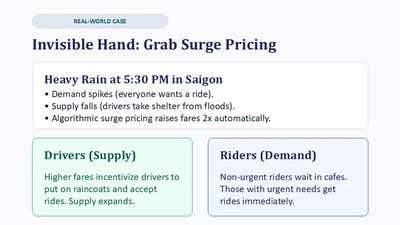
Real-World Case: Grab Surge Pricing
Algorithmic pricing adjusts fares based on supply and demand. For example, during heavy rain, demand for rides spikes and supply falls, so prices rise to balance the market.
Drivers (Supply): Higher fares incentivize more drivers to work.
Riders (Demand): Only those with urgent needs pay higher fares.
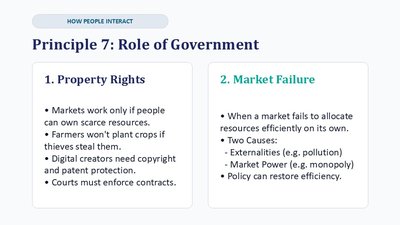
Principle 7: Role of Government
Governments can sometimes improve market outcomes by enforcing property rights and correcting market failures such as externalities and market power.
Property Rights: Essential for markets to function.
Market Failure: Occurs when markets fail to allocate resources efficiently.
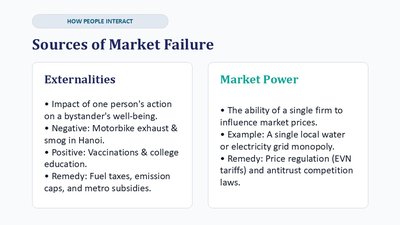
Sources of Market Failure
Externalities: Impact of one person's actions on others (e.g., pollution, vaccinations).
Market Power: Ability of a single firm to influence prices (e.g., monopoly).
Limits of Government Intervention
Markets reward productivity, not fairness. Government intervention can sometimes improve outcomes, but not always. Political pressures and imperfect information can lead to poor policies.
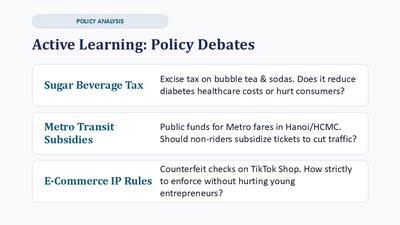
Policy Debates
Sugar Beverage Tax: Does it reduce healthcare costs or harm consumers?
Metro Transit Subsidies: Should non-riders subsidize public transit?
E-Commerce IP Rules: How to enforce without harming entrepreneurs?
The Whole Economy
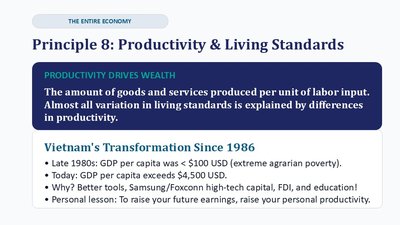
Principle 8: Productivity & Living Standards
Productivity—the amount of goods and services produced per unit of labor input—determines living standards. Differences in productivity explain most differences in income across countries and over time.
Example: Vietnam's rapid economic growth since 1986 due to better tools, capital, and education.
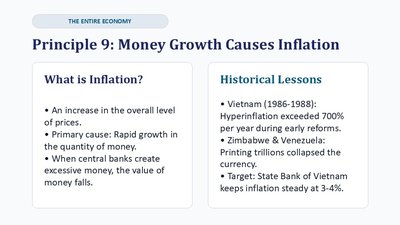
Principle 9: Money Growth Causes Inflation
Inflation is an increase in the overall level of prices. The primary cause is rapid growth in the quantity of money. When central banks create too much money, the value of money falls.
Historical Examples: Vietnam (1986-1988), Zimbabwe, Venezuela.
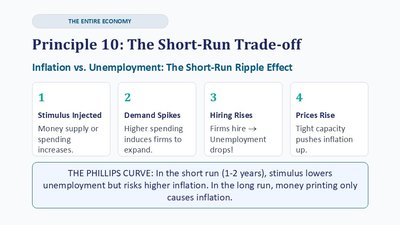
Principle 10: The Short-Run Trade-off between Inflation and Unemployment
In the short run, increasing the money supply or government spending can lower unemployment but may lead to higher inflation. This relationship is described by the Phillips Curve.
Short-Run Ripple Effect: Stimulus increases demand, hiring rises, but prices eventually rise.
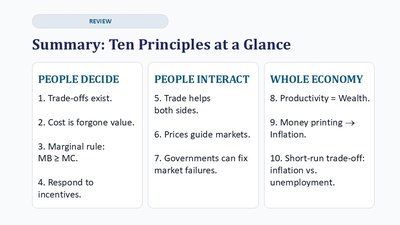
Summary: Ten Principles at a Glance
People Decide | People Interact | Whole Economy |
|---|---|---|
1. Trade-offs exist. 2. Cost is forgone value. 3. Marginal rule: MB ≥ MC. 4. Respond to incentives. | 5. Trade helps both sides. 6. Prices guide markets. 7. Governments can fix market failures. | 8. Productivity = Wealth. 9. Money printing → Inflation. 10. Short-run trade-off: inflation vs. unemployment. |