 Indietro
Chapter 1: Financial Statements – Foundations of Financial Accounting
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Introduction to Financial Accounting
Financial accounting is the process of measuring, processing, and communicating financial information about economic entities to interested parties. This chapter introduces the foundational concepts, principles, and statements that form the basis of financial accounting.
Why Accounting Is Critical to Business
The Role of Accounting
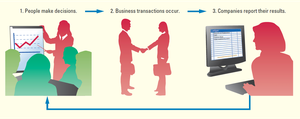
Accounting serves as an information system that:
Measures business activities
Processes data into financial statements and reports
Communicates results to decision makers
The accounting cycle is the process by which a company’s financial statements are prepared.
Users of Accounting Information
Individuals
Investors and creditors
Regulatory bodies
Nonprofit organizations
Types of Accounting
Financial Accounting: For external users (investors, creditors, government agencies, the public)
Managerial Accounting: For internal users (managers for budgeting, forecasting, projections)
Forms of Business Organization
Proprietorship
Single owner
Owner is personally liable for all business debts
Distinct entity for accounting purposes
Partnership
Two or more co-owners
Income and losses flow through to partners
General partnerships have unlimited liability; limited-liability partnerships limit liability to investment
Limited-Liability Company (LLC)
Business is liable for debts, not owners
Members have limited liability
Income flows through to members
Corporation
Owned by stockholders
Legally distinct from owners
Can raise large sums by issuing stock
Stockholders have limited liability
Subject to double taxation (corporation and shareholders taxed)
Accounting Concepts, Assumptions, and Principles
Professional Frameworks
Generally Accepted Accounting Principles (GAAP): Set by the Financial Accounting Standards Board (FASB)
International Financial Reporting Standards (IFRS): Set by the International Accounting Standards Board (IASB)
Conceptual Foundation of Accounting
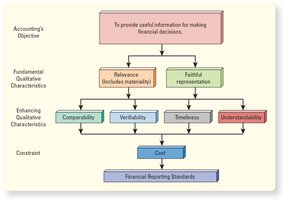
Relevance: Information must be useful and material to decision makers.
Faithful Representation: Information must be complete, neutral, and free from error.
Enhancing Qualitative Characteristics: Comparability, verifiability, timeliness, understandability.
Constraint: Cost-benefit consideration in reporting information.
Key Assumptions and Principles
Entity Assumption: Business is a separate economic unit.
Continuity (Going-Concern) Assumption: Entity will continue operating in the foreseeable future.
Historical Cost Principle: Assets are recorded at their actual cost.
Stable-Monetary-Unit Assumption: Dollar’s purchasing power is stable over time.
The Accounting Equation
Definition and Application
The accounting equation expresses the relationship among a company’s assets, liabilities, and equity:
Assets = Liabilities + Equity
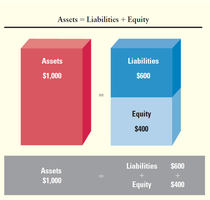
This equation must always balance. Assets are resources owned by the company; liabilities are obligations to outsiders; equity represents the owners’ claims.
Accounts
Assets: Cash, accounts receivable, inventories, property, plant, and equipment
Liabilities: Accounts payable, income taxes payable, long-term debt
Equity: Paid-in capital (common stock), retained earnings
Expanded Accounting Equation
For corporations:
Assets = Liabilities + (Common Stock + Retained Earnings)
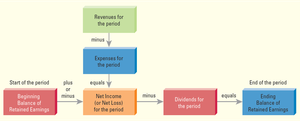
Components of Retained Earnings
Revenues: Inflows from delivering goods or services; increase retained earnings
Expenses: Outflows due to operations; decrease retained earnings
Dividends: Distributions to stockholders; decrease retained earnings (not an expense)
Gains: Increases from peripheral activities
Losses: Decreases from peripheral activities
Financial Statements and Their Relationships
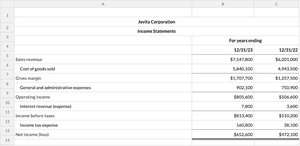
1. Income Statement
Reports revenues and expenses for a period, resulting in net income or loss.
Net Income (Loss) = Revenues - Expenses
2. Statement of Retained Earnings
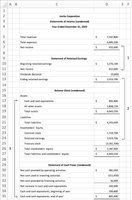
Shows changes in retained earnings over a period:
Beginning retained earnings
+ Net income (or - Net loss)
- Dividends
= Ending retained earnings
3. Balance Sheet
Reports assets, liabilities, and stockholders’ equity at a specific point in time.
Current assets: Used or converted to cash within one year
Long-term assets: Benefit the company beyond one year
Current liabilities: Due within one year
Long-term liabilities: Due after one year
Equity: Ownership interest in assets
4. Statement of Cash Flows
Reports cash receipts and payments, classified as:
Operating activities
Investing activities
Financing activities
Ethical Decision-Making in Accounting
Three Influences on Decisions
Economic: Maximize economic benefits
Legal: Follow laws and regulations
Ethical: Consider what is right, beyond legality and profitability
AICPA Code of Professional Conduct
Responsibilities
Public Interest
Integrity
Objectivity and Independence
Due Care
Scope and Nature of Services
Accounting and ESG (Environmental, Social, and Governance) Practices
ESG Reporting
Focuses on sustainability and social responsibility
Frameworks: GRI, ISSB, UNGC, TCFD
Measures: energy use, water use, emissions, waste, diversity
Accountants’ Role in ESG
Assure ESG reports
Analyze and recommend improvements in sustainability practices
Accounting Careers and Certifications
Career Paths
External auditor
Management accountant
Internal auditor
Budget analyst
Financial analyst
Professional Certifications
CPA (Certified Public Accountant)
CMA (Certified Management Accountant)
CGMA (Chartered Global Management Accountant)
CIA (Certified Internal Auditor)
CFE (Certified Fraud Examiner)
Tools and Technologies in Accounting
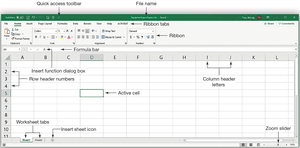
Spreadsheets
Organize data, perform calculations, generate graphs
Examples: Microsoft Excel, Google Sheets, Apple Numbers
Data Analytics
Transforms raw data into useful insights
Applications: trend analysis, process improvement, investment decisions
Artificial Intelligence and Machine Learning
AI: Programs that solve problems in a human-like way
Machine Learning: Machines learn from data without explicit programming
Robotic Process Automation (RPA)
Software bots perform routine tasks, freeing accountants for analysis
Technology Risks
Proper use facilitates better decisions
Improper use can lead to errors or catastrophic outcomes
Key Equations and Formulas
Accounting Equation: \text{Assets} = \text{Liabilities} + \text{Equity}\$
Net Income: \text{Net Income} = \text{Revenues} - \text{Expenses}\$
Ending Retained Earnings: \text{Ending Retained Earnings} = \text{Beginning Retained Earnings} + \text{Net Income} - \text{Dividends}\$
