 Indietro
Chapter 2: Transaction Analysis – Financial Accounting Study Notes
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Transaction Analysis in Financial Accounting
Recognizing Business Transactions and Types of Accounts
Business transactions are events with a financial impact on a company that can be measured reliably. Each transaction involves an exchange: something is given and something is received. Accounting records both sides of every transaction, ensuring objective information about the financial impact.
Transaction: Any event affecting the financial position of a business.
Account: A record of all changes in a particular asset, liability, or stockholders’ equity during a period.
Types of Accounts:
Assets: Economic resources providing future benefit (e.g., Cash, Accounts Receivable, Inventory, Prepaid Expenses, Investments, Property Plant & Equipment).
Liabilities: Debts or payables (e.g., Accounts Payable, Notes Payable, Accrued Liabilities).
Stockholders’ Equity: Owners’ claims to assets (e.g., Common Stock, Retained Earnings, Dividends, Revenues, Expenses).
Example: Selling goods to customers, purchasing supplies, or paying salaries are typical business transactions.
Accounting Equation
The fundamental relationship in accounting is expressed as:
Assets are resources, liabilities are external claims, and stockholders’ equity represents internal claims.
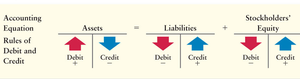
List and Differentiate Between Types of Accounts
Assets: Cash, Accounts Receivable, Notes Receivable, Inventory, Prepaid Expenses, Investments, Property Plant & Equipment.
Liabilities: Accounts Payable, Notes Payable, Accrued Liabilities.
Stockholders’ Equity: Common Stock, Retained Earnings, Dividends, Revenues, Expenses.
Example: Cash is an asset; Accounts Payable is a liability; Common Stock is stockholders’ equity.
Analyzing the Impact of Business Transactions on the Accounting Equation
Each transaction affects at least two accounts and changes the accounting equation. For example, investing cash increases assets and stockholders’ equity.
Key Steps:
Identify the nature of the activity.
Track the impact on specific accounts (increase or decrease).
Determine the amount involved.
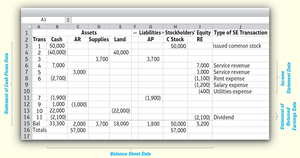
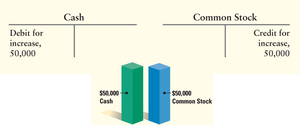
Example: Owners invest $50,000 cash and receive common stock. Cash (asset) increases; Common Stock (equity) increases.
Double-Entry System and Rules of Debit and Credit
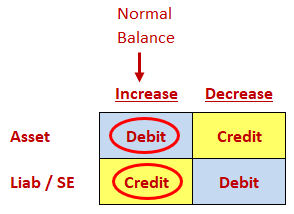
Accounting uses a double-entry system, recording dual effects of each transaction. Debits and credits indicate increases or decreases in account balances.
Debit: Left side of an account; increases assets and expenses.
Credit: Right side of an account; increases liabilities, stockholders’ equity, and revenues.
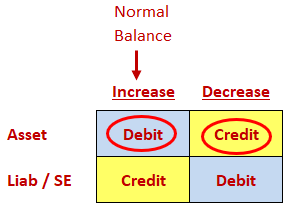
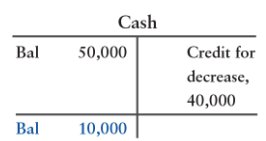
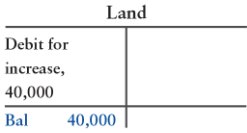
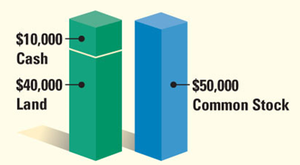
Example: Purchasing land for cash: Debit Land (asset increases), Credit Cash (asset decreases).
Expanded Accounting Equation
The expanded accounting equation includes income statement accounts:
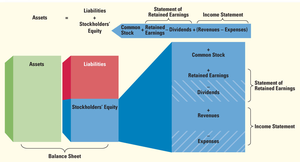
Journalizing Transactions and Posting to the Ledger
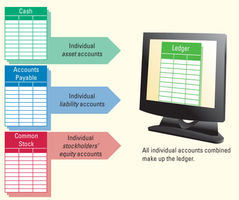
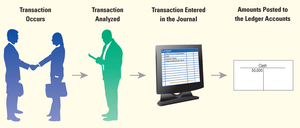
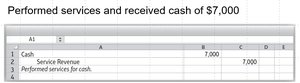
Transactions are first recorded in a journal as journal entries, then posted to the ledger. Each entry specifies the accounts affected, whether they are debited or credited, and the amount.
Journal: Chronological record of transactions.
Ledger: Collection of all accounts.
Posting: Transferring journal entries to the ledger accounts.
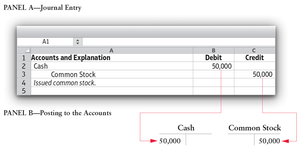
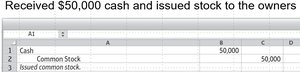
Example: Received $50,000 cash and issued stock: Debit Cash, Credit Common Stock.
Constructing a Trial Balance
A trial balance lists all accounts with their balances, showing that total debits equal total credits. It is usually prepared at the end of the period and facilitates the preparation of financial statements.
Assets listed first, followed by liabilities and stockholders’ equity.
Purpose: To check the accuracy of the accounting records.
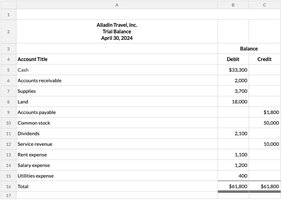
Chart of Accounts
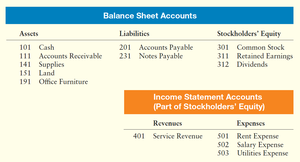
A chart of accounts is a list of all account titles and numbers used by a business. It organizes accounts for easy reference and reporting.
Machine Learning and Its Applications in Accounting and Business
Machine learning is a subset of artificial intelligence where machines learn from data without explicit programming. In accounting, machine learning can automate tasks such as identifying general ledger account names for transactions.
Supervised Learning: Task-driven, predicts values (e.g., spam filters).
Unsupervised Learning: Data-driven, identifies clusters (e.g., recommendation systems).
Programming Languages: Python (most popular), R, Julia, Java.
Example: Using machine learning to classify transactions for automated bookkeeping.
