 Indietro
The Valuation Principle and the Time Value of Money
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
The Valuation Principle in Financial Accounting
Cost-Benefit Analysis
The cost-benefit analysis is a fundamental tool for financial managers, guiding decisions to ensure that the benefits of an action exceed its costs. This principle is essential for maximizing the value of a firm.
Quantifying Costs and Benefits: All costs and benefits should be measured in equivalent terms, typically cash today, to allow for direct comparison.
Example: If a jewelry manufacturer trades 200 ounces of silver (worth $4,000) for 10 ounces of gold (worth $10,000), the net value is $6,000. Since the benefit exceeds the cost, the trade should be accepted.
Market Prices and the Valuation Principle
Competitive market prices are used to determine the value of goods and assets. The valuation principle states that the value of a commodity or asset is determined by its competitive market price, not by personal preferences or face values.
Law of One Price: In competitive markets, identical goods must have the same price.
Arbitrage: The practice of exploiting price differences for equivalent goods to earn risk-free profits.
Example: Choosing between concert tickets should be based on their market value, not personal preference or face value.
Applying the Valuation Principle
When evaluating opportunities, compare the total market value of the assets received to the cost incurred. If the net value is positive, the opportunity should be accepted.
Example: Acquiring 200 barrels of oil and 3,000 pounds of copper for $25,000, when their market values are $18,000 and $10,500 respectively, yields a net value of $3,500. The opportunity should be accepted.
The Time Value of Money and Interest Rates
The Time Value of Money
The time value of money reflects the principle that a dollar today is worth more than a dollar in the future due to its earning potential. This concept is central to financial decision-making.
Interest Rate (r): The rate at which money can be borrowed or lent over a period.
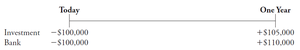
Opportunity Cost: The value forgone by investing in one option over another, such as depositing money in a bank versus investing in a project.
Present Value and Future Value
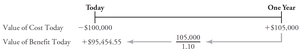
Present value (PV) is the value today of a future cash flow, discounted at the appropriate interest rate. Future value (FV) is the value of a cash flow at a future date, compounded at the interest rate.
Formula for Future Value:
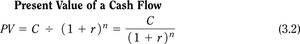
Formula for Present Value:
Example: Investing $100,000 today at 10% yields $110,000 in one year. The present value of $105,000 received in one year at 10% is $95,454.55.
Discount Factors and Discount Rates
The discount factor is the present value of $1 received in the future. The discount rate is the rate used to discount future cash flows to the present.
Formula for Discount Factor:
Valuing Cash Flows at Different Points in Time
Timelines
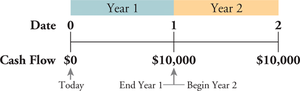
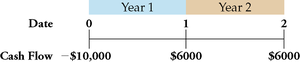
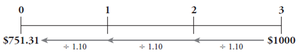
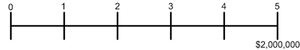
Timelines are visual tools used to represent the timing of cash flows, distinguishing between inflows and outflows and identifying the relevant dates for analysis.
Rules for Valuing Cash Flows
Rule 1: Comparing and Combining Values – Only compare or combine values at the same point in time.
Rule 2: Compounding – To calculate a cash flow’s future value, compound it using the interest rate.
Rule 3: Discounting – To calculate the value of a future cash flow at an earlier point in time, discount it using the interest rate.
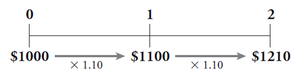
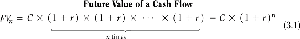
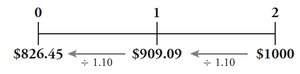
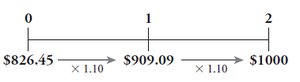
Examples of Present Value Calculations
Example 1: A savings bond pays PV = \frac{15,000}{(1 + 0.06)^{10}}$
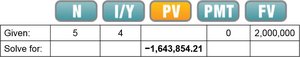
Example 2: XYZ Company expects PV = \frac{2,000,000}{(1 + 0.04)^5}$
Summary Table: Key Formulas
Concept | Formula (LaTeX) | Description |
|---|---|---|
Future Value | Value of a cash flow at a future date | |
Present Value | Value today of a future cash flow | |
Discount Factor | Present value of $1 received in the future |
Additional info: These principles are foundational for understanding how to value investments, compare alternatives, and make sound financial decisions in both accounting and finance contexts.
