 Indietro
The Valuation Principle and the Time Value of Money
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
The Valuation Principle in Financial Decision-Making
Cost-Benefit Analysis
Cost-benefit analysis is a fundamental tool in financial accounting and management, used to evaluate whether the benefits of a decision outweigh its costs. The role of the financial manager is to make decisions that increase the value of the firm by ensuring that the value of benefits exceeds the value of costs.
Quantifying Costs and Benefits: All costs and benefits should be measured in equivalent terms, typically cash today, to allow for accurate comparison.
Example: If a jewelry manufacturer trades 200 ounces of silver (at $20/ounce) for 10 ounces of gold (at $1,000/ounce), the net value is $10,000 - $4,000 = $6,000. Since the net value is positive, the trade should be accepted.
Market Prices and the Valuation Principle
Market prices in competitive markets provide an objective measure of value, independent of personal preferences. The valuation principle states that the value of an asset or commodity is determined by its competitive market price, and decisions should be evaluated using these prices.
Law of One Price: In competitive markets, identical goods must have the same price.
Arbitrage: The practice of exploiting price differences for equivalent goods to earn risk-free profits. Arbitrage opportunities are eliminated in efficient markets.
Example: Choosing between concert tickets based on their market value, not personal preference or face value, ensures the best financial outcome.
Applying the Valuation Principle
When evaluating opportunities, compare the total market value of what you receive to the cost you pay. If the value is positive, the opportunity should be accepted.
Example: Acquiring 200 barrels of oil (at $90/barrel) and 3,000 pounds of copper (at $3.50/pound) for $25,000 yields a net value of $18,000 + $10,500 - $25,000 = $3,500. The opportunity should be accepted.
The Time Value of Money and Interest Rates
Understanding the Time Value of Money
The time value of money is the concept that a dollar today is worth more than a dollar in the future due to its earning potential. This principle is central to financial accounting and investment decisions.
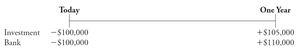
Interest Rate (r): The rate at which money can be borrowed or lent over a period.
Opportunity Cost: The value of the next best alternative forgone, such as the interest that could be earned by depositing money in a bank.
Present Value and Future Value
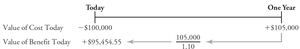
To compare cash flows at different points in time, we use present value (PV) and future value (FV) calculations. Present value discounts future cash flows to their value today, while future value compounds present cash flows to their value at a future date.
Present Value (PV): The value today of a future cash flow, discounted at the appropriate interest rate.
Future Value (FV): The value of a cash flow at a future date, compounded at the interest rate.
Discount Rate: The rate used to discount future cash flows to the present.
Discount Factor: The value today of $1 received in the future.
Timelines and Cash Flow Representation
Constructing Timelines
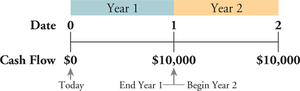
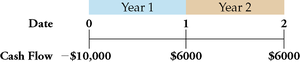
Timelines are visual tools used to represent the timing of cash flows, helping to clarify when costs and benefits occur. Each point on the timeline corresponds to a specific date, such as today (Date 0), the end of Year 1 (Date 1), etc.
Cash Inflows and Outflows: Positive values represent inflows, while negative values represent outflows.
Time Periods: Timelines can be adjusted for different periods (e.g., years, months).
Valuing Cash Flows at Different Points in Time
Rule 1: Comparing and Combining Values
Only cash flows at the same point in time can be directly compared or combined. To analyze cash flows occurring at different times, they must be converted to a common date using present or future value calculations.
Rule 2: Compounding
Compounding is the process of calculating the future value of a present cash flow by applying the interest rate over multiple periods. Compound interest is the interest earned on both the initial principal and the accumulated interest from previous periods.
Formula for Future Value:
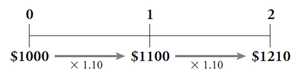
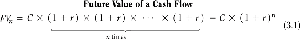
Rule 3: Discounting
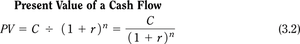
Discounting is the process of determining the present value of a future cash flow by applying the discount rate. This reflects the principle that money in the future is worth less than money today.
Formula for Present Value:
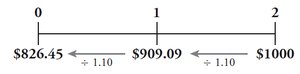
Examples of Present and Future Value Calculations
Example 1: Two-Year Investment
If $826.45 is invested today at 10% interest for two years, the future value will be $1,000. Conversely, the present value of $1,000 received in two years at a 10% discount rate is $826.45.
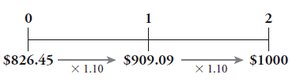
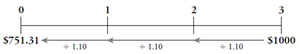
Example 2: Three-Year Investment
The present value of $1,000 received in three years at a 10% discount rate is $751.31.
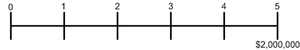
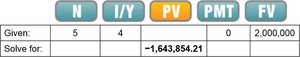
Example 3: Present Value of a Single Future Cash Flow
Suppose a company expects to receive $2,000,000 in five years. If the market interest rate is 4%, the present value can be calculated using the formula:
Summary Table: Key Formulas
Concept | Formula |
|---|---|
Future Value (FV) | |
Present Value (PV) |
Additional info: These principles are foundational for topics such as capital budgeting, investment analysis, and financial statement analysis in financial accounting.
