 Indietro
Microeconomics Review: Study Guidance and Practice
Guida di studio - Note intelligenti
 Appunti personalizzati basati sui tuoi materiali, ampliati con definizioni chiave, esempi e contesto.
Q1. Define the following terms: Scarcity, Land, Labor, Capital, Entrepreneurship.
Background
Topic: Factors of Production & Basic Economic Concepts
This question tests your understanding of the fundamental resources used in economics and the concept of scarcity, which is central to microeconomics.
Key Terms:
Scarcity: Limited nature of resources.
Land: Natural resources used in production.
Labor: Human effort used in production.
Capital: Tools, machinery, and buildings used to produce goods and services.
Entrepreneurship: The initiative to combine resources and create goods/services.
Step-by-Step Guidance
Start by identifying what each term means in the context of microeconomics.
Think about examples for each factor of production (e.g., land could be farmland, labor could be factory workers).
Consider how scarcity affects choices in an economy.
Write a brief definition for each term, focusing on its role in production.
Try solving on your own before revealing the answer!
Final Answer:
Scarcity: The condition where resources are limited and cannot satisfy all human wants.
Land: All natural resources used to produce goods and services.
Labor: The human effort, both physical and mental, used in production.
Capital: Manufactured goods used to produce other goods and services.
Entrepreneurship: The ability to organize land, labor, and capital to create new products or services.
These are the basic building blocks of economic activity.
Q2. What is human capital?
Background
Topic: Factors of Production
This question focuses on the concept of human capital, which is a key resource in microeconomics.
Key Term:
Human Capital: The skills, knowledge, and experience possessed by individuals.
Step-by-Step Guidance
Recall what distinguishes human capital from physical capital.
Think about how education and training contribute to human capital.
Consider examples of investments in human capital (e.g., schooling, job training).
Try solving on your own before revealing the answer!
Final Answer:
Human capital refers to the skills, knowledge, and experience that workers possess, which can be improved through education and training.
It increases productivity and is essential for economic growth.
Q3. What are the key qualities for each of the following economic systems: Command Economy and Market Economy?
Background
Topic: Economic Systems
This question tests your understanding of how different economies are organized and how resources are allocated.
Key Terms:
Command Economy: An economy where the government makes all decisions.
Market Economy: An economy where decisions are made by individuals and firms.
Step-by-Step Guidance
Identify who makes decisions in each system (government vs. individuals).
Think about how prices are determined (set by government or by supply and demand).
Consider examples of each system (e.g., North Korea for command, USA for market).
Try solving on your own before revealing the answer!
Final Answer:
Command Economy: Centralized decision-making, government ownership of resources, prices set by government.
Market Economy: Decentralized decision-making, private ownership, prices determined by supply and demand.
Each system has different strengths and weaknesses in resource allocation.
Q4. What are private property rights in a market economy?
Background
Topic: Market Economy & Property Rights
This question explores the importance of property rights in market economies.
Key Term:
Private Property Rights: The legal right to own and control resources.
Step-by-Step Guidance
Think about how property rights encourage investment and innovation.
Consider how property rights are protected in a market economy.
Reflect on the role of property rights in economic growth.
Try solving on your own before revealing the answer!
Final Answer:
Private property rights allow individuals to own, use, and transfer resources freely, which is essential for efficient resource allocation in a market economy.
They provide incentives for investment and innovation.
Q5. Explicit Cost vs. Implicit Cost vs. Opportunity Cost
Background
Topic: Costs in Economics
This question tests your understanding of different types of costs and how they relate to opportunity cost.
Key Terms:
Explicit Cost: Direct, out-of-pocket expenses.
Implicit Cost: Indirect, non-monetary opportunity costs.
Opportunity Cost: The value of the next best alternative foregone.
Step-by-Step Guidance
Identify examples of explicit costs (e.g., tuition, books).
Identify examples of implicit costs (e.g., lost wages from not working).
Understand how opportunity cost includes both explicit and implicit costs.
Think about how to calculate opportunity cost in a real-life scenario.
Try solving on your own before revealing the answer!
Final Answer:
Explicit Cost: Direct payments for goods/services (e.g., tuition).
Implicit Cost: The value of resources used without direct payment (e.g., foregone wages).
Opportunity Cost: The sum of explicit and implicit costs, representing the value of the next best alternative.
Opportunity cost is a key concept in decision-making.
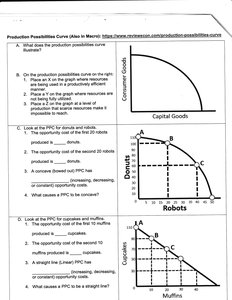
Q6. What does the production possibilities curve (PPC) illustrate?
Background
Topic: Production Possibilities Curve (PPC)
This question tests your understanding of the PPC, which shows the trade-offs between two goods.
Key Terms:
PPC: A graph showing the maximum possible output combinations of two goods.
Trade-off: Giving up one good to produce more of another.
Opportunity Cost: The cost of the next best alternative.
Step-by-Step Guidance
Examine the axes of the PPC (usually two goods).
Identify points on the curve and what they represent (efficient production).
Consider points inside and outside the curve (inefficiency vs. unattainable).
Think about how the curve illustrates opportunity cost and trade-offs.
Try solving on your own before revealing the answer!
Final Answer:
The PPC illustrates the maximum possible combinations of two goods that can be produced with available resources and technology. It shows trade-offs and opportunity costs.
Points on the curve are efficient, inside are inefficient, and outside are unattainable.
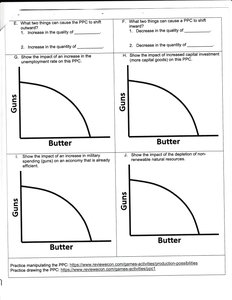
Q7. What two things can cause the PPC to shift outward?
Background
Topic: Economic Growth & PPC Shifts
This question tests your understanding of what causes an economy to grow and expand its production possibilities.
Key Terms:
Economic Growth: Increase in resources or technology.
PPC Shift: Outward movement of the curve.
Step-by-Step Guidance
Think about what increases an economy's capacity (e.g., more resources, better technology).
Consider examples like increased labor force or improved machinery.
Reflect on how these changes affect the PPC.
Try solving on your own before revealing the answer!
Final Answer:
Increase in the quantity or quality of resources (e.g., labor, capital).
Advances in technology.
Both lead to an outward shift of the PPC, representing economic growth.
Q8. What is comparative advantage and how is it calculated?
Background
Topic: Comparative Advantage
This question tests your understanding of how countries or individuals decide what to specialize in based on opportunity cost.
Key Terms & Formulas:
Comparative Advantage: The ability to produce a good at a lower opportunity cost than others.
Opportunity Cost Formula (Output):
Step-by-Step Guidance
Identify the output for each producer.
Calculate the opportunity cost for each good using the formula.
Compare opportunity costs to determine who has the comparative advantage.
Remember, lower opportunity cost means comparative advantage.
Try solving on your own before revealing the answer!
Final Answer:
Comparative advantage is calculated by comparing opportunity costs. The producer with the lower opportunity cost for a good has the comparative advantage in producing that good.
Use the formula to compare.
Q9. What is benefit maximizing behavior?
Background
Topic: Marginal Analysis
This question tests your understanding of how consumers make decisions to maximize their satisfaction.
Key Terms:
Benefit Maximizing Behavior: Choosing options that provide the greatest net benefit.
Marginal Analysis: Comparing additional benefits and costs.
Step-by-Step Guidance
Think about how consumers weigh marginal benefit against marginal cost.
Consider the decision rule: maximize net benefit where marginal benefit equals marginal cost.
Apply this concept to real-life choices (e.g., how many hours to study).
Try solving on your own before revealing the answer!
Final Answer:
Benefit maximizing behavior means making choices where the marginal benefit equals the marginal cost, maximizing overall satisfaction or utility.
This is a key principle in microeconomics.
