 뒤로
Comprehensive Study Notes for Principles of Macroeconomics
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Principles and Practice of Economics
What is Economics?
Economics is the study of how people choose to use resources. It encompasses both individual (microeconomics) and aggregate (macroeconomics) decision-making, focusing on how choices affect output, jobs, inflation, growth, and trade.
Resources include time, money, labor, capital, and natural resources.
Economics is broad, covering choices by individuals, firms, and governments.
Three Core Principles
Optimization: People and firms try to do the best they can given constraints.
Equilibrium: Markets tend to move toward a state where no agent has an incentive to change behavior.
Empiricism: Economists use data to test theories and inform policy.
Economic Science: Using Data and Models
The Scientific Method in Economics
Economists use models—simplified representations of reality—to generate predictions and test them with data.
Models are not exact but are useful for understanding and predicting economic phenomena.
Assumptions are necessary to simplify complex realities.
Causation vs. Correlation
Correlation: Two variables move together but one does not necessarily cause the other.
Causation: One variable directly affects another.
Omitted variables and reverse causality can lead to incorrect conclusions.
Optimization: Doing the Best You Can
Optimization in Levels and Differences
Levels: Choose the option with the highest net benefit (total benefit minus total cost).
Differences: Consider whether doing a little more yields greater marginal benefit than marginal cost.
Opportunity Cost
The value of the next best alternative forgone when making a choice.
Includes not just monetary costs but also time, effort, and foregone opportunities.
Demand, Supply, and Equilibrium
Markets and Market Price
A market is a collection of buyers and sellers for a good or service. The market price is where transactions occur.
Demand
Quantity Demanded: Amount buyers are willing to purchase at a given price.
Demand Curve: Plots quantity demanded at different prices, holding other factors constant.
Shifts in demand occur due to changes in tastes, income, prices of related goods, number of buyers, or expectations.
Supply
Quantity Supplied: Amount sellers are willing to sell at a given price.
Supply Curve: Plots quantity supplied at different prices, holding other factors constant.
Shifts in supply occur due to changes in input prices, technology, number of sellers, or expectations.
Market Equilibrium
Occurs where quantity supplied equals quantity demanded.
Competitive equilibrium price and quantity are determined by the intersection of supply and demand curves.
The Wealth of Nations: Measuring Macroeconomic Aggregates
Gross Domestic Product (GDP)
GDP: The market value of all final goods and services produced within a country in a given period.
Three approaches:
Production: Value of output minus value of intermediate goods.
Expenditure: Sum of consumption (C), investment (I), government spending (G), and net exports (X-M).
Income: Sum of all incomes earned in production (wages, profits, etc.).
What is Not in GDP?
Depreciation, home production, underground economy, negative externalities, leisure, and production by nationals abroad (GNP covers this).
Aggregate Incomes
Comparing Incomes Across Countries
GDP per capita is used to compare living standards.
Conversion methods:
Exchange-rate approach: Converts using current exchange rates (can be misleading due to price differences and fluctuations).
Purchasing Power Parity (PPP): Adjusts for differences in price levels using a representative basket of goods.
Productivity and the Aggregate Production Function
Productivity is output per worker or per hour worked.
Determinants: Human capital, physical capital, and technology.
Aggregate Production Function
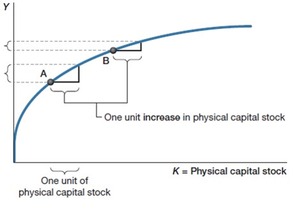
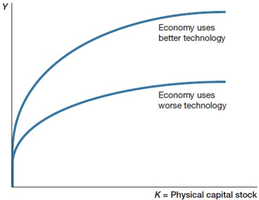
Describes how output (Y) depends on inputs of capital (K), labor (L), and technology (A):
Diminishing marginal product of capital: Each additional unit of capital increases output by less than the previous unit.
Better technology shifts the production function upward.
Economic Growth
Types of Growth
Catch-up growth: Poor countries grow rapidly by adopting existing technologies.
Sustained growth: Steady, long-term growth in advanced economies.
How Does Growth Happen?
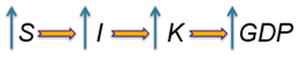
Growth results from increases in savings (S), investment (I), capital accumulation (K), and technological progress.
Sources of U.S. Economic Growth
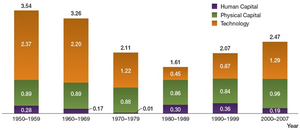
Technology has been the largest contributor to growth, followed by physical and human capital.
Growth, Inequality, and Poverty
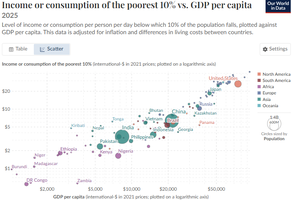
Growth reduces poverty and raises incomes, but may increase inequality.
GDP per capita is positively correlated with life expectancy, human development, and income of the poorest.
Employment and Unemployment
Defining and Measuring Employment & Unemployment
Potential workers: All people except children under 16, active military, and institutionalized persons.
Categories:
Employed: Paid job (full or part time).
Unemployed: No job, actively searching.
Not in labor force: No job, not searching.
Official and Alternative Unemployment Rates
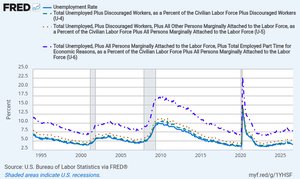
U-3: Official unemployment rate (actively seeking work).
U-4: U-3 plus discouraged workers.
U-5: U-4 plus other marginally attached workers.
U-6: U-5 plus part-time for economic reasons.
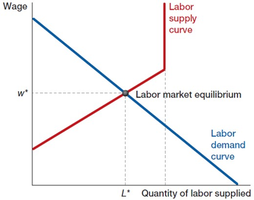
Labor Market Equilibrium
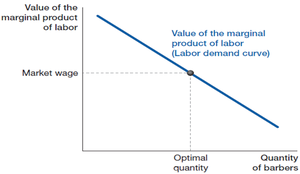
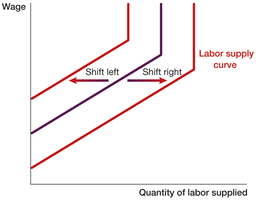
Equilibrium real wage and quantity of labor are determined by labor demand (firms) and labor supply (workers).
Types of Unemployment
Frictional: Due to time needed to match workers with jobs.
Structural: Due to persistent mismatch between skills and jobs, or wage rigidity.
Wage rigidity: Wages held above equilibrium by minimum wage laws, unions, efficiency wages, or worker aversion to wage cuts.
Measuring GDP and Inflation
National Income Accounts
GDP can be measured by production, expenditure, or income approaches.
Expenditure approach:
Nominal vs. Real GDP
Nominal GDP: Value of production at current prices.
Real GDP: Value of production at constant base-year prices.
GDP Deflator:
Inflation Measures
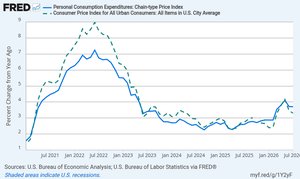
Consumer Price Index (CPI): Measures prices paid by urban consumers for a fixed basket of goods.
Personal Consumption Expenditures (PCE) Price Index: Measures prices of goods and services purchased by or for consumers, allows for substitution.
GDP Deflator: Measures prices of all domestically produced final goods and services.
Producer Price Index (PPI): Measures prices received by domestic producers.
Inflation Rate Formula
CPI vs. PCE
CPI uses a fixed basket; PCE allows for consumer substitution, often showing lower inflation.
Appendix: Key Tables
Summary Table: Types of Unemployment
Type | Description | Main Causes |
|---|---|---|
Frictional | Short-term, due to job search | Imperfect information, time to match |
Structural | Long-term, persistent mismatch | Skill mismatch, wage rigidity |
Cyclical | Due to economic downturns | Insufficient demand |
Summary Table: Inflation Measures
Index | Produced by | What it Measures |
|---|---|---|
CPI | BLS | Prices paid by urban consumers |
PCE | BEA | Prices of goods/services purchased by/for consumers |
GDP Deflator | BEA | Prices of all domestically produced final output |
PPI | BLS | Prices received by domestic producers |
