 뒤로
Foundations and Models in Macroeconomics: Chapter 1 Study Guide
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Economics: Foundations and Models
Three Key Economic Ideas
Economics is built upon three fundamental concepts that guide decision-making and analysis:
People Are Rational: Individuals and firms use all available information to achieve their goals, weighing costs and benefits to make optimal decisions. For example, a company like Apple sets prices to maximize profit, not randomly.
People Respond to Economic Incentives: Changes in incentives alter behavior. For instance, policies requiring DNA samples from felons reduced repeat convictions, demonstrating that even criminals respond to incentives.
Optimal Decisions Are Made at the Margin: Most choices involve incremental changes. Marginal analysis compares the additional benefit (marginal benefit) and additional cost (marginal cost) of an action. Decisions are made when marginal benefit equals marginal cost.
Example: Deciding whether to study for an extra hour or watch TV involves comparing the marginal benefit of improved grades to the marginal cost of lost leisure time.
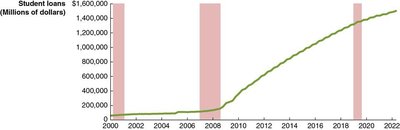
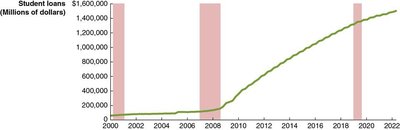
The Economic Problem That Every Society Must Solve
Scarcity means limited resources must be allocated efficiently. Every society must answer:
What goods and services will be produced? Trade-offs are necessary; producing more of one good means less of another. The opportunity cost is the value of the next best alternative forgone.
How will goods and services be produced? Firms choose production methods based on costs and available technology, sometimes substituting labor for capital or relocating to reduce expenses.
Who will receive the goods and services produced? Distribution is often based on income, but government policies can redistribute resources for equity.
Example: Increased funding for space exploration may require reducing funding for cancer research.
Centrally Planned, Market, and Mixed Economies
Economic systems differ in how resources are allocated:
Centrally Planned Economy: The government decides allocation.
Market Economy: Households and firms interact in markets to allocate resources.
Mixed Economy: Most decisions are made in markets, but government plays a significant role (e.g., Social Security, minimum wage).
The U.S. is best described as a mixed economy.
Efficiency and Equity in Market Economies
Market economies promote:
Productive Efficiency: Goods and services are produced at the lowest possible cost.
Allocative Efficiency: Production matches consumer preferences; goods are produced up to the point where marginal benefit equals marginal cost.
Voluntary exchange ensures both buyers and sellers benefit, improving overall well-being.
However, markets may not always be fully efficient due to government intervention, slow adaptation, or externalities (e.g., pollution).
Equity refers to the fair distribution of economic benefits. Governments often face trade-offs between efficiency and equity.
Economic Models
How Economists Use Models
Economic models are simplified representations of reality used to analyze events and policies. The process involves:
Deciding on assumptions
Formulating a testable hypothesis
Using data to test the hypothesis
Revising the model if necessary
Retaining the revised model for future analysis
Models rely on behavioral assumptions, such as consumers maximizing well-being and firms maximizing profit.
Positive vs. Normative Analysis
Positive Analysis: Concerned with what is; objective and fact-based.
Normative Analysis: Concerned with what ought to be; involves value judgments.
Economists primarily use positive analysis, but policy decisions often require normative considerations.
Economics as a Social Science
Economics studies individual actions and their effects on outcomes like prices, employment, and growth. It is a social science, emphasizing the impact of choices and policies on society.
Applications of Economics in Careers
Economists use their skills in various fields, including forecasting demand, analyzing costs and benefits, reporting on monetary policy, and evaluating development programs.
Company/Organization | Economist's Role |
|---|---|
Ford Motor Company | Forecast demand for electric cars |
Goldman Sachs | Forecast interest rates |
McDonald's | Evaluate expansion decisions |
Pfizer | Analyze costs and benefits of treatments |
Wall Street Journal | Interpret monetary policy |
Federal Reserve Bank | Forecast employment trends |
Federal Trade Commission | Analyze mergers |
World Bank | Evaluate development programs |
Does Majoring in Economics Increase Income?
Economics majors tend to have higher median wages, but causation is not guaranteed; self-selection may play a role.
Major | Median Wage (Early Career) | Median Wage (Midcareer) |
|---|---|---|
Economics | $60,000 | $91,000 |
All Majors | $45,000 | $72,000 |
Preview of Important Economic Terms
Scarcity: Unlimited wants exceed limited resources.
Opportunity Cost: The value of the next best alternative forgone.
Technology: Processes used to produce goods and services.
Capital: Manufactured goods used to produce other goods and services.
Appendix: Using Graphs and Formulas
Graphs in Economics
Graphs are essential tools for visualizing economic relationships. Common types include bar graphs, pie charts, and time-series graphs.
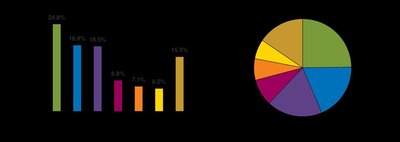
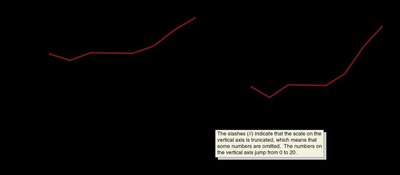
Plotting Price and Quantity
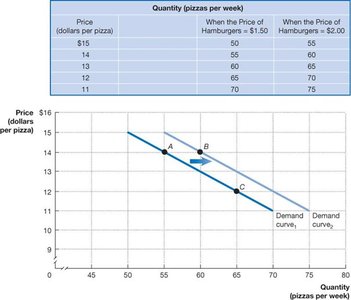
Graphs can illustrate the relationship between price and quantity, such as the demand curve for pizza.
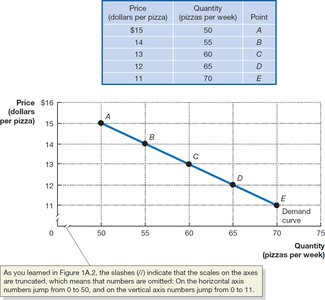
Calculating Slope
The slope of a line is calculated as the change in the y-axis variable divided by the change in the x-axis variable:
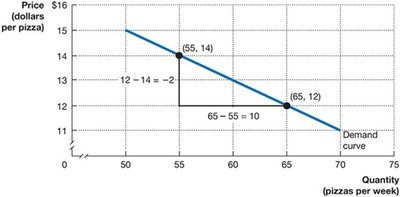
Example: If the price of pizza decreases from \frac{-2}{10} = -0.2$.
Showing Three Variables on a Graph
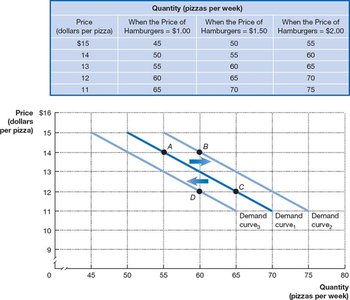
Graphs can hold other variables constant or show shifts due to changes in related goods (e.g., price of hamburgers affecting pizza demand).
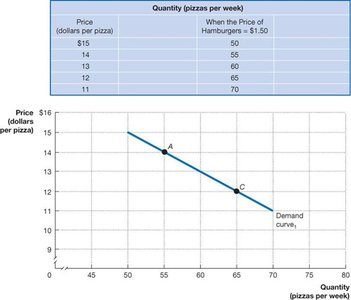
Positive and Negative Relationships
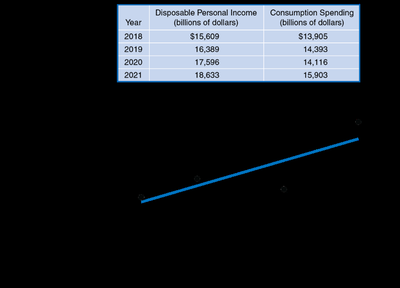
A positive relationship means both variables increase together; a negative relationship means one increases as the other decreases.
Cause and Effect in Graphs
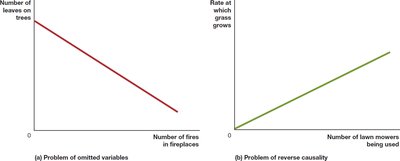
Graphs can illustrate relationships but do not always prove causality. Problems include omitted variables and reverse causality.
Linear and Nonlinear Relationships
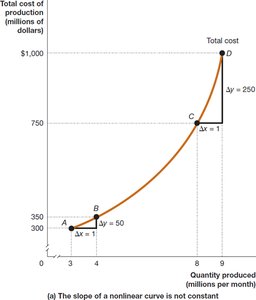
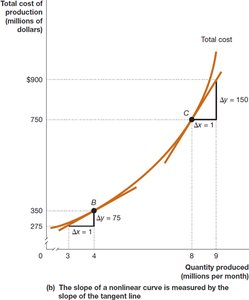
Most economic relationships are not perfectly linear. Nonlinear curves have varying slopes, which can be measured using tangent lines.
Percentage Change Formula
The percentage change in an economic variable is calculated as:
Example: U.S. real GDP increased from $19,610 billion in 2021 to $20,018 billion in 2022, a 2.1% increase.
Calculating Areas in Economic Graphs
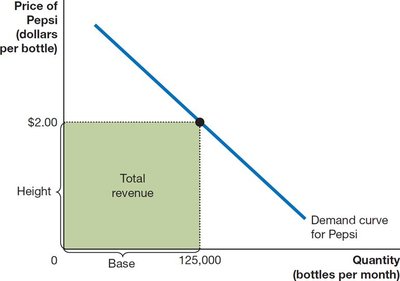
The area of a rectangle (e.g., total revenue) is base times height:
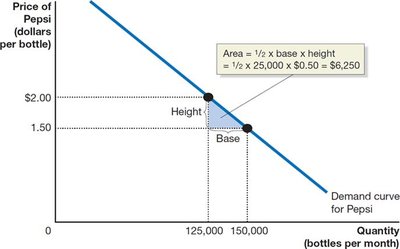
The area of a triangle (e.g., consumer surplus) is:
Summary of Using Formulas
Understand the economic concept represented by the formula.
Use the correct formula for the problem.
Check that the calculated value is economically reasonable.
Microeconomics vs. Macroeconomics
Definitions and Examples
Microeconomics studies individual households and firms, their choices, and market interactions. Macroeconomics examines the economy as a whole, including inflation, unemployment, and growth.
Microeconomic Issues | Macroeconomic Issues |
|---|---|
Consumer reactions to price changes | Causes of recessions and unemployment |
Firm pricing decisions | Long-run economic growth |
Government policies to reduce addiction | Inflation rate determinants |
AI effects on production and employment | Value of currency exchange rates |
Efficient ways to reduce pollution | Government intervention in recessions |
Example: Analyzing the effect of tariffs involves both microeconomic (firm-level) and macroeconomic (national-level) perspectives.
