 뒤로
Ten Big Ideas in Economics: Foundations and Principles
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Ten Big Ideas in Economics
What Economics Is All About
Economics is the study of how society manages its scarce resources. Scarcity refers to the limited nature of society’s resources, which forces individuals, firms, and governments to make choices about allocation. These choices include decisions about what to buy, how much to work, save, and spend, how firms decide production and employment, and how countries allocate resources among competing needs.
Scarcity: The fundamental economic problem of having limited resources to meet unlimited wants.
Economics: The science of decision-making under scarcity.
Resource Allocation: The process of distributing scarce resources among competing uses.
Examples: Choosing between national defense, consumer goods, and environmental protection.
The Principles of How People Make Decisions
Big Idea #1: Tradeoffs are Everywhere
Every decision involves tradeoffs. Choosing one option means giving up another. This applies to individuals, firms, and societies. For example, spending more time tailgating before a football game leaves less time for other activities, and working longer hours increases income but reduces leisure time.
Tradeoff: The act of giving up one benefit to gain another.
Efficiency vs. Equality: Efficiency means maximizing output from scarce resources, while equality means distributing prosperity uniformly. Government programs often illustrate this tradeoff.
Big Idea #2: The Cost of Something Is What You Give Up to Get It
Decision-making requires comparing costs and benefits. The opportunity cost of an item is what must be given up to obtain it. For example, the cost of attending college includes tuition, books, and foregone earnings from not working.
Opportunity Cost: The value of the next best alternative foregone.
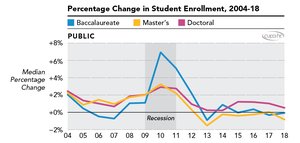
Example: College enrollment often increases during recessions as opportunity costs (foregone wages) decrease.
Big Idea #3: Rational People Think at the Margin
Rational individuals make decisions by evaluating marginal changes—small, incremental adjustments to an existing plan. They weigh the additional benefits and costs of their actions. For example, the decision to repair a car depends on the marginal cost and benefit, not on past expenditures.
Marginal Analysis: Comparing the additional benefits and costs of a decision.
Example: Mandatory executions for speeding would drastically change incentives and behavior.
Big Idea #4: Incentives Matter
Incentives are rewards or punishments that influence behavior. Rational people respond to incentives, and policymakers must consider how laws and regulations affect incentives to avoid unintended consequences.
Incentive: Something that motivates a person to act.
Example: Historical transportation of British felons to Australia changed incentives and outcomes.
Active Learning: Applying the Principles
When deciding whether to repair a car, only the marginal cost and benefit matter. Sunk costs, such as previous repairs, are irrelevant. Changes in incentives can alter decisions.
Sunk Cost: A cost that has already been incurred and cannot be recovered.
Marginal Decision: Repair if the increase in value exceeds the cost.
The Principles of How People Interact
Big Idea #5: Trade Can Make Everyone Better Off
Trade allows people and countries to specialize in what they do best and exchange goods and services, leading to greater overall prosperity. Specialization and exchange enable participants to obtain goods at lower opportunity costs.
Specialization: Focusing on the production of a particular good or service.
Exchange: Trading goods and services to mutual benefit.
Big Idea #6: Markets Are Usually a Good Way to Organize Economic Activity
Markets are groups of buyers and sellers who interact to determine prices and allocate resources. In a market economy, decentralized decisions by households and firms guide resource allocation, often leading to efficient outcomes. Adam Smith described this process as being led by an "invisible hand."
Market: A system where buyers and sellers interact.
Invisible Hand: The self-regulating nature of markets.
Price System: Prices reflect value and cost, guiding decisions.
Big Idea #7: Governments Can Sometimes Improve Market Outcomes
Markets sometimes fail to allocate resources efficiently, a situation known as market failure. Causes include externalities (effects on bystanders) and market power (influence over prices). Government intervention can promote efficiency and equity.
Market Failure: Inefficient allocation of resources by the market.
Externality: Impact of one’s actions on others (e.g., pollution).
Market Power: Ability to influence prices (e.g., monopoly).
The Principles of How the Economy as a Whole Works
Big Idea #8: Productivity is the Key to Economic Prosperity
Productivity, the amount of goods and services produced per unit of labor, is the most important determinant of living standards. Differences in productivity explain variations in income across countries and over time. Productivity depends on equipment, skills, education, and technology.
Productivity: Output per unit of labor.
Determinants: Equipment, skills, education, technology.
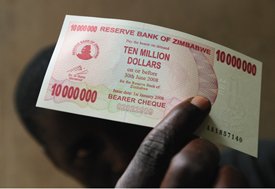
Big Idea #9: Prices Rise When the Government Prints Too Much Money
Inflation is an increase in the general level of prices. In the long run, inflation is caused by excessive growth in the money supply, which reduces the value of money. The faster the government creates money, the higher the inflation rate.
Inflation: Sustained increase in prices.
Money Supply: Total amount of money in circulation.
Equation: (Money supply × Velocity = Price level × Quantity of output)
Big Idea #10: Booms and Busts Cannot be Avoided but Can be Moderated
Economies experience irregular fluctuations known as the business cycle, which includes periods of expansion (booms) and contraction (busts). Monetary and fiscal policy are tools used by policymakers to moderate these fluctuations and stabilize the economy.
Business Cycle: Fluctuations in economic activity, employment, and production.
Monetary Policy: Central bank actions affecting money supply and interest rates.
Fiscal Policy: Government spending and taxation decisions.
