 뒤로
Chapter 1: What Is Economics? — Microeconomics Foundations
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
What Is Economics?
Definition and Scope of Economics
Economics is the social science that studies how individuals, businesses, governments, and societies make choices to cope with scarcity and the incentives that influence and reconcile those choices. Scarcity arises because our wants exceed the resources available, requiring us to make choices. These choices are shaped by incentives, which are rewards or penalties that influence behavior.
Scarcity: The fundamental economic problem of having limited resources to meet unlimited wants.
Incentives: Rewards or penalties that motivate choices.
Microeconomics: The study of individual and business choices, market interactions, and government influence.
Macroeconomics: The study of national and global economic performance.
Example: A microeconomic question: Why are people buying more e-books and fewer hard copy books?
The Two Big Economic Questions
Economics addresses two central questions:
1. How do choices determine what, how, and for whom goods and services are produced?
2. When do choices made in self-interest also promote the social interest?
What, How, and For Whom?
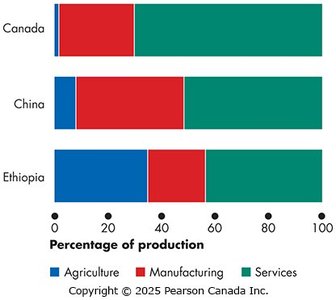
Goods and services are produced to satisfy human wants. The composition of production varies by country, as illustrated below:
What? The mix of agriculture, manufacturing, and services differs across nations.
How? Goods and services are produced using factors of production: land, labour, capital, and entrepreneurship.
For Whom? Distribution depends on incomes earned from factors of production: rent (land), wages (labour), interest (capital), and profit (entrepreneurship).
Factors of Production
Land: Natural resources used in production.
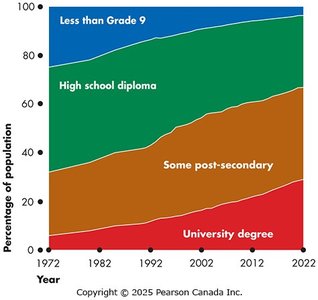
Labour: Human effort, influenced by human capital (education, training, experience).
Capital: Tools, machines, buildings used in production.
Entrepreneurship: The human resource that organizes the other factors.
Self-Interest vs. Social Interest
Choices made in self-interest may or may not align with the social interest. Social interest is defined by efficiency (maximizing benefits without making others worse off) and equity (fairness).
Efficiency: Resource use is efficient if it is impossible to make someone better off without making someone else worse off.
Equity: Fairness in the distribution of resources and outcomes.
Key issues illustrating the tension between self-interest and social interest include globalization, information-age monopolies, climate change, and the gender pay gap.
The Economic Way of Thinking
Six Key Ideas
The economic way of thinking is defined by six core concepts:
A choice is a tradeoff: Every decision involves giving up one thing to get another.
Rational choices: People compare benefits and costs to maximize their benefit over cost.
Benefit: The gain or pleasure from an action, determined by preferences.
Cost: The opportunity cost, or the highest-valued alternative forgone.
Marginal analysis: Most choices are "how-much" decisions made at the margin, comparing incremental benefits and costs.
Incentives: Choices respond to changes in incentives.
Opportunity Cost
The opportunity cost of an action is the value of the next best alternative forgone. It includes both monetary and time costs.
Formula:
Marginal Benefit and Marginal Cost
Marginal Benefit: The additional benefit from an incremental increase in an activity.
Marginal Cost: The additional cost from an incremental increase in an activity.
Rational Decision Rule: Increase activity if marginal benefit exceeds marginal cost.
Formula:
Economics as a Social Science and Policy Tool
Positive vs. Normative Statements
Positive statements: Describe what is; can be tested against facts.
Normative statements: Describe what ought to be; express opinions and cannot be tested.
Economic Models and Methods
Economists use models to describe aspects of the economic world, focusing on relevant features. Models are tested by comparing predictions with facts, using natural experiments, statistical investigations, and economic experiments.
Economist as Policy Adviser
Economics provides a toolkit for evaluating policy alternatives by comparing marginal benefits and marginal costs, though it cannot determine normative goals.
Economists in the Economy
Jobs and Skills for Economics Majors
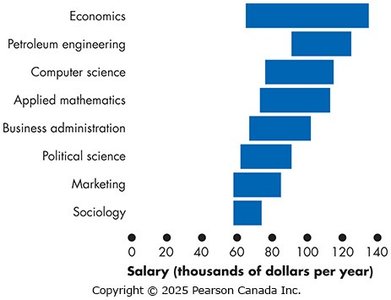
Economics graduates pursue careers as economists, market research analysts, financial analysts, and budget analysts. Employment is found in private firms, government, and international organizations.
Key skills: Critical-thinking, analytical, math, writing, and oral communication.
Diversity, Equity, and Inclusion in Economics
Economics faces challenges in diversity and representation. In Canada, women are underrepresented in economics degrees compared to their population share. Efforts to improve diversity are ongoing, as a more inclusive profession enhances fairness and efficiency.
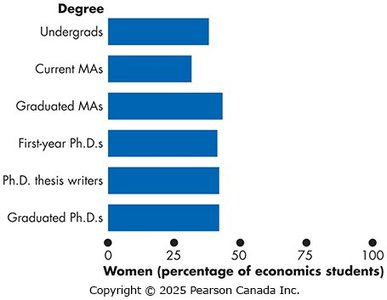
Degree | Women (% of economics students) |
|---|---|
Undergrads | ~42% |
Current MAs | ~42% |
Graduated MAs | ~42% |
First-year Ph.D.s | ~42% |
Ph.D. thesis writers | ~42% |
Graduated Ph.D.s | ~42% |
Additional info: Diversity and inclusion are essential for attracting the best talent and improving economic research and policy outcomes.
