 뒤로
Competitive Markets and Perfect Competition: Study Notes
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Competitive Markets
Market Structure and Firm Behaviour
Market structure encompasses all features of a market that affect the behaviour and performance of firms, including the number and size of sellers, knowledge of competitors' actions, freedom of entry, and product differentiation. Market power refers to a firm's ability to influence the price of its product. In a competitive market, firms have little or no market power, and the extreme case is a perfectly competitive market where each firm has zero market power.
Competitive behaviour is the degree to which firms actively compete for business.
Example: MasterCard and Visa compete, but their market is not competitive; wheat farmers do not compete actively, but their market is highly competitive.
The Theory of Perfect Competition
Assumptions of Perfect Competition
Perfect competition is based on four key assumptions:
All firms sell a homogeneous product.
Customers are fully informed about products and prices.
The minimum efficient scale of each firm is small relative to total industry output.
There is freedom of entry and exit in the industry.
Demand Curves in Perfect Competition
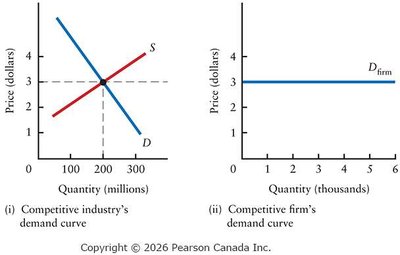
In a competitive industry, the market demand curve is downward sloping, while an individual firm's demand curve is perfectly elastic (horizontal) at the market price. This means the firm can sell any quantity at the prevailing price, but cannot influence the price by its own output decisions.
Firms are price takers and face horizontal demand curves.
Total, Average, and Marginal Revenue
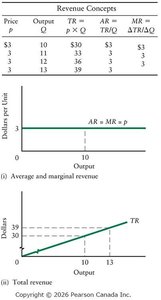
Revenue concepts are central to understanding firm behaviour in competitive markets:
Total Revenue (TR):
Average Revenue (AR):
Marginal Revenue (MR):
For a price-taking firm,
Short-Run Decisions
Profit Maximization and Losses
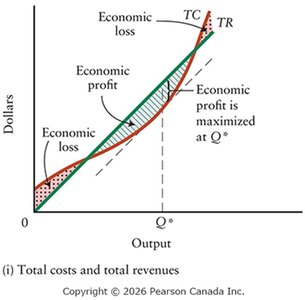
A firm's objective is to maximize profits, defined as:
If , the firm makes economic losses ().
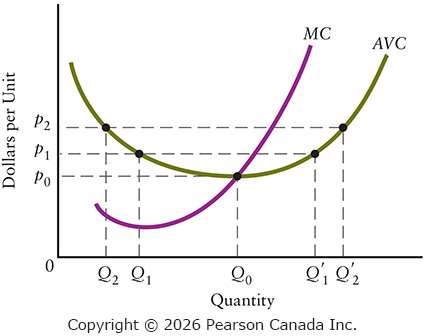
If a firm produces nothing, its loss equals total fixed costs (). If it produces, it must cover variable costs (). The firm should produce if or equivalently .
If , the firm should shut down.
The shut-down price is where .
Output Decision: How Much to Produce?
If producing is profitable, the firm should produce the quantity where marginal revenue equals marginal cost:
For a competitive firm,
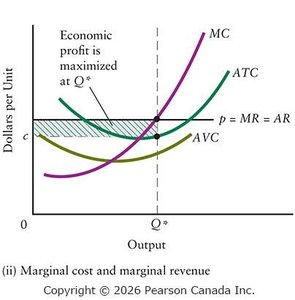
Short-Run Supply Curve
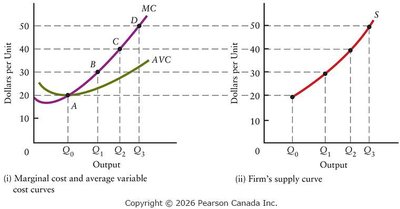
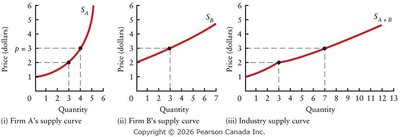
The competitive firm's supply curve is its marginal cost curve above the average variable cost curve. The industry supply curve is the horizontal sum of all firms' supply curves above AVC.
Short-Run Equilibrium
In short-run equilibrium, quantity demanded equals quantity supplied, and each firm maximizes profit given the market price. Firms may make losses, break even, or earn profits.
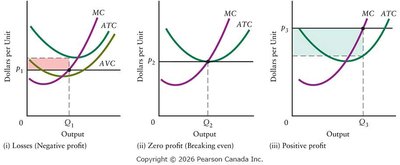
At , (losses), but (firm produces).
At , (break-even).
At , (positive profit).
Long-Run Decisions
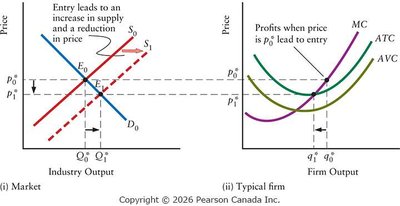
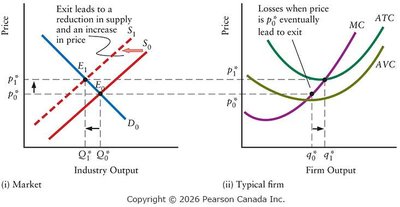
Entry and Exit
Long-run decisions are driven by profits:
Positive profits attract new firms (entry).
Zero profits mean no incentive to enter or exit.
Negative profits cause firms to exit.
Long-Run Equilibrium
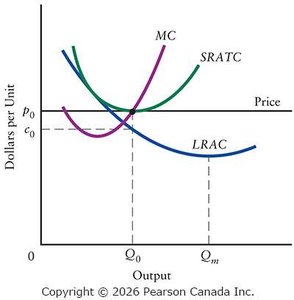
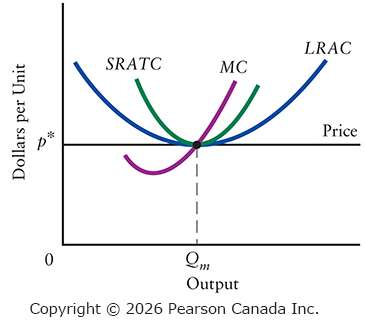
Long-run equilibrium occurs when firms earn zero economic profit, and the price equals the break-even price (covering all costs, including opportunity cost of capital).
Firms maximize profits given their capital.
No firms are suffering losses or earning profits.
Firms cannot increase profits by changing facility size; each operates at the minimum point of its LRAC curve.
Technological Change and Declining Industries
Continuous Technological Progress
Technological improvements lower costs for new plants, allowing them to earn profits and attract entry. Industry output expands, driving prices down to the new plants' average costs. Older plants may earn losses and eventually exit.
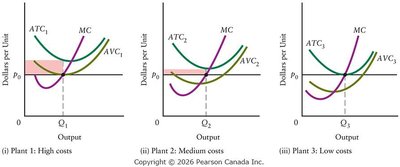
Declining Industries
When demand continually decreases, the industry contracts, and obsolete equipment is often a result of the decline. Firms may not replace antiquated equipment, and the industry shrinks over time.
Historical Example: Whales and Crude Oil
The decline of the whaling industry due to rising costs and the invention of kerosene parallels the current challenges faced by the oil industry, which faces increasing costs and the development of substitute energy sources.
