 뒤로
Elasticity in Microeconomics: Price, Income, and Supply Elasticities
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Elasticity
Introduction to Elasticity
Elasticity is a fundamental concept in microeconomics that measures the responsiveness of one variable to changes in another. In this chapter, we focus on price elasticity of demand, income elasticity of demand, cross elasticity of demand, and elasticity of supply. Understanding elasticity helps explain how changes in price, income, or related goods affect the quantity demanded or supplied.
Price Elasticity of Demand
Definition and Calculation
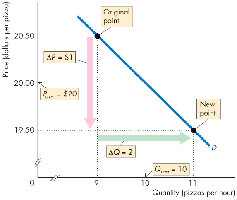
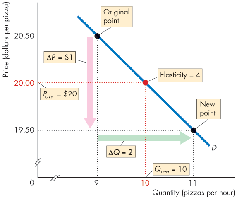
Price elasticity of demand is a units-free measure of the responsiveness of the quantity demanded of a good to a change in its price, holding all other influences constant. It is calculated using the following formula:
Formula:
Percentage changes are calculated using the average of the initial and new values to ensure consistency regardless of direction.
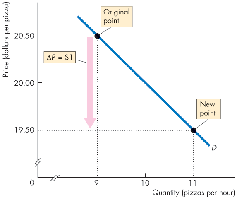
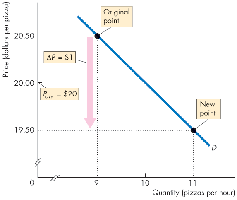
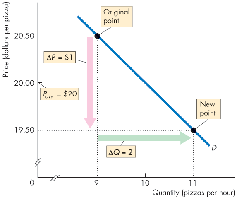
Example: If the price of pizza falls from (2/10) \times 100 = 20\%(1/20) \times 100 = 5\%.
Properties of Price Elasticity of Demand
Units-Free Measure: Elasticity is a ratio of percentages, so it is independent of the units used for price or quantity.
Minus Sign: The formula yields a negative value because price and quantity move in opposite directions, but the absolute value is used to indicate responsiveness.
Types of Demand Elasticity
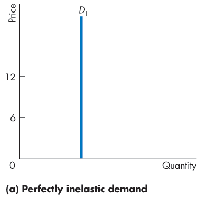
Perfectly Inelastic Demand: Elasticity = 0; quantity demanded does not change as price changes. The demand curve is vertical.
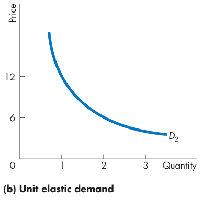
Unit Elastic Demand: Elasticity = 1; percentage change in quantity equals percentage change in price. The demand curve has a declining slope.
Inelastic Demand: Elasticity < 1; quantity demanded changes less than price.
Elastic Demand: Elasticity > 1; quantity demanded changes more than price.
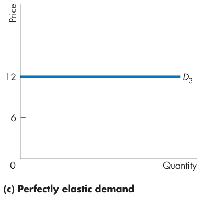
Perfectly Elastic Demand: Elasticity = ∞; quantity demanded changes infinitely with a tiny change in price. The demand curve is horizontal.
Factors Influencing Elasticity of Demand
Closeness of Substitutes: The more substitutes available, the more elastic the demand.
Proportion of Income Spent: Goods that take up a larger proportion of income tend to have more elastic demand.
Time Elapsed Since Price Change: Demand becomes more elastic as consumers have more time to adjust.
Elasticity Along a Linear Demand Curve
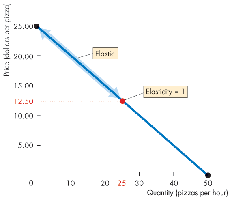
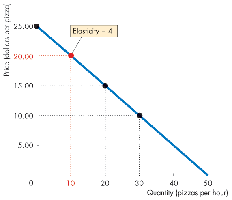
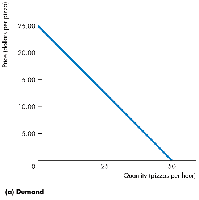
Elasticity varies along a linear demand curve. At the midpoint, demand is unit elastic. Above the midpoint, demand is elastic; below, it is inelastic.
Total Revenue and Elasticity
Relationship Between Total Revenue and Elasticity
Total revenue is the product of price and quantity sold. The effect of a price change on total revenue depends on the elasticity of demand:
If demand is elastic, a price cut increases total revenue.
If demand is inelastic, a price cut decreases total revenue.
If demand is unit elastic, a price cut leaves total revenue unchanged.
The total revenue test helps estimate elasticity by observing changes in total revenue after a price change.
Income Elasticity of Demand
Definition and Calculation
Income elasticity of demand measures how the quantity demanded of a good responds to changes in income, holding other factors constant. The formula is:
Classification:
If elasticity > 1, demand is income elastic and the good is a normal good.
If elasticity is between 0 and 1, demand is income inelastic and the good is a normal good.
If elasticity < 0, the good is an inferior good.
Cross Elasticity of Demand
Definition and Calculation
Cross elasticity of demand measures the responsiveness of demand for a good to changes in the price of a substitute or complement. The formula is:
Classification:
For substitutes, cross elasticity is positive.
For complements, cross elasticity is negative.
Elasticity of Supply
Definition and Calculation
Elasticity of supply measures the responsiveness of the quantity supplied to a change in price, holding other factors constant. The formula is:
Types of Supply Elasticity
Perfectly Inelastic Supply: Elasticity = 0; supply curve is vertical.
Unit Elastic Supply: Elasticity = 1; supply curve passes through the origin.
Perfectly Elastic Supply: Elasticity = ∞; supply curve is horizontal.
Factors Influencing Elasticity of Supply
Resource Substitution Possibilities: The easier it is to substitute resources, the greater the elasticity of supply.
Time Frame for Supply Decision: Elasticity increases as more time passes after a price change. Momentary supply is perfectly inelastic, short-run supply is somewhat elastic, and long-run supply is most elastic.
Glossary of Elasticity Measures
Summary Table
The following table summarizes the main elasticity measures:
Elasticity Type | Formula | Interpretation |
|---|---|---|
Price Elasticity of Demand | Responsiveness of demand to price changes | |
Income Elasticity of Demand | Responsiveness of demand to income changes | |
Cross Elasticity of Demand | Responsiveness of demand to price changes in substitutes/complements | |
Elasticity of Supply | Responsiveness of supply to price changes |
