 뒤로
Microeconomics: Foundations and Models – Chapter 1 Study Notes
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Economics: Foundations and Models
Introduction to Economics
Economics is the study of how people make choices to attain their goals, given their scarce resources. Because resources are limited but wants are unlimited, individuals, firms, and governments must make choices, leading to the study of trade-offs and opportunity costs. Economists use models—simplified versions of reality—to analyze real-world economic situations.
Scarcity and Choice
Scarcity: A situation in which unlimited wants exceed the limited resources available to fulfill those wants.
Economics: The study of the choices people make to attain their goals, given their scarce resources.
Economic Models: Simplified versions of reality used to analyze real-world economic situations.
Three Key Economic Ideas
Economists rely on three foundational ideas when analyzing choices and markets:
People Are Rational: Individuals and firms use all available information to achieve their goals, weighing costs and benefits to make optimal decisions.
People Respond to Economic Incentives: Changes in incentives lead to changes in behavior. For example, policies can unintentionally create new incentives, sometimes with unintended consequences.
Optimal Decisions Are Made at the Margin: Most decisions involve doing a little more or a little less of something. Marginal analysis compares the additional benefit (marginal benefit) and the additional cost (marginal cost) of an action.
The Economic Problem That Every Society Must Solve
Every society must answer three fundamental questions due to scarcity:
What goods and services will be produced? Deciding which goods and services to produce involves trade-offs, as producing more of one good means producing less of another. The opportunity cost is the highest-valued alternative given up to engage in an activity.
How will the goods and services be produced? Firms choose among different production methods, often influenced by costs and available technology.
Who will receive the goods and services produced? Distribution is often based on income, but government policies can alter this through taxes and welfare programs.
Types of Economic Systems
Centrally Planned Economy: The government decides how economic resources will be allocated.
Market Economy: Households and firms interacting in markets allocate resources.
Mixed Economy: Most decisions result from market interactions, but the government plays a significant role in resource allocation. The U.S. is best described as a mixed economy.
Efficiency and Equity
Productive Efficiency: Goods and services are produced at the lowest possible cost, often due to competition.
Allocative Efficiency: Production is in accordance with consumer preferences; every good or service is produced up to the point where the last unit provides a marginal benefit equal to the marginal cost.
Voluntary Exchange: Both buyers and sellers are made better off by transactions.
Equity: The fair distribution of economic benefits. There is often a trade-off between efficiency and equity.
Economic Models and Analysis
Economists use models to analyze economic events and policies. The process involves:
Deciding on assumptions
Formulating a testable hypothesis
Using data to test the hypothesis
Revising the model if necessary
Retaining the revised model for future analysis
Models rely on assumptions about consumer and firm behavior, such as consumers maximizing well-being and firms maximizing profit.
Positive vs. Normative Analysis
Positive Analysis: Concerned with what is (objective statements).
Normative Analysis: Concerned with what ought to be (subjective judgments).
Microeconomics vs. Macroeconomics
Microeconomics: The study of how households and firms make choices, interact in markets, and how the government influences these choices.
Macroeconomics: The study of the economy as a whole, including inflation, unemployment, and economic growth.
Economic Skills and Careers
Studying economics develops analytical and quantitative skills valuable in many careers, including business, government, and research. Economics majors often have higher average incomes, though this may be due to both the skills learned and self-selection into the field.
Important Economic Terms
Technology: The processes a firm uses to produce goods and services.
Capital: Manufactured goods used to produce other goods and services.
Appendix: Using Graphs and Formulas
Graphs in Economics
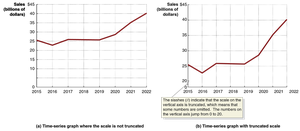
Graphs are essential tools for visualizing economic relationships and data. Common types include bar graphs, pie charts, and time-series graphs.
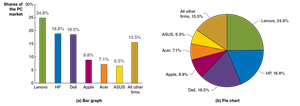
Plotting Economic Data
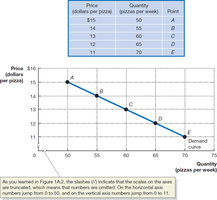
Economic relationships are often illustrated using two-dimensional graphs, with price on the vertical axis and quantity on the horizontal axis. Each point represents a price-quantity combination.
Calculating the Slope of a Line
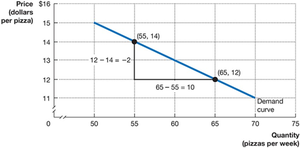
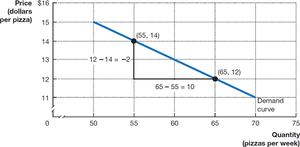
The slope of a line is calculated as the change in the y-axis variable divided by the change in the x-axis variable. For a demand curve, this shows how quantity demanded changes as price changes.
Formula:
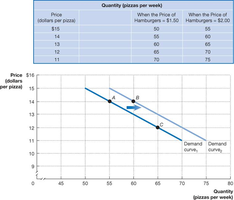
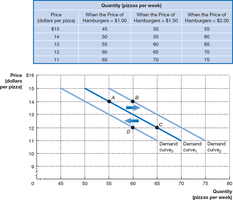
Showing Three Variables on a Graph
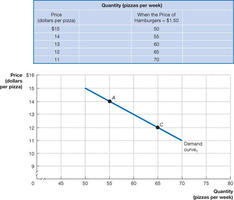
Graphs can illustrate the effect of a third variable by showing shifts in curves, such as the demand curve shifting due to changes in the price of a related good.
Positive and Negative Relationships
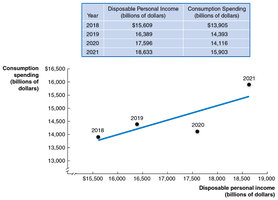
A positive relationship means both variables move in the same direction; a negative relationship means they move in opposite directions. For example, disposable income and consumption spending typically have a positive relationship.
Cause and Effect in Graphs
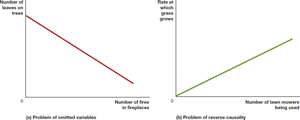
Graphs can suggest relationships but do not always prove causality. Problems such as omitted variables or reverse causality can lead to incorrect conclusions.
Linear and Nonlinear Relationships
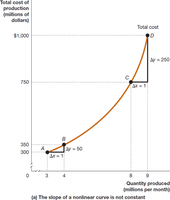
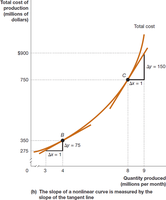
Most economic relationships are not perfectly linear. The slope of a nonlinear curve varies at different points and can be approximated by the slope of a tangent line at a specific point.
Formulas in Economics
Percentage Change:
Areas on Graphs: Total Revenue and Surplus
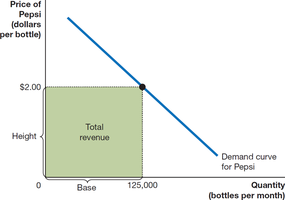
Total Revenue: The area of a rectangle under the demand curve, calculated as price times quantity.
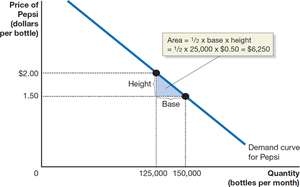
Area of a Triangle:
Summary of Using Formulas
Understand the economic concept the formula represents.
Use the correct formula for the problem.
Check that the calculated number is economically reasonable.
