 뒤로
Microeconomics: Foundations and Models – Chapter 1 Study Notes
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Economics: Foundations and Models
Introduction to Economics
Economics is the study of how people make choices to attain their goals, given their scarce resources. Because resources are limited but wants are unlimited, individuals, firms, and governments must make choices, leading to the study of scarcity and trade-offs.
Scarcity: A situation in which unlimited wants exceed the limited resources available to fulfill those wants.
Economic Models: Simplified versions of reality used to analyze real-world economic situations.
Key Economic Questions
What determines the prices of goods and services?
Why do firms engage in international trade?
How do government policies affect markets?
1.1 Three Key Economic Ideas
People Are Rational
Economists assume that individuals and firms use all available information to achieve their goals, weighing the benefits and costs of each action to make the best possible decision.
Example: A firm like Apple sets prices to maximize profit, not randomly.
People Respond to Economic Incentives
As incentives change, so do the actions that people take. Economic incentives can lead to unintended consequences when policies change.
Example: DNA databases for felons reduced repeat offenses, showing even criminals respond to incentives.
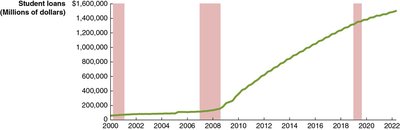
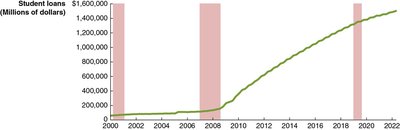
Application: Changes in student loan policies may incentivize colleges to increase tuition or students to borrow more.
Optimal Decisions Are Made at the Margin
Most decisions involve doing a little more or a little less of something. Economists use marginal analysis to compare the additional benefit and cost of an action.
Marginal Benefit (MB): The additional benefit from a small increase in an activity.
Marginal Cost (MC): The additional cost from a small increase in an activity.
Optimal Decision: Occurs where MB = MC.
1.2 The Economic Problem That Every Society Must Solve
Basic Economic Questions
Every society must answer three fundamental questions due to scarcity:
What goods and services will be produced? Trade-offs are necessary; producing more of one good means producing less of another. The opportunity cost is the highest-valued alternative given up.
How will the goods and services be produced? Firms choose production methods based on costs and available technology.
Who will receive the goods and services produced? Distribution often depends on income, but government policies can alter this distribution.
Types of Economic Systems
Centrally Planned Economy: The government decides how resources are allocated.
Market Economy: Households and firms interacting in markets allocate resources.
Mixed Economy: Most decisions result from market interactions, but the government plays a significant role.
Efficiency and Equity
Productive Efficiency: Goods and services are produced at the lowest possible cost.
Allocative Efficiency: Production matches consumer preferences; the last unit provides a marginal benefit equal to marginal cost.
Equity: The fair distribution of economic benefits. There is often a trade-off between efficiency and equity.
1.3 Economic Models
How Economists Use Models
Economic models are simplified frameworks for analyzing real-world issues. The process of building a model includes:
Deciding on assumptions
Formulating a testable hypothesis
Using data to test the hypothesis
Revising the model if necessary
Retaining the model for future analysis
Assumptions and Hypotheses
Assumptions: Simplify reality to make models useful (e.g., consumers maximize well-being, firms maximize profit).
Hypothesis: A statement about an economic variable that can be tested with data.
Positive vs. Normative Analysis
Positive Analysis: Concerned with what is (facts and cause-effect relationships).
Normative Analysis: Concerned with what ought to be (value judgments).
1.4 Microeconomics and Macroeconomics
Distinguishing Microeconomics and Macroeconomics
Microeconomics: The study of how households and firms make choices, interact in markets, and how the government influences these choices.
Macroeconomics: The study of the economy as a whole, including inflation, unemployment, and economic growth.
Examples of Microeconomic Issues | Examples of Macroeconomic Issues |
|---|---|
How consumers react to price changes | Why economies experience recessions |
How firms set prices | What determines inflation rates |
Effects of AI on production costs | What determines exchange rates |
1.5 Economic Skills and Economics as a Career
Skills Gained from Studying Economics
Analyzing choices and their consequences
Understanding and applying economic models
Interpreting data and trends
Making informed recommendations
Applications in Careers
Company/Organization | Role of an Economist |
|---|---|
Ford Motor Company | Forecast demand for electric cars |
Goldman Sachs | Forecast interest rates |
McDonald's | Decide on opening new restaurants |
Pfizer | Analyze costs and benefits of new treatments |
Federal Trade Commission | Analyze effects of mergers |
Economics Majors and Income
Median Wage, Early Career (22-27) | Median Wage, Midcareer (35-45) | |
|---|---|---|
Economics majors | $60,000 | $91,000 |
All majors | $45,000 | $72,000 |
Additional info: Higher earnings may be due to skills learned or self-selection of high-earning individuals into economics.
1.6 A Preview of Important Economic Terms
Technology: The processes a firm uses to produce goods and services.
Capital: Manufactured goods used to produce other goods and services.
Appendix: Using Graphs and Formulas
Graphs in Economics
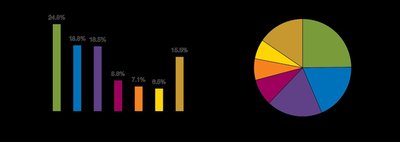
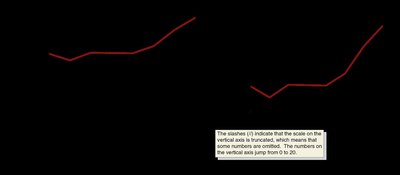
Graphs are visual tools that help illustrate economic relationships and trends. Common types include bar graphs, pie charts, and time-series graphs.
Plotting Economic Data
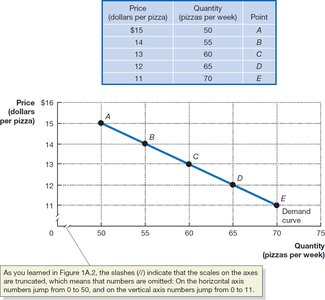
Graphs often plot price on the vertical axis and quantity on the horizontal axis to show relationships such as demand curves.
Calculating Slope
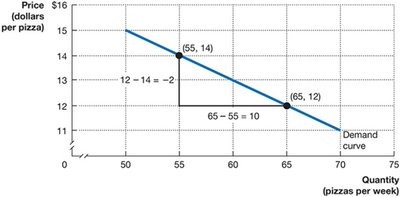
The slope of a line is calculated as the change in the y-axis variable divided by the change in the x-axis variable:
Showing Multiple Variables
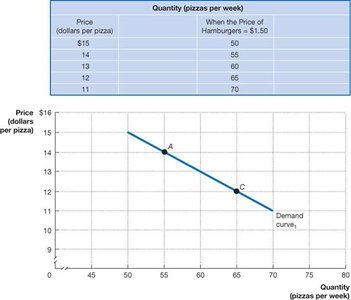
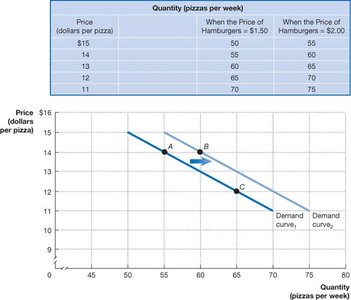
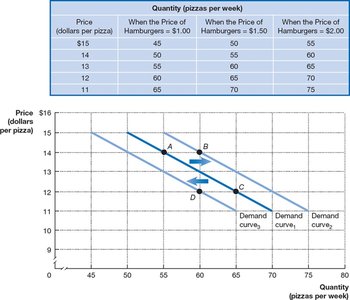
Graphs can show how a third variable affects the relationship between two variables, such as how the price of a related good shifts the demand curve.
Positive and Negative Relationships
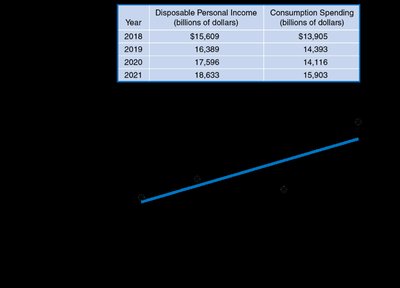
A positive relationship means both variables move in the same direction; a negative relationship means they move in opposite directions.
Cause and Effect in Graphs
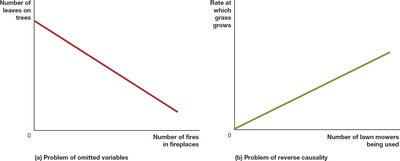
Graphs can illustrate relationships but do not always prove causality. Omitted variables or reverse causality can lead to incorrect conclusions.
Linear and Nonlinear Relationships
Most economic relationships are not perfectly linear. The slope of a nonlinear curve can be approximated over a section or measured at a point using a tangent line.
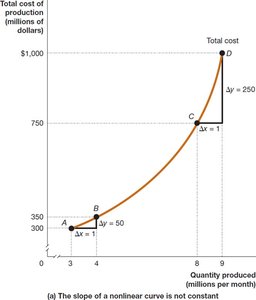
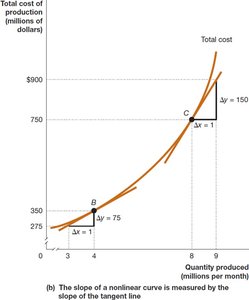
Formulas in Economics
Percentage Change:
Areas in Graphs
Area of a Rectangle (Total Revenue):
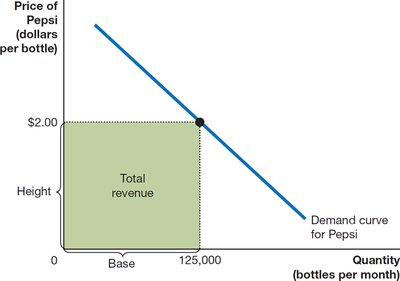
Area of a Triangle:
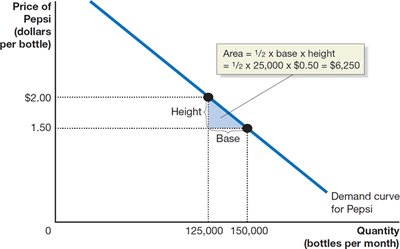
Steps for Using Formulas
Understand the economic concept the formula represents.
Use the correct formula for the problem.
Check that the result is economically reasonable.
