 뒤로
Short-Run Costs and Output Decisions in Microeconomics
스터디 가이드 - 스마트 노트
 자료에 맞춘 맞춤형 노트, 핵심 정의, 예시, 맥락을 확장해 제공합니다.
Short-Run Costs and Output Decisions
Overview
This chapter explores the fundamental concepts of short-run costs and output decisions in microeconomics, focusing on how firms calculate costs, make production decisions, and maximize profits in perfectly competitive markets.
Costs in the Short Run
Types of Costs
Firms face various types of costs in the short run, which are essential for making production decisions:
Fixed Cost: Costs that do not depend on the level of output. These are incurred even if the firm produces nothing. There are no fixed costs in the long run.
Variable Cost: Costs that depend on the level of production chosen. These change as output changes.
Total Cost (TC): The sum of total fixed costs and total variable costs.
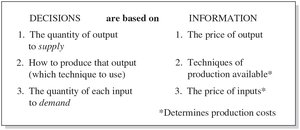
Decisions Facing Firms
Firms must decide:
The quantity of output to supply
How to produce that output (which technique to use)
The quantity of each input to demand
These decisions are based on information about the price of output, available production techniques, and input prices.
Fixed Costs
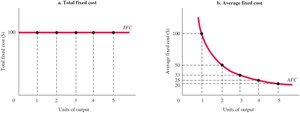
Total Fixed Cost (TFC): The total of all costs that do not change with output, even if output is zero. Also known as overhead.
Average Fixed Cost (AFC): Total fixed cost divided by the number of units of output; a per-unit measure of fixed costs. As output increases, AFC declines because the fixed cost is spread over more units.
Spreading Overhead: The process of dividing total fixed costs by more units of output, causing AFC to decline as quantity rises.
Variable Costs
Total Variable Cost (TVC): The total of all costs that vary with output in the short run. The TVC curve shows the relationship between TVC and the level of output.
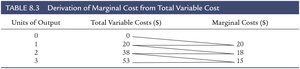
Marginal Cost (MC): The increase in total cost from producing one more unit of output. MC reflects changes in variable costs.
Units of Output | Total Variable Costs ($) | Marginal Costs ($) |
|---|---|---|
0 | 0 | 20 |
1 | 20 | 18 |
2 | 38 | 15 |
3 | 53 |
The Shape of the Marginal Cost Curve
In the short run, firms are constrained by some fixed input, leading to diminishing returns to variable inputs and limited production capacity. As capacity is approached, marginal costs rise, reflecting increasing costs for additional output.
Average Variable Cost (AVC)
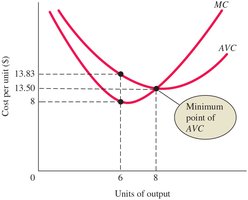
Average Variable Cost (AVC): Total variable cost divided by the number of units of output; a per-unit measure of variable costs.
When MC is below AVC, AVC declines. When MC is above AVC, AVC increases. MC intersects AVC at the minimum point of AVC.
Total Costs
Relationship Between Costs
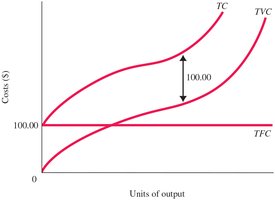
Total Cost (TC): TC = TFC + TVC. The TC curve has the same shape as the TVC curve but is higher by the amount of TFC.
Average Total Cost (ATC)
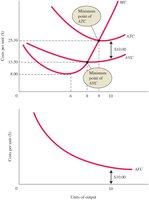
Average Total Cost (ATC): ATC = TC divided by the number of units of output. ATC = AVC + AFC at all levels of output. As output increases, AFC falls, so ATC and AVC get closer but never meet.
Relationship Between ATC and MC
If MC is below ATC, ATC declines toward MC. If MC is above ATC, ATC increases. MC intersects ATC at its minimum point, just as it does with AVC.
Output Decisions: Revenues, Costs, and Profit Maximization
Perfect Competition
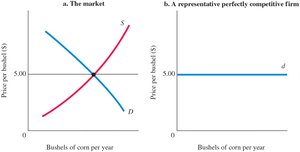
Perfect Competition: An industry structure with many firms producing identical products, none of which can control prices. New competitors can freely enter, and old firms can exit. Firms face a perfectly elastic demand curve.
Total Revenue and Marginal Revenue
Total Revenue (TR): The total amount a firm receives from selling its product: price per unit times quantity produced.
Marginal Revenue (MR): The additional revenue from selling one more unit. In perfect competition, MR equals the price.
Profit Maximization
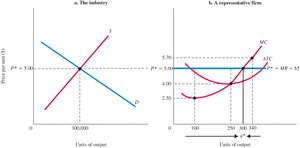
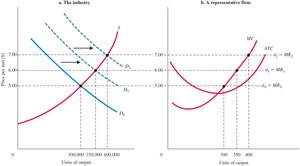
Firms maximize profit by producing up to the point where MR equals MC. As long as MR > MC, increasing output adds profit. The profit-maximizing output is where:
In perfect competition,
The Short-Run Supply Curve
The MC curve of a perfectly competitive, profit-maximizing firm is its short-run supply curve, except when price is so low that the firm should shut down.
Key Terms and Equations
Average Fixed Cost (AFC):
Average Variable Cost (AVC):
Average Total Cost (ATC):
Marginal Cost (MC):
Total Revenue (TR):
Marginal Revenue (MR):
Profit Maximization Condition: (or in perfect competition)
Summary Table: Cost Concepts
Concept | Definition |
|---|---|
Fixed Cost (FC) | Cost that does not vary with output |
Variable Cost (VC) | Cost that varies with output |
Total Cost (TC) | Sum of FC and VC |
Average Fixed Cost (AFC) | FC divided by output |
Average Variable Cost (AVC) | VC divided by output |
Average Total Cost (ATC) | TC divided by output |
Marginal Cost (MC) | Change in TC from one more unit |
Total Revenue (TR) | Price times quantity sold |
Marginal Revenue (MR) | Change in TR from one more unit |
Additional info:
These notes provide a comprehensive overview of short-run costs and output decisions, including graphical representations and key formulas. The chapter prepares students for understanding profit maximization and supply decisions in perfectly competitive markets.
