 Back
Chapter 1: Foundations and Models in Microeconomics – Structured Study Notes
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Economics: Foundations and Models
Three Key Economic Ideas
Economics is the study of how people make choices to attain their goals, given scarce resources. Three fundamental ideas guide economic analysis:
People are rational: Individuals and firms use all available information to achieve their objectives, weighing costs and benefits to make optimal decisions.
People respond to economic incentives: Changes in incentives alter behavior. For example, government policies can unintentionally create new incentives for firms or consumers.
Optimal decisions are made at the margin: Most choices involve incremental changes. Marginal analysis compares the additional benefit (marginal benefit) and additional cost (marginal cost) of an action.
Example: Apple sets iPhone prices to maximize profit, not randomly. Students may choose to study more if the marginal benefit exceeds the marginal cost.
Marginal Analysis Formula:
Optimal decision: Continue as long as .
The Economic Problem That Every Society Must Solve
Scarcity means unlimited wants exceed limited resources, forcing societies to make choices. Every economy must answer:
What goods and services will be produced? Trade-offs are necessary; producing more of one good means less of another.
How will goods and services be produced? Firms choose production methods based on costs and available technology.
Who will receive the goods and services produced? Distribution depends on income, government policy, and societal values.
Opportunity Cost: The value of the next best alternative foregone when making a choice.
Trade-off Example: Funding space exploration may require reducing cancer research funding.
Centrally Planned, Market, and Mixed Economies
Economies differ in how resources are allocated:
Centrally planned economy: Government decides allocation.
Market economy: Households and firms interact in markets to allocate resources.
Mixed economy: Most decisions are market-based, but government intervenes to achieve social goals.
The U.S. is best described as a mixed economy, with significant government intervention.
Efficiency and Equity in Market Economies
Market economies promote:
Productive efficiency: Goods produced at lowest possible cost.
Allocative efficiency: Production matches consumer preferences; last unit provides marginal benefit equal to marginal cost.
Voluntary exchange: Both buyer and seller benefit from transactions.
However, markets may not always be fully efficient or equitable. Governments may intervene to improve fairness (equity), sometimes at the cost of efficiency.
Economic Models
Economists use models—simplified representations of reality—to analyze issues and predict outcomes. Model-building steps:
Decide on assumptions.
Formulate a testable hypothesis.
Use data to test the hypothesis.
Revise the model if needed.
Retain the model for future analysis.
Models rely on behavioral assumptions, such as consumers maximizing well-being and firms maximizing profit.
Positive vs. Normative Analysis
Economists distinguish between:
Positive analysis: What is (objective, fact-based).
Normative analysis: What ought to be (subjective, value-based).
Most economic research is positive, but policy decisions often require normative judgments.
Microeconomics vs. Macroeconomics
Economics is divided into two main branches:
Microeconomics: Studies individual households, firms, and markets.
Macroeconomics: Studies the economy as a whole, including inflation, unemployment, and growth.
Economic Skills and Careers
Studying economics develops analytical skills valuable in many careers, including business, government, and consulting. Economics majors often earn higher salaries, though causation versus correlation is debated.
Important Economic Terms
Key terms to know:
Scarcity: Limited resources versus unlimited wants.
Opportunity cost: Value of the next best alternative.
Technology: Processes used to produce goods/services.
Capital: Manufactured goods used for production.
Appendix: Using Graphs and Formulas
Graphs in Economics
Graphs are essential tools for visualizing economic relationships. Common types include:
Bar graphs: Compare quantities across categories.
Pie charts: Show proportions of a whole.
Time-series graphs: Track changes over time.
Scatter plots: Show relationships between two variables.
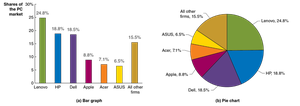
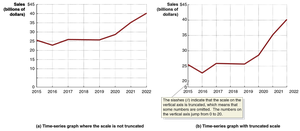
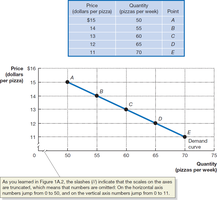
Plotting Price and Quantity
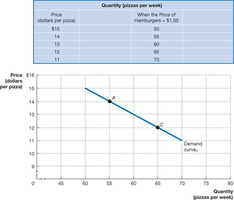
Demand curves illustrate the relationship between price and quantity demanded. Each point represents a price-quantity pair.
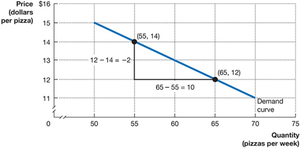
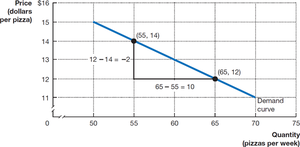
Calculating the Slope of a Line
The slope measures the rate of change between two variables. For a straight line:
Showing Three Variables on a Graph
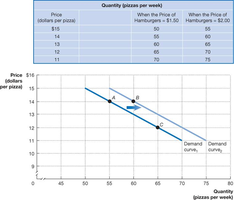
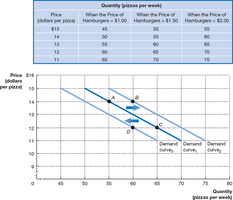
Graphs can illustrate how a third variable affects the relationship between two others, such as how the price of hamburgers shifts the demand curve for pizza.
Positive and Negative Relationships
A positive relationship means both variables increase together; a negative relationship means one increases as the other decreases.
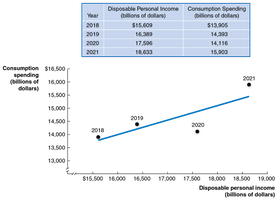
Cause and Effect in Graphs
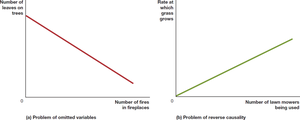
Graphs can suggest relationships, but causality is not always clear. Problems include omitted variables and reverse causality.
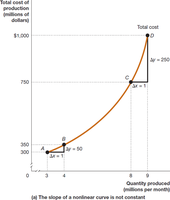
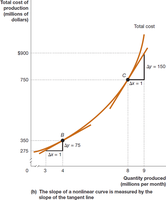
Linear vs. Nonlinear Relationships
Most economic relationships are not perfectly linear. Nonlinear curves have varying slopes at different points.
Formulas in Economics
Formulas are used to calculate changes and relationships. For example, percentage change:
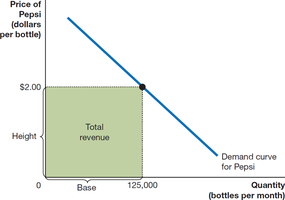
Graphing Total Revenue
Total revenue is the product of price and quantity. The area of a rectangle on a graph represents total revenue.
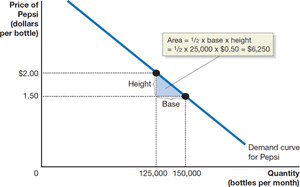
Area of a Triangle
The area of a triangle is used in economic graphs, such as consumer or producer surplus:
Summary of Using Formulas
Understand the economic concept represented by the formula.
Use the correct formula for the problem.
Check that the calculated value is economically reasonable.
Additional info: These notes expand on brief points from the original slides, providing definitions, examples, and formulas for clarity. Images included are directly relevant to the adjacent explanations, reinforcing key concepts in graphical analysis.
