 Back
Chapter 2: Trade-offs, Comparative Advantage, and the Market System – Microeconomics Study Notes
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Trade-offs, Comparative Advantage, and the Market System
Scarcity and Trade-offs
Scarcity is a fundamental concept in economics, referring to the situation where unlimited wants exceed the limited resources available to fulfill those wants. Because resources are scarce, individuals, firms, and governments must make choices about how to allocate them, leading to trade-offs.
Scarcity: The condition that arises because resources are limited relative to wants.
Trade-off: The act of giving up one thing to obtain something else.
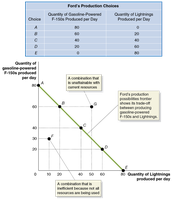
Example: Ford must decide whether to allocate resources to produce more electric vehicles (EVs) or gasoline-powered F-150s. Increasing production of one type means reducing production of the other.
Production Possibilities Frontier (PPF) and Opportunity Costs
The Production Possibilities Frontier (PPF) is a curve that shows the maximum attainable combinations of two goods that can be produced with available resources and current technology. The PPF illustrates the concepts of trade-offs and opportunity costs.
PPF: Represents the boundary between attainable and unattainable production combinations.
Opportunity Cost: The value of the next best alternative that is forgone when a choice is made.
Points on the PPF: Efficient and attainable.
Points below the PPF: Inefficient (not all resources are used).
Points above the PPF: Unattainable with current resources.
Equation: Opportunity cost of producing more of Good X = Amount of Good Y forgone / Amount of Good X gained.
Increasing Marginal Opportunity Costs
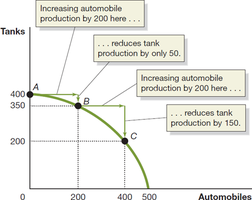
Marginal opportunity costs often increase as more resources are devoted to an activity. This is because resources are not equally suited to all tasks; the first resources switched are those best suited for the new activity, while later resources are less efficient.
Law of Increasing Opportunity Costs: As production of a good increases, the opportunity cost of producing an additional unit rises.
Example: Increasing automobile production by 200 units may reduce tank production by only 50 units initially, but later by 150 units.
Economic Growth and Shifts in the PPF
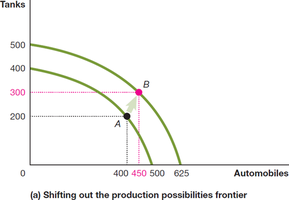
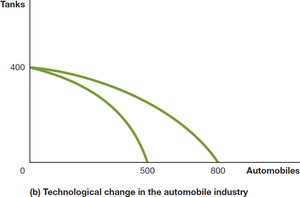
Economic growth occurs when an economy's capacity to produce goods and services increases. This is represented by an outward shift in the PPF, allowing more of both goods to be produced. Technological improvements can also shift the PPF outward for specific goods.
Economic Growth: The ability of the economy to increase production over time.
Technological Change: Improvements in technology can increase the production of one good without affecting the other.
Comparative Advantage and Trade
Comparative advantage is the basis for trade. It refers to the ability of an individual, firm, or country to produce a good or service at a lower opportunity cost than competitors. Even if one party has an absolute advantage in producing all goods, both parties can benefit from trade by specializing according to their comparative advantage.
Absolute Advantage: The ability to produce more of a good or service with the same amount of resources.
Comparative Advantage: The ability to produce a good at a lower opportunity cost.
Specialization: Focusing on the production of goods for which one has a comparative advantage.
Gains from Trade: Both parties can consume more than they could without trade.
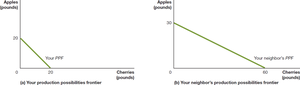
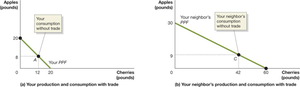
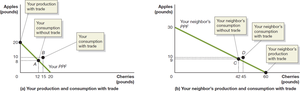
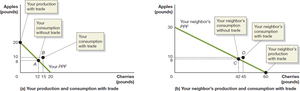
Table: Opportunity Costs and Gains from Trade
The following table summarizes the gains from trade:
Person | Apples Consumed (No Trade) | Cherries Consumed (No Trade) | Apples Consumed (With Trade) | Cherries Consumed (With Trade) |
|---|---|---|---|---|
You | 8 | 12 | 10 | 15 |
Neighbor | 9 | 42 | 10 | 45 |
Additional info: Table values inferred from the text and images.
The Market System
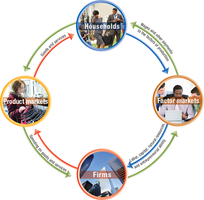
A market system is a group of buyers and sellers of a good or service, and the institution or arrangement by which they come together to trade. The market system relies on the interaction between households and firms.
Households: Provide factors of production (labor, capital, natural resources, entrepreneurial ability).
Firms: Purchase factors of production and use them to produce goods and services.
Factor Market: Where factors of production are bought and sold.
Product Market: Where goods and services are bought and sold.
The Four Factors of Production
Labor: All types of work.
Capital: Physical capital used to produce other goods.
Natural Resources: Raw materials used in production.
Entrepreneurial Ability: The skill to combine resources to produce goods and services.
The Circular-Flow Diagram
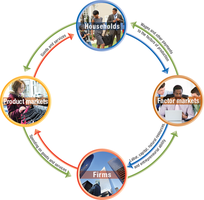
The circular-flow diagram illustrates how households and firms interact in product and factor markets. It shows the flow of resources, goods, services, and money in the economy.
Households provide factors of production to firms.
Firms provide goods and services to households.
Money flows from firms to households for factors of production, and from households to firms for goods and services.
The Gains From Free Markets
Free markets, with few government restrictions, have historically led to higher living standards compared to centrally planned economies. Adam Smith argued for free markets, emphasizing the role of the "invisible hand" in guiding resources to their most valued uses.
Free Market: Minimal government intervention in production and employment of resources.
Invisible Hand: The self-interested actions of individuals and firms lead to outcomes that benefit society as a whole.
The Market Mechanism and Price Signals
The market mechanism relies on flexible prices to signal the relative worth of goods and services. When consumer preferences change, prices adjust, and firms respond by reallocating resources to more profitable activities.
Price Signals: Indicate where resources should be allocated.
Flexible Prices: Essential for efficient resource allocation.
Knowledge and the Market System
Markets process vast amounts of information, much of which is local and specific. Individuals use their knowledge to maximize profit, which helps transmit price signals throughout the economy and adapt to changing conditions.
The Role of the Entrepreneur
Entrepreneurs bring together the factors of production to create goods and services, often introducing innovations that drive economic growth. Their willingness to take risks is vital for the development of new products and industries.
The Legal Basis of a Successful Market System
While free markets minimize government intervention, a sound legal environment is necessary for markets to function effectively. This includes protection of private property, enforcement of contracts, and an independent court system.
Property Rights: The exclusive right to use, buy, or sell property.
Contract Enforcement: Ensures that agreements are honored.
Independent Courts: Critical for resolving disputes and maintaining trust in the market system.
