 Back
Economic Efficiency, Government Price Setting, and Taxes: Microeconomics Study Guide
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Economic Efficiency, Government Price Setting, and Taxes
Consumer Surplus and Producer Surplus
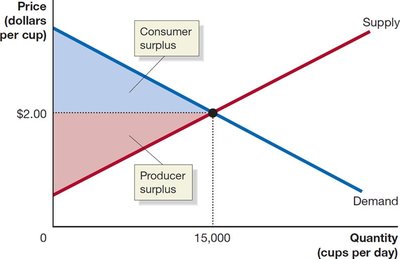
Consumer surplus and producer surplus are fundamental concepts in microeconomics, measuring the net benefits that consumers and producers receive from participating in markets.
Consumer Surplus: The difference between the highest price a consumer is willing to pay for a good or service and the actual price paid.
Producer Surplus: The difference between the lowest price a firm would accept for a good or service and the price it actually receives.
Surplus: In economics, surplus refers to the benefit derived from market transactions, above what is used or needed.
Marginal Benefit: The additional benefit to a consumer from consuming one more unit of a good or service.
Marginal Cost: The change in a firm’s total cost from producing one more unit of a good or service.
Example: The market for chai tea can be used to illustrate these concepts. Four consumers (Theresa, Tom, Terri, Tim) each have a maximum price they are willing to pay for a cup of chai tea. The market demand curve is derived from these willingness-to-pay values.
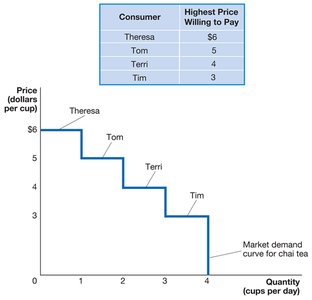
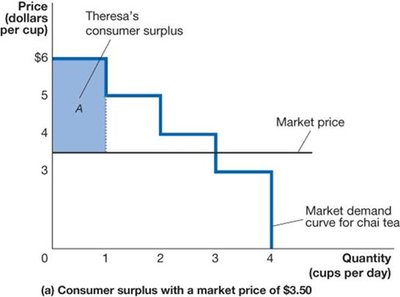
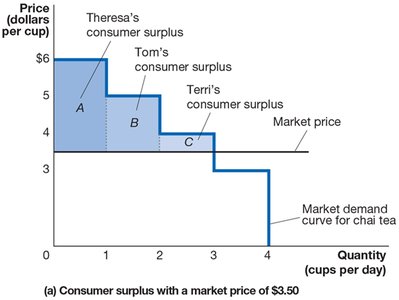
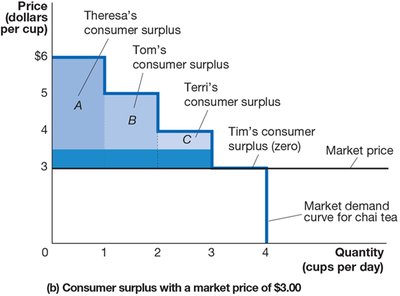
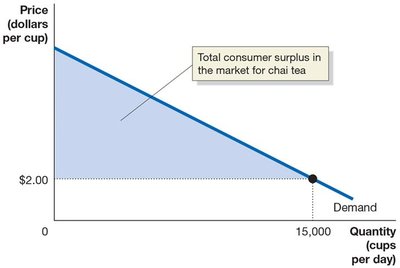
Consumer surplus is visually represented as the area below the demand curve and above the market price. For example, if the market price is $3.50, Theresa, Tom, and Terri each receive a surplus, calculated as the difference between their willingness to pay and the market price.
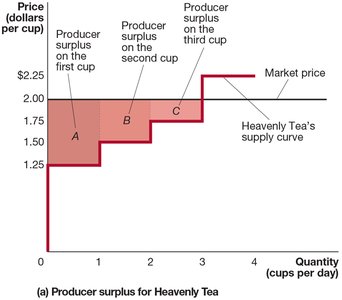
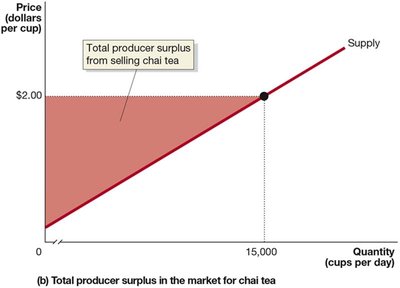
Producer surplus is similarly represented as the area above the supply curve and below the market price. For Heavenly Tea, a small producer, the surplus is calculated for each cup sold.
Formulas:
Consumer Surplus = Total Benefit Received by Consumers − Total Amount Paid
Producer Surplus = Total Amount Received by Firms − Cost of Providing the Good or Service
The Efficiency of Competitive Markets
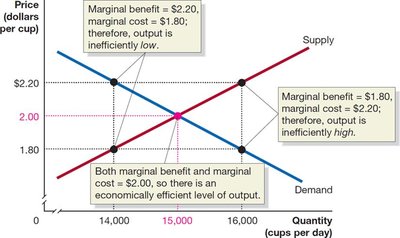
Economic efficiency in a market is achieved when resources are allocated in a way that maximizes the sum of consumer and producer surplus, known as economic surplus.
Economic Efficiency: A market outcome in which the marginal benefit to consumers of the last unit produced equals its marginal cost of production, and the sum of consumer and producer surplus is maximized.
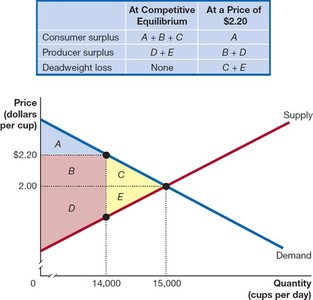
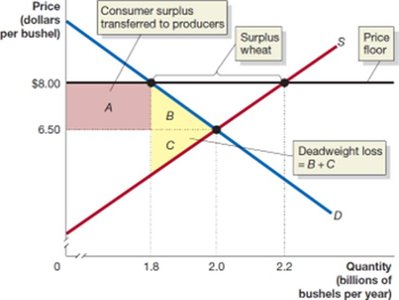
Deadweight Loss: The reduction in economic surplus resulting from a market not being in competitive equilibrium.
At the competitive equilibrium, marginal benefit equals marginal cost, and economic surplus is maximized.
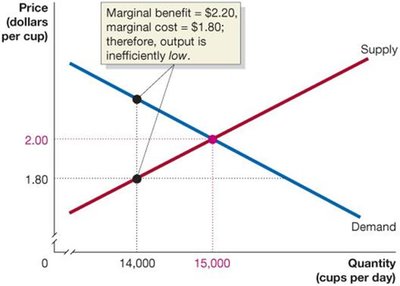
When the market is not in equilibrium, deadweight loss occurs, representing inefficiency.
Government Intervention: Price Floors and Price Ceilings
Governments may impose price floors (minimum prices) or price ceilings (maximum prices) to influence market outcomes. These interventions often lead to inefficiencies and deadweight loss.
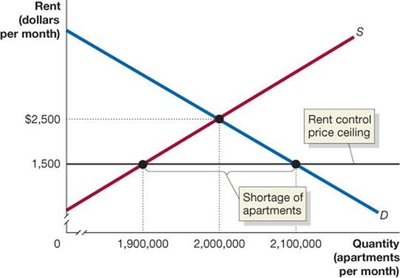
Price Ceiling: A legally determined maximum price that sellers may charge.
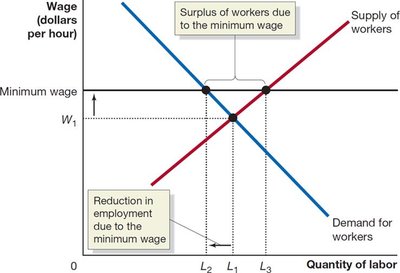
Price Floor: A legally determined minimum price that sellers may receive.
Examples: Minimum wages, rent controls, agricultural price supports.
Price floors in the wheat market transfer consumer surplus to producers and create deadweight loss.
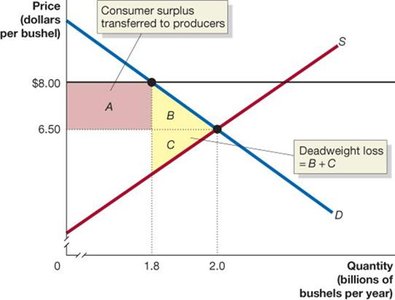
Minimum wage policies are a form of price floor in labor markets, potentially reducing employment and creating deadweight loss.
Rent ceilings (price ceilings) in housing markets create shortages and transfer producer surplus from landlords to renters, also resulting in deadweight loss.
The Economic Effect of Taxes
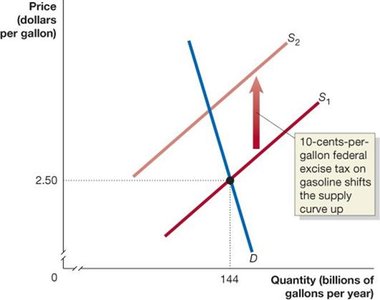
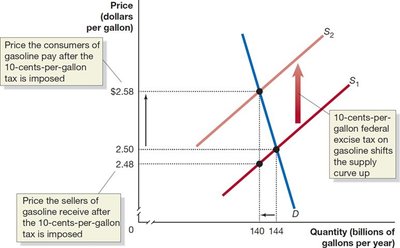
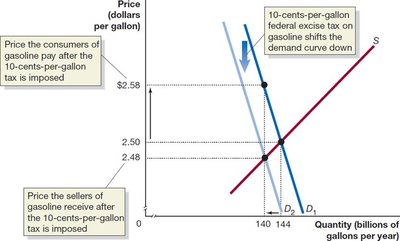
Taxes are used by governments to fund activities, often assessed as a per-unit tax. Taxes shift the supply curve upward, increase prices for consumers, decrease prices received by producers, and create deadweight loss.
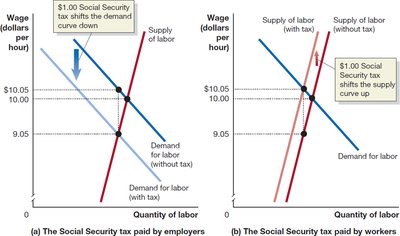
Tax Incidence: The actual division of the burden of a tax between buyers and sellers in a market.
Excess Burden: The deadweight loss from a tax.
Example: A $1.00-per-pack tax on cigarettes shifts the supply curve up, increases the price paid by consumers, and decreases the price received by producers.
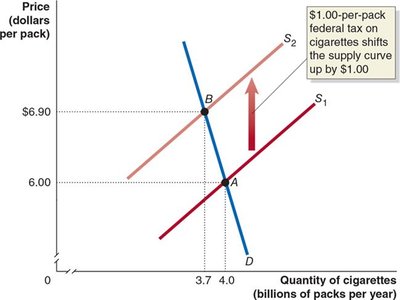
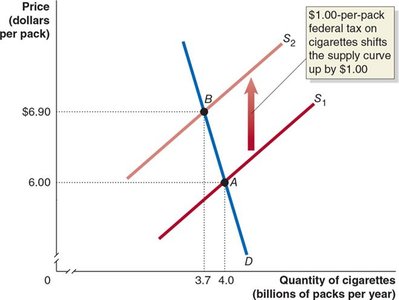
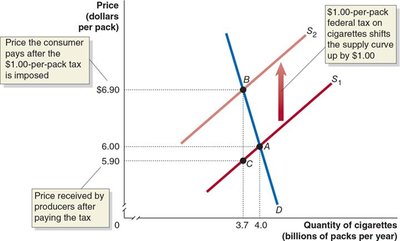
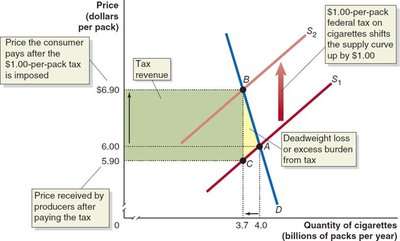
Tax incidence depends on the relative slopes of the demand and supply curves, not on who has the legal obligation to pay the tax.
Appendix: Quantitative Demand and Supply Analysis
Quantitative analysis involves using equations to determine equilibrium price and quantity, and to estimate consumer and producer surplus.
Demand Equation:
Supply Equation:
Equilibrium Condition:
Equilibrium Price:
Equilibrium Quantity:
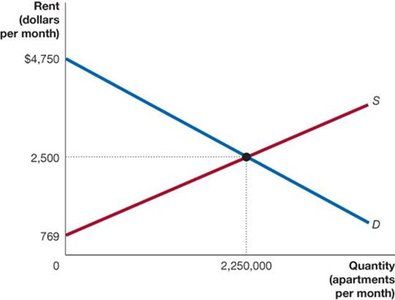
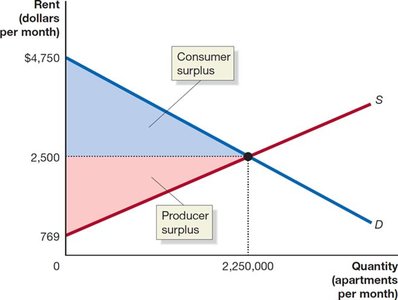
Consumer and producer surplus can be calculated using the area of triangles:
Consumer Surplus: million
Producer Surplus: million
Rent controls reduce producer surplus and create deadweight loss:
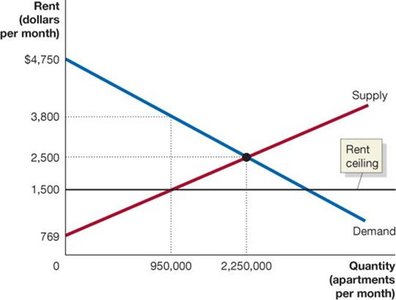
Competitive Equilibrium | Rent Control | |
|---|---|---|
Consumer Surplus | $2,531 | $2,636 |
Producer Surplus | $1,947 | $347 |
Deadweight Loss | $0 | $1,495 |
Additional info: These notes expand on the original slides and figures by providing definitions, formulas, and context for each concept, ensuring a comprehensive and self-contained study guide for exam preparation.
