 Back
Introduction to Economics: Foundations and Models
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Economics: Foundations and Models
Introduction to Economics
Economics is the study of how societies allocate scarce resources to produce goods and services and distribute them among individuals. It is divided into two main branches:
Microeconomics: Focuses on individual decision-making and the interactions between households and firms.
Macroeconomics: Examines the overall ups and downs in the economy, including policies to mitigate economic fluctuations.
Types of Economic Systems
Economic systems determine how resources are allocated and decisions are made regarding production and distribution.
Market Economy: Decisions are decentralized; individuals and firms decide what to produce and how to distribute goods and services. No central authority dictates these choices.
Command Economy: A central authority makes all decisions about production and distribution. This system is characterized by government control over resources and economic activity.
Microeconomics: Individual Decision-Making
Microeconomics analyzes how individuals make choices and how these choices interact in markets.
Individual Choice: Choices are necessary because resources are scarce.
Scarcity: A resource is scarce when there is not enough to satisfy all the ways society wants to use it.
Resources: Anything used to produce something else. The main types are:
Land
Labor
Capital
Human capital
Opportunity Cost
The true cost of any decision is its opportunity cost: what you must give up in order to get something.
Opportunity cost is central to economic thinking and decision-making.
Example: Choosing to study means giving up time that could be spent elsewhere.
Principles of Individual Choice
Marginal Decision-Making: "How much" is a decision at the margin, comparing the costs and benefits of incremental changes.
Trade-off: Every choice involves a trade-off between costs and benefits.
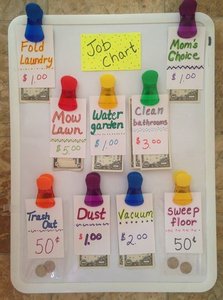
Incentives: People respond to incentives, exploiting opportunities to make themselves better off. An incentive is anything that offers rewards to people who change their behavior.
Interaction and Gains from Trade
Interaction: Individual choices interact in markets, affecting others.
Gains from Trade: Trade allows all participants to consume more than they otherwise could, due to specialization and exchange.
Specialization: Each person specializes in the task they are best at, increasing overall efficiency.
Efficiency and Equity
Efficiency: Resources should be used efficiently to achieve society’s goals. Efficiency means taking all opportunities to make some people better off without making others worse off.
Equity: A condition in which everyone gets their "fair share." There are many definitions of equity, and it often conflicts with efficiency.
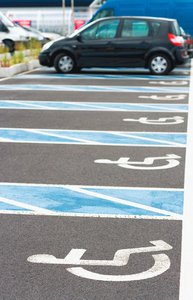
Example: Disabled parking spaces prioritize equity over efficiency.
Economy-Wide Interactions
One person’s spending is another person’s income, creating a circular flow of economic activity.
During recessions, a drop in business spending leads to less income, less spending, further drops in business spending, layoffs, and rising unemployment.
Key Terms and Concepts
Scarcity: Limited nature of resources.
Opportunity Cost: The value of the next best alternative forgone.
Efficiency: Maximizing output without making anyone worse off.
Equity: Fair distribution of resources.
Incentives: Rewards or penalties that influence behavior.
Specialization: Focusing on tasks one is best at.
Trade: Exchange of goods and services for mutual benefit.
Summary Table: Market vs. Command Economy
Feature | Market Economy | Command Economy |
|---|---|---|
Decision-Making | Decentralized | Centralized |
Resource Allocation | By price mechanism | By government |
Incentives | Profit and competition | Government directives |
Examples | USA, UK | Former USSR, North Korea |
