 Back
Microeconomics Foundations and Models: Chapter 1 Study Guide
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Economics: Foundations and Models
Three Key Economic Ideas
Economics is built on three fundamental concepts: rationality, incentives, and marginal decision-making. These principles guide how individuals and firms make choices in a world of scarcity.
People Are Rational: Economic agents use available information to achieve their goals, weighing costs and benefits to make optimal decisions.
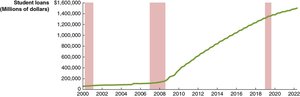
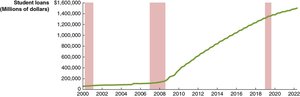
People Respond to Economic Incentives: Changes in incentives alter behavior. For example, policies affecting student loans can unintentionally encourage colleges to raise tuition.
Optimal Decisions Are Made at the Margin: Most choices involve incremental changes. Marginal analysis compares the additional benefit (marginal benefit) and additional cost (marginal cost) of an action.
Market: A group of buyers and sellers of a good or service and the institution or arrangement by which they come together to trade.
Additional info: Marginal analysis is central to microeconomic reasoning, as it helps determine the optimal allocation of resources.
The Economic Problem That Every Society Must Solve
Scarcity forces societies to make choices about resource allocation. Every society must answer three fundamental questions:
What goods and services will be produced? Due to limited resources, increasing production of one good requires reducing production of another (trade-off).
How will the goods and services be produced? Firms choose production methods based on costs and available technology.
Who will receive the goods and services produced? Distribution is often based on income, but government policies can alter this.
Opportunity Cost: The highest-valued alternative that must be given up to engage in an activity.
Trade-off: Because of scarcity, producing more of one good means producing less of another.
Centrally Planned Economies Versus Market Economies
Economic systems differ in how resources are allocated:
Centrally Planned Economy: The government decides how resources are allocated.
Market Economy: Households and firms interacting in markets determine resource allocation.
Mixed Economy: Most decisions result from market interactions, but the government plays a significant role.
Efficiency: Market economies tend to be more efficient, promoting productive and allocative efficiency.
Productive Efficiency: Goods and services are produced at the lowest possible cost.
Allocative Efficiency: Production aligns with consumer preferences; goods are produced up to the point where marginal benefit equals marginal cost.
Voluntary Exchange: Both buyer and seller are made better off by the transaction.
Additional info: Market failures can occur due to inefficiencies, government intervention, or externalities.
Economic Models
Economists use models—simplified representations of reality—to analyze economic issues. The process involves:
Deciding on assumptions
Formulating a testable hypothesis
Using data to test the hypothesis
Revising the model if necessary
Assumptions: Models require simplifications to be useful. Behavioral assumptions include consumers maximizing well-being and firms maximizing profit.
Hypothesis: A statement about an economic variable that can be tested.
Positive Analysis: Concerned with what is.
Normative Analysis: Concerned with what ought to be.
Additional info: Economic models are tested using statistical methods, but establishing causality can be challenging.
Microeconomics and Macroeconomics
Economics is divided into two main branches:
Microeconomics: Studies how households and firms make choices, interact in markets, and how government influences these choices.
Macroeconomics: Studies the economy as a whole, including inflation, unemployment, and economic growth.
Economic Skills and Economics as a Career
Studying economics develops analytical skills valuable in many careers. Economists help individuals, businesses, and governments make better decisions by analyzing choices and their consequences.
Additional info: Economics majors often have higher-than-average incomes, though causation versus correlation is debated.
A Preview of Important Economic Terms
Economics uses precise terminology. Key terms include:
Technology: The processes a firm uses to produce goods and services.
Capital: Manufactured goods used to produce other goods and services.
Appendix: Using Graphs and Formulas
Graphs in Economics
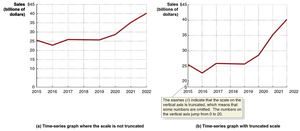
Graphs are essential tools for visualizing economic relationships. Common types include bar graphs, pie charts, and time-series graphs.
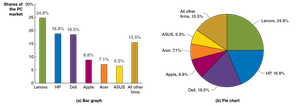
Plotting Price and Quantity Points
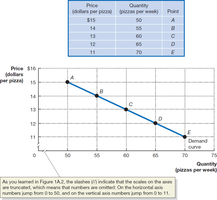
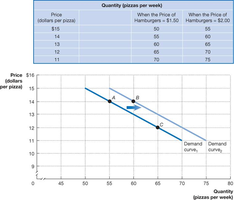
Graphs can illustrate the relationship between price and quantity, such as the demand curve for pizza. Each point represents a price-quantity combination.
Calculating the Slope of a Line
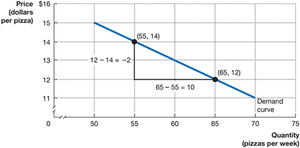
The slope of a line is calculated as the change in the y-axis variable divided by the change in the x-axis variable. For a demand curve, this shows how quantity demanded changes with price.
Formula:
Showing Three Variables on a Graph
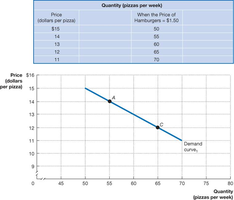
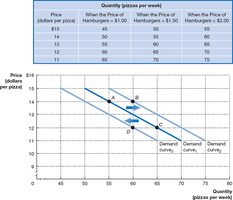
Graphs can show how a third variable affects the relationship between two others, such as how the price of hamburgers affects the demand for pizza.
Positive and Negative Relationships
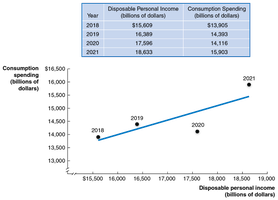
A positive relationship means both variables increase together; a negative relationship means one increases as the other decreases.
Determining Cause and Effect
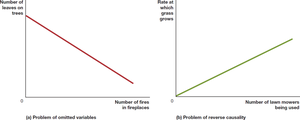
Graphs can illustrate relationships, but caution is needed when inferring causality. Omitted variables or reverse causality can mislead conclusions.
Linear and Nonlinear Relationships
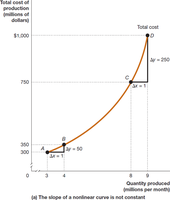
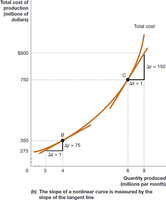
Most economic relationships are not perfectly linear. Nonlinear curves have varying slopes at different points, which can be approximated or measured with tangent lines.
Formula for Percentage Change
Percentage change measures the change in an economic variable from one period to the next, expressed as a percentage.
Formula:
Graphing Total Revenue
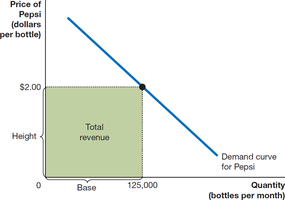
Total revenue is calculated as price times quantity. On a graph, it is represented by the area of a rectangle under the demand curve.
Formula:
Area of a Triangle
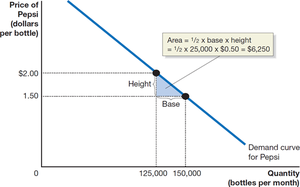
The area of a triangle is useful for calculating consumer or producer surplus in economics.
Formula:
Summary of Using Formulas
When using formulas in economics:
Understand the economic concept the formula represents.
Use the correct formula for the problem.
Check that the calculated number is economically reasonable.
