 Back
Microeconomics Midterm Study Guide: Key Concepts, Models, and Formulas
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Chapter 1: Economics, Foundations and Models
Three Key Economic Ideas
Microeconomics begins with three foundational concepts that guide economic reasoning and decision-making:
People are rational: Individuals use available information to make decisions that maximize their well-being.
People respond to economic incentives: Changes in costs and benefits influence behavior.
Optimal decisions are made at the margin: Decisions are based on comparing marginal benefits (MB) and marginal costs (MC).
The Economic Problem
Every society faces the challenge of scarcity, where unlimited wants exceed limited resources. This leads to trade-offs and opportunity costs:
Scarcity: The fundamental economic problem of having limited resources to meet unlimited wants.
Trade-off: Choosing more of one good or service means producing less of another.
Opportunity cost: The highest-valued alternative forgone when making a choice.
Economic Models
Economic models are simplified representations of reality used to analyze and predict economic outcomes. Models can be used for:
Positive analysis: Describes what is.
Normative analysis: Describes what ought to be.
Microeconomics vs. Macroeconomics
Microeconomics: Studies individual choices, market interactions, and government influence on households and firms.
Macroeconomics: Examines the economy as a whole, including inflation, unemployment, and growth.
Efficiency and Equity
Productive efficiency: Goods and services are produced at the lowest possible cost.
Allocative efficiency: Production matches consumer preferences; the marginal benefit equals marginal cost.
Equity: Fairness in the distribution of resources, which may not coincide with efficiency.
Chapter 2: Trade-offs, Comparative Advantage, and the Market System
Production Possibilities Frontier (PPF)
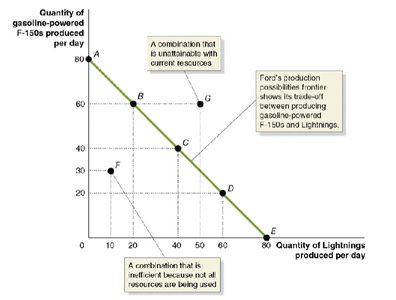
The PPF illustrates the maximum attainable combinations of two goods that can be produced with available resources and technology. It demonstrates trade-offs, opportunity costs, and economic growth.
Points on the PPF: Efficient use of resources.
Points inside the PPF: Inefficient use of resources.
Points outside the PPF: Unattainable with current resources.
Increasing Opportunity Costs
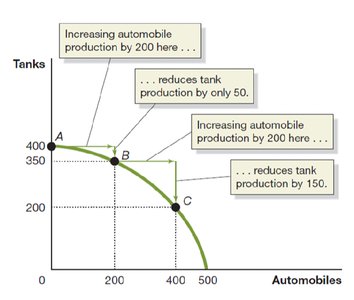
The PPF is typically bowed outward, reflecting increasing opportunity costs as more of one good is produced.
Comparative and Absolute Advantage
Absolute advantage: The ability to produce more of a good with the same resources.
Comparative advantage: The ability to produce a good at a lower opportunity cost than others.
Gains from trade: Specialization and exchange allow consumption beyond the PPF.
The Circular Flow Model
This model shows how households and firms interact in factor and product markets:
Households: Provide labor, capital, and natural resources.
Firms: Purchase factors of production and produce goods/services.
Factor market: Where resources are bought and sold.
Product market: Where goods and services are bought and sold.
Chapter 3: Where Prices Come From – Demand and Supply
Law of Demand
The law of demand states that, holding other factors constant, as the price of a product falls, the quantity demanded increases, and vice versa.
Substitution effect: Consumers switch to cheaper alternatives.
Income effect: Lower prices increase purchasing power.
Variables That Shift Market Demand
Changes in income (normal vs. inferior goods)
Changes in prices of related goods (substitutes and complements)
Changes in tastes
Changes in population and demographics
Changes in expected future prices
Natural disasters and pandemics
Law of Supply
The law of supply states that, holding other factors constant, as the price of a product rises, the quantity supplied increases, and vice versa.
Quantity supplied: The amount a firm is willing and able to supply at a given price.
Market Equilibrium
Market equilibrium: Occurs when quantity demanded equals quantity supplied.
Chapter 4: Economic Efficiency, Government Price Setting, and Taxes
Consumer and Producer Surplus
Consumer surplus: The difference between what consumers are willing to pay and what they actually pay.
Producer surplus: The difference between the price received and the seller’s cost.
Total surplus: The sum of consumer and producer surplus.
Market Efficiency and Price Controls
Price floors: Minimum prices set above equilibrium (e.g., minimum wage).
Price ceilings: Maximum prices set below equilibrium (e.g., rent control).
Effects: Price controls can create winners and losers, and reduce market efficiency.
Taxes and Market Outcomes
Taxes can reduce both consumer and producer surplus, and affect market efficiency.
Chapter 6: Elasticity – The Responsiveness of Demand and Supply
Price Elasticity of Demand
Elasticity measures how much quantity demanded responds to price changes.
Formula:
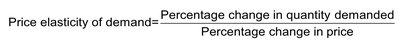
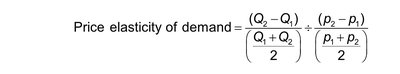
Midpoint formula:
Determinants: Availability of substitutes, passage of time, luxury vs. necessity, market definition, share of budget.
Elastic demand: Shallow slope; quantity demanded changes significantly with price.
Inelastic demand: Steep slope; quantity demanded changes little with price.
Perfectly elastic: Horizontal demand curve.
Perfectly inelastic: Vertical demand curve.
Price Elasticity of Supply
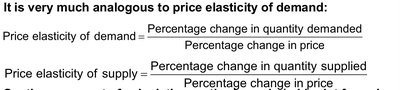
Measures responsiveness of quantity supplied to price changes.
Formula:
Income Elasticity of Demand
Normal goods: Quantity demanded increases as income increases.
Inferior goods: Quantity demanded decreases as income increases.
Chapter 8: Firms, the Stock Market, and Corporate Governance
Types of Firms
Sole proprietorship: Owned by a single individual.
Partnership: Owned jointly by two or more persons.
Corporation: Legal entity providing limited liability to owners.
Asset: Anything of value owned by a person or firm.
Present Value
Present value is the current worth of a future sum of money, given a specific interest rate:
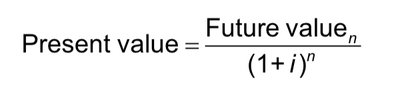
Formula:
Chapter 9: Comparative Advantage and Gains from International Trade
Sources of Comparative Advantage
Climate and natural resources
Relative abundance of labor and capital
Technological differences
External economies
Trade Barriers and Globalization
Tariffs: Taxes on imports.
Quotas and Voluntary Export Restraints (VERs): Limits on imported quantities.
Globalization: Increased openness to trade and investment.
Arguments against trade: Saving jobs, protecting wages, infant industries, national security, and dumping.
Review Tips
Review all graphs and tables for each chapter.
Understand definitions, models, and formulas.
Apply concepts to market situations and examples.
