 Back
Supply and Demand: The Foundations of Market Prices
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Where Prices Come From: The Interaction of Demand and Supply
Chapter Overview
This chapter explores how prices are determined in competitive markets through the interaction of demand and supply. It covers the concepts of demand and supply, the factors that shift these curves, and how equilibrium price and quantity are established and change in response to market forces.
The Demand Side of the Market
Demand Schedule, Quantity Demanded, and the Demand Curve
The demand schedule is a table showing the relationship between the price of a good and the quantity demanded at each price. The quantity demanded is the amount of a good that buyers are willing and able to purchase at a specific price. The demand curve is a graphical representation of the demand schedule, typically downward sloping, reflecting the law of demand.
Law of Demand: Ceteris paribus (holding everything else constant), when the price of a product falls, the quantity demanded increases; when the price rises, the quantity demanded decreases.
Demand curves are downward sloping because of the substitution effect and the income effect.
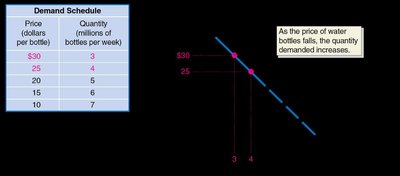
Shifts in Demand
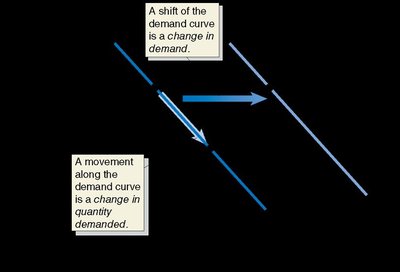
A change in demand refers to a shift of the entire demand curve, caused by factors other than the product's price. A change in quantity demanded is a movement along the demand curve due to a change in the product's price.
Change in Quantity Demanded: Movement along the same demand curve.
Change in Demand: Shift of the entire demand curve.
Factors that Shift Market Demand
Several variables can shift the demand curve:
Income: Normal goods (demand increases as income rises), inferior goods (demand decreases as income rises).
Prices of Related Goods: Substitutes (goods used in place of each other), complements (goods used together).
Tastes and Preferences: Changes in consumer preferences can increase or decrease demand.
Population and Demographics: More consumers or changes in demographic composition can shift demand.
Expected Future Prices: If consumers expect prices to rise, current demand may increase.
Natural Disasters and Pandemics: Can cause sudden shifts in demand.
The Supply Side of the Market
Supply Schedule, Quantity Supplied, and the Supply Curve
The Supply Schedule is a table showing the relationship between the price of a good and the quantity supplied at each price. The quantity supplied is the amount of a good that sellers are willing and able to sell at a specific price. The supply curve is a graphical representation of the supply schedule, typically upward sloping, reflecting the law of supply.
Law of Supply: Ceteris paribus, when the price of a product rises, the quantity supplied increases; when the price falls, the quantity supplied decreases.
Supply curves are upward sloping because higher prices provide an incentive for producers to supply more.
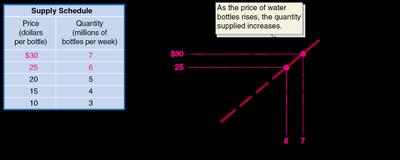
Shifts in Supply
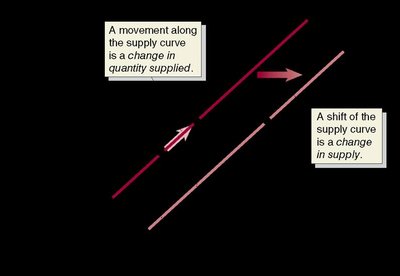
A change in supply refers to a shift of the entire supply curve, caused by factors other than the product's price. A change in quantity supplied is a movement along the supply curve due to a change in the product's price.
Change in Quantity Supplied: Movement along the same supply curve.
Change in Supply: Shift of the entire supply curve.
Factors that Shift Market Supply
Several variables can shift the supply curve:
Prices of Inputs: Higher input prices decrease supply; lower input prices increase supply.
Technological Change: Improvements in technology increase supply.
Prices of Related Goods in Production: Substitutes and complements in production can affect supply.
Number of Firms in the Market: More firms increase supply.
Expected Future Prices: If producers expect higher future prices, current supply may decrease.
Natural Disasters and Pandemics: Can reduce supply suddenly.
Market Equilibrium: Putting Demand and Supply Together
Market Equilibrium
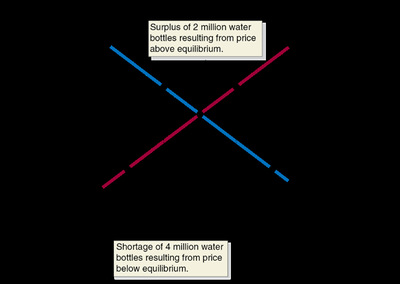
Market equilibrium occurs where the quantity demanded equals the quantity supplied. The corresponding price is the equilibrium price, and the quantity is the equilibrium quantity. At this point, there is no tendency for price to change unless there is a shift in demand or supply.
Surplus: Occurs when quantity supplied exceeds quantity demanded at a given price, leading to downward pressure on price.
Shortage: Occurs when quantity demanded exceeds quantity supplied at a given price, leading to upward pressure on price.
The Effect of Demand and Supply Shifts on Equilibrium
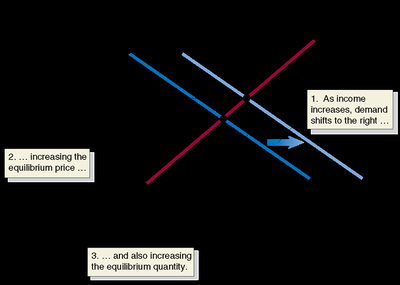
Effect of an Increase in Demand
When demand increases (shifts to the right), the equilibrium price and equilibrium quantity both rise, assuming supply is unchanged.
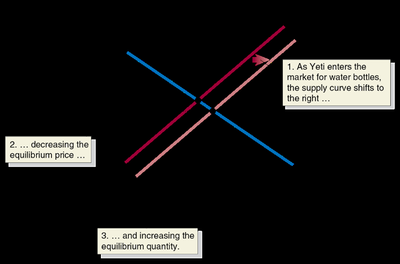
Effect of an Increase in Supply
When supply increases (shifts to the right), the equilibrium price falls and the equilibrium quantity rises, assuming demand is unchanged.
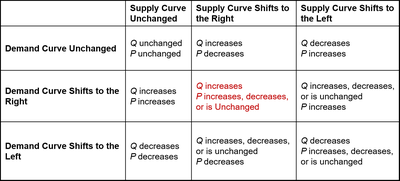
Summarizing Demand and Supply Shifts
The combined effects of shifts in demand and supply can be summarized in the following table:
Supply Curve Unchanged | Supply Curve Shifts to the Right | Supply Curve Shifts to the Left | |
|---|---|---|---|
Demand Curve Unchanged | Q unchanged P unchanged | Q increases P decreases | Q decreases P increases |
Demand Curve Shifts to the Right | Q increases P increases | Q increases P increases, decreases, or is unchanged | Q increases, decreases, or is unchanged P increases |
Demand Curve Shifts to the Left | Q decreases P decreases | Q increases, decreases, or is unchanged P decreases | Q decreases P increases, decreases, or is unchanged |
The Market System and the Role of Prices
Adam Smith and the Invisible Hand
Adam Smith described how individuals pursuing their own self-interest in a market system are led, as if by an "invisible hand," to promote the interests of society, even if that is not their intention. Market prices play a crucial role in coordinating economic activity.
Functions Performed by Market Prices
Prices communicate information about relative scarcity and value.
Prices coordinate the actions of buyers and sellers.
Prices motivate economic players to respond to incentives.
Practice and Application Questions
How do generational differences affect demand?
Why is oil production more sensitive to expectations of future prices than most other products?
Why did the prices of used cars skyrocket in August 2020 through April 2022?
How might government policies affect the market for recycled plastic?
Summary
Variables that influence demand include income, prices of related goods, tastes, population, expectations, and external events.
Variables that influence supply include input prices, technology, prices of related goods in production, number of firms, expectations, and external events.
Market equilibrium is illustrated using demand and supply graphs.
Demand and supply graphs can be used to predict changes in prices and quantities resulting from shifts in demand or supply.
