 Back
Merchandise Inventory: Principles, Methods, and Financial Impacts
Study Guide - Smart Notes
 Tailored notes based on your materials, expanded with key definitions, examples, and context.
Merchandise Inventory
Accounting Principles and Controls Related to Merchandise Inventory
Merchandise inventory is a key asset for merchandising and manufacturing companies. Proper accounting principles and controls ensure accurate classification, reporting, and safeguarding of inventory.
Consistency Principle: Businesses must use the same accounting methods and procedures from period to period. This enables comparability of financial statements across periods. If changes are made, they must be disclosed in the financial statement notes.
Disclosure Principle: Financial statements should provide sufficient information for external users to make informed decisions. Information must be relevant and reliable.
Materiality Concept: Only items significant to the business’s financial situation require strict accounting. Materiality depends on the size and impact of the item relative to the business.
Conservatism: When faced with multiple options, report the least optimistic figures. Anticipate no gains, but provide for all probable losses. Record assets at the lowest reasonable amount and liabilities at the highest reasonable amount. When uncertain, record an expense rather than an asset.
Inventory Controls: Good controls ensure inventory purchases and sales are authorized and properly accounted for. Controls include authorization of purchases, verification of receipt, proper recording, annual physical counts, and tracking inventory sold.
Data Analytics: Modern businesses use data analytics tools to monitor inventory levels, sales patterns, and optimize inventory management.
Merchandise Inventory Costs Under a Perpetual Inventory System
In a perpetual inventory system, inventory records are updated continuously as transactions occur. At period end, physical counts verify inventory balances.
Ending Inventory: Count units in ending inventory and assign dollar amounts.
Cost of Goods Sold (COGS): Determine units sold during the period and assign dollar amounts to COGS.
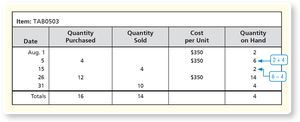
Perpetual Inventory Record Example
The perpetual inventory record tracks purchases, sales, and inventory balances for each item.
Inventory Costing Methods
Inventory costing methods determine how costs are assigned to COGS and ending inventory. Four methods are allowed by GAAP:
Specific Identification
First-In, First-Out (FIFO)
Last-In, First-Out (LIFO)
Weighted-Average
Specific Identification Method
This method assigns actual costs to each item sold and remaining in inventory. Used for high-value, unique items (e.g., automobiles, jewelry, real estate).
First-In, First-Out (FIFO) Method
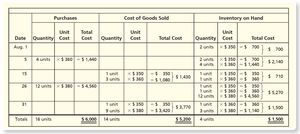
FIFO assumes the first items purchased are the first sold. COGS is based on oldest purchases; ending inventory reflects recent costs.
Cost of Goods Available for Sale: Total cost spent on inventory available for sale during the period.
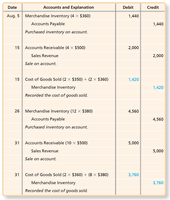
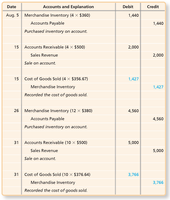
FIFO Journal Entries
Journal entries for inventory transactions under FIFO highlight the allocation of costs.
Last-In, First-Out (LIFO) Method
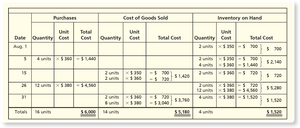
LIFO assumes the last items purchased are the first sold. COGS reflects recent costs; ending inventory contains oldest costs.
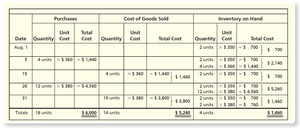
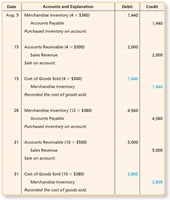
LIFO Journal Entries
Journal entries for inventory transactions under LIFO show the allocation of costs.
Weighted-Average Method
This method computes a new average cost per unit after each purchase. Ending inventory and COGS are based on the weighted-average cost.
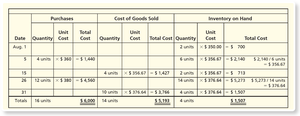
Weighted-Average Calculation Example
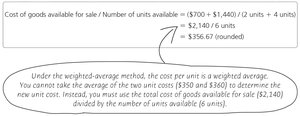
Weighted-average cost per unit is calculated as:
Formula:
Weighted-Average Journal Entries
Journal entries for inventory transactions under the weighted-average method show the allocation of costs.
Effects of Inventory Costing Methods on Financial Statements
Different inventory costing methods affect the income statement and balance sheet.
Income Statement: COGS is higher under LIFO than FIFO when costs are rising. Net income is lower under LIFO than FIFO in this scenario.
Balance Sheet: When costs are increasing, FIFO inventory will be higher and LIFO inventory will be lower.
Comparative Results Table
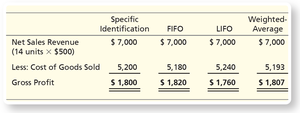
The following table compares net sales revenue, COGS, and gross profit for each method:
Method | Net Sales Revenue | Cost of Goods Sold | Gross Profit |
|---|---|---|---|
Specific Identification | $7,000 | $5,200 | $1,800 |
FIFO | $7,000 | $5,180 | $1,820 |
LIFO | $7,000 | $5,240 | $1,760 |
Weighted-Average | $7,000 | $5,193 | $1,807 |
Lower-of-Cost-or-Market Rule
The lower-of-cost-or-market (LCM) rule requires inventory to be reported at the lower of its historical cost or current market value (replacement cost).
Market Value: Generally means current replacement cost.
Adjusting Entry: If market value falls below cost, an adjusting entry reduces inventory value and recognizes a loss.
Effects of Inventory Errors on Financial Statements
Inventory errors can affect multiple accounts, including COGS, gross profit, and net income. Because ending inventory is used in other computations, errors propagate through financial statements.
Overstatement of Ending Inventory: Leads to understated COGS, overstated gross profit, and overstated net income.
Understatement of Ending Inventory: Leads to overstated COGS, understated gross profit, and understated net income.
Error Reversal: Inventory errors typically cancel out after two periods.
Inventory Turnover and Days’ Sales in Inventory
These ratios evaluate how efficiently a company manages its inventory.
Inventory Turnover Ratio: Measures how rapidly inventory is sold. Formula: High turnover indicates ease of selling; low turnover indicates difficulty.
Days’ Sales in Inventory: Measures the average number of days inventory is held. Formula: Important for inventory with a short shelf life.
Merchandise Inventory Costs Under a Periodic Inventory System (Appendix 6A)
In a periodic inventory system, inventory records are updated at period end. Purchases are accumulated, and ending inventory is determined by physical count.
Cost of Goods Sold Formula:
FIFO, LIFO, Weighted-Average: These methods are also applied under the periodic system, but calculations are made at period end.
Periodic Inventory Record Example
Periodic inventory records summarize purchases, sales, and inventory balances for each item at period end.
Summary
Merchandise inventory accounting involves principles, controls, and methods that impact financial statements. Understanding these concepts is essential for accurate reporting and effective business management.
