Table of contents
- 1. Introduction to Macroeconomics2h 13m
- 2. Introductory Economic Models1h 15m
- Production Possibilities Frontier (PPF) - Introduction and Productive Efficiency19m
- PPF - Increasing Marginal Opportunity Costs and Allocative Efficiency12m
- PPF - Outward Shifts9m
- PPF - Comparative Advantage and Absolute Advantage14m
- PPF - Comparative Advantage and Trade14m
- PPF - The Price of the Trade4m
- 3. Supply and Demand3h 28m
- Introduction to Supply and Demand5m
- The Basics of Demand7m
- Individual Demand and Market Demand3m
- Shifting Demand39m
- The Basics of Supply3m
- Individual Supply and Market Supply6m
- Shifting Supply29m
- Overview of Supply and Demand Shifts9m
- Supply and Demand Together: Equilibrium, Shortage, and Surplus6m
- Supply and Demand Together: One-sided Shifts20m
- Supply and Demand Together: Both Shift34m
- Supply and Demand: Quantitative Analysis41m
- 4. Elasticity2h 36m
- Percentage Change and Price Elasticity of Demand19m
- Elasticity and the Midpoint Method21m
- Price Elasticity of Demand on a Graph12m
- Determinants of Price Elasticity of Demand7m
- Total Revenue Test14m
- Total Revenue Along a Linear Demand Curve15m
- Income Elasticity of Demand24m
- Cross-Price Elasticity of Demand12m
- Price Elasticity of Supply13m
- Price Elasticity of Supply on a Graph4m
- Elasticity Summary10m
- 5. Consumer and Producer Surplus; Price Ceilings and Price Floors3h 19m
- Willingness to Pay and Consumer Surplus19m
- Willingness to Sell and Producer Surplus13m
- Economic Surplus and Efficiency19m
- Quantitative Analysis of Consumer and Producer Surplus at Equilibrium29m
- Price Ceilings, Price Floors, and Black Markets39m
- Quantitative Analysis of Price Ceilings and Price Floors: Finding Points21m
- Quantitative Analysis of Price Ceilings and Price Floors: Finding Areas55m
- 6. Introduction to Taxes and Subsidies1h 53m
- 7. Externalities56m
- 8. The Types of Goods1h 6m
- 9. International Trade1h 21m
- 10. The Costs of Production2h 35m
- 11. Perfect Competition2h 26m
- Introduction to the Four Market Models2m
- Characteristics of Perfect Competition6m
- Revenue in Perfect Competition14m
- Perfect Competition Profit on the Graph21m
- Short Run Shutdown Decision35m
- Long Run Entry and Exit Decision18m
- Individual Supply Curve in the Short Run and Long Run6m
- Market Supply Curve in the Short Run and Long Run9m
- Long Run Equilibrium12m
- Perfect Competition and Efficiency15m
- Four Market Model Summary: Perfect Competition5m
- 12. Monopoly2h 13m
- Characteristics of Monopoly21m
- Monopoly Revenue12m
- Monopoly Profit on the Graph16m
- Monopoly Efficiency and Deadweight Loss20m
- Price Discrimination22m
- Antitrust Laws and Government Regulation of Monopolies11m
- Mergers and the Herfindahl-Hirschman Index (HHI)17m
- Four Firm Concentration Ratio6m
- Four Market Model Summary: Monopoly4m
- 13. Monopolistic Competition1h 9m
- 14. Oligopoly1h 26m
- 15. Markets for the Factors of Production1h 26m
- 16. Income Inequality and Poverty36m
- 17. Asymmetric Information, Voting, and Public Choice39m
- 18. Consumer Choice and Behavioral Economics1h 16m
2. Introductory Economic Models
PPF - Increasing Marginal Opportunity Costs and Allocative Efficiency
Multiple Choice
Your bakery has workers who are cookie specialists and cake specialists. After a busy weekend, your bakery is short on cookies, and you need to rebuild your cookie inventory. To do this, you decide to shift workers away from cake production and into cookie production.
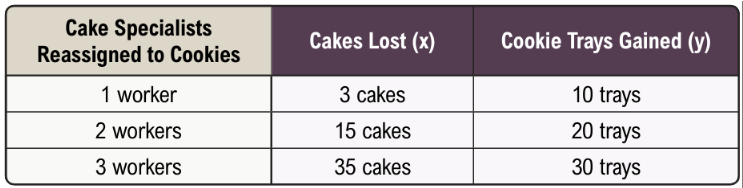
As you reassign each worker, you track how many cakes you give up and how many trays of cookies you gain:

What is the marginal opportunity cost of increasing cookie production from 10 trays to 20 trays?
A
5 cakes
B
10 cakes
C
12 cakes
D
15 cakes
0 Comments
Verified step by step guidance1
Identify the relevant data from the table for cookie trays increasing from 10 to 20 trays. At 10 trays, the cake loss is 3 cakes, and at 20 trays, the cake loss is 15 cakes.
Calculate the change in cakes lost when increasing cookie production from 10 trays to 20 trays by subtracting the cakes lost at 10 trays from the cakes lost at 20 trays.
Use the formula for marginal opportunity cost: \(\text{Marginal Opportunity Cost} = \frac{\text{Change in Cakes Lost}}{\text{Change in Cookie Trays}}\). Substitute the values: \(\frac{15 - 3}{20 - 10}\).
Simplify the fraction to find the marginal opportunity cost per tray of cookies produced, which represents how many cakes are given up for each additional tray of cookies between 10 and 20 trays.
Interpret the result as the total number of cakes lost when increasing cookie production by 10 trays, which is the marginal opportunity cost of increasing cookie production from 10 trays to 20 trays.
Related Videos
Related Practice
Multiple Choice
In the context of the production possibilities frontier (PPF), what does 'increasing marginal opportunity costs' mean?
154
views